 ·

Types of Life Insurance in Canada
There are really only two categories: term and permanent. Almost everything else is a product built on one of those two, sold under a different name. Here is how each type works, who it fits, and the few I will usually tell you to skip.
By Parvesh Benning, Licensed Life Insurance Broker
Updated: October 27, 2026
Types of Life Insurance in Canada
There are really only two categories: term and permanent. Almost everything else is a product built on one of those two. Here is how each type works, who it fits, and the few I will usually tell you to skip.
By Parvesh Benning, Licensed Life Insurance Broker, Updated: October 27, 2026
The names multiply, the actual choices do not. Once you know whether your need has an end date or runs for life, you have basically picked your lane, and everything below is detail inside it. Start with term or permanent, then narrow from there.
Here is the quick version before we get into the detail.
Term life
Covers a set period, usually 10, 20, or 30 years.
Lower premiums, no cash value.
Best when the need ends: a mortgage, kids at home, your working years.
Renews or converts, then expires.
Permanent life
Covers you for life, as long as premiums are paid.
Higher premiums, can build cash value over time.
Best when the need never ends: estate, a dependent with lifelong needs, final costs.
Stays in force, no expiry.
If you only read this far, here is the honest take: term is the right fit for most Canadians, most of the time. Permanent has real uses, but it gets sold a lot more often than it actually fits, and I will flag where that happens as we go.
And here is every type on this page at a glance, with where each one actually earns its place.
| Type | Best for | The trade-off |
|---|---|---|
| Term | A mortgage, young kids, an income people depend on | Renewing after the term costs far more |
| Whole life | A lifelong need, estate planning | Higher premium than term |
| Universal life | Flexible permanent coverage you will actively manage | More moving parts, cash value not guaranteed |
| Term-to-100 | Lifelong coverage at a lower cost | Usually no cash value to draw on |
| Simplified issue | A health issue, or you need coverage fast | Costs more than a fully underwritten policy |
| Guaranteed issue | A last resort when nothing else approves | Highest cost per dollar, plus an early waiting period |
| Mortgage (bank) | Rarely the right fit | The bank is paid, not your family |
| Group (employer) | A top-up while you are employed | Ends when the job does |
The rest of the page is just these eight, one at a time.
On this page:
- What is Traditional (Fully Underwritten) Life Insurance?
- What is Term Life Insurance?
- What is Permanent Life Insurance?
- What is No Medical Life Insurance?
- What is Mortgage Life Insurance?
- What is Group Life Insurance?
- What Type of Life Insurance Should I Get?
- Frequently Asked Questions About Life Insurance Types
What is Traditional (Fully Underwritten) Life Insurance?
Traditional life insurance is the fully underwritten path most term and permanent policies still run through. Before making an offer, the insurer reviews your health, lifestyle, medications, and family history, and sometimes pulls a report from your doctor.
What the insurer looks at depends on your age, the coverage amount, and your health. It can run the full review, or almost none of it:
What they may check
A nurse visit with bloodwork, a urine sample, or a report from your doctor. On smaller, simpler files, sometimes no exam at all.
What you get for it
It takes longer than no-medical coverage, but the insurer knows more, so a clean file generally earns a lower premium than any no-medical option.
This is where I start for most people in reasonably good health who are not in a rush. The no-medical routes further down exist for speed, or for health that would make this path hard, not as the default.
What is Term Life Insurance?
Term life insurance is a cheap way to get coverage for a period of time. You pick the length, usually 10, 20, or 30 years, the price stays level for that stretch, and if you pass away during that window your beneficiary gets the payout.
What happens after the term is where most people get caught. Many policies renew without a new medical, but at a much higher price, and renewals usually stop around age 85. A non-smoking man’s 10-year term on $750,000, bought at about 45, cost about $70 a month; the renewal at 55 came in at about $607 a month.
Most people don’t actually keep paying those higher renewal premiums. Instead, they either replace the coverage if their health allows or use the conversion option before the term ends. What to do when your term life insurance expires walks through each route.
This is the one most people actually need. It lines up with the years you carry the most financial weight: a mortgage, young kids, an income your family depends on. Cover those years, and once the mortgage is gone and the kids are grown, the need usually shrinks anyway.
It is the lowest-cost type for a simple reason. The insurer is only on the hook for a defined period, not your whole life, so the premium reflects that.
A few things to know before you buy term:
You choose the amount and the length. Those two numbers drive your premium. More coverage or a longer term costs more.
The payout goes to your beneficiary tax-free. Most families take it as a single lump sum. Some policies offer alternative settlement options, so it is worth asking what a given policy allows.
Most term policies can convert. Many let you switch to permanent later without a new medical, which matters if your health changes before the term ends. The window often closes between 65 and 75, so confirm it on any policy you are considering.
It works for more than just you. You can put term coverage on a whole family, add it for children, or attach it as a rider to an existing policy.
If your budget is tight and your need has an end date, this is almost always where I start the conversation.
What is Permanent Life Insurance?
Permanent life insurance covers you for your entire life, not a set number of years, as long as the premiums are paid. It is an umbrella term, not a single product. Whole life, universal life, and term-to-100 all sit underneath it.
The part that gets people interested is the cash value, though not every permanent policy builds it. Whole life and universal life can grow cash value over time, with a portion of each premium going into an account inside the policy. Term-to-100 usually skips that, giving you lifelong coverage at a lower cost with little or no cash value to draw on.
Where there is cash value, you can borrow against it, withdraw from it, or in later years surrender the policy and take the value out. Any of those moves can reduce or end the death benefit and may have tax consequences, so it is worth getting advice before you touch it.
The honest part
Permanent costs a lot more than term for the same death benefit, and that gap is the whole reason it gets oversold. It earns its keep in specific situations, not as a default for everyone. If you are buying it mainly as an investment, slow down. For many families, buying term and investing separately can do more than using permanent coverage as an investment.
Where it actually fits:
A need that never ends. Final expenses, or leaving something behind no matter when you pass.
A lifelong dependent. Coverage that has to outlast any 30-year term.
Estate and tax planning. Usually higher-income or business-owner files, once the simpler needs are handled.
Permanent is a tool for a specific job. Whole life, term-to-100 and universal life below are different versions of that tool, and our permanent life insurance guide compares them in more depth.
What is Whole Life Insurance?
Whole life is the most common form of permanent coverage. It covers you for life, the premium is set, and it builds guaranteed cash value over time under the contract. Two things are worth knowing before you compare quotes.
Limited pay
You pay for a set period, say 10 or 20 years, then payments stop while coverage and cash value continue for life. You front-load the cost so you are not paying premiums into your 80s. Manulife, for example, offers participating whole life on pay-10, pay-20, pay-to-90 and pay-to-100 schedules, though options and pricing vary by carrier and are subject to underwriting.
One check before you sign: make sure the short pay period is written into the contract. Some illustrations only stop premiums early if dividends hold up as projected, and those future values are projections rather than guarantees.
Participating vs non-participating
Participating pays dividends, your share of the insurer’s results, which can buy more coverage, cut premiums, or be taken in cash. Dividends are not guaranteed. Non-participating skips that and just provides the coverage at a lower cost.
What is Term-to-100 Insurance?
Term-to-100 is a permanent policy with level rates for life and no cash value component, simply the cost of insurance, payable for life. That trade is the point: you get lifelong coverage at a lower cost because you are not funding a cash value account.
Minimum-funded universal life with level costs acts in a similar fashion, and cost-wise the two are typically the same or sometimes even lower. Whole life usually costs a little more for the same amount, because part of each premium is building cash value.
Minimum-funded universal life
$363
Term-to-100
$368
Whole life, paid for life
$391
Starting monthly premiums for a man, age 40, non-smoker, $500,000 of lifelong coverage. Based on current carrier rates, illustrative only, subject to underwriting and change.
The catch is simple. With no cash value there is nothing to borrow against, and if you cancel you typically walk away with nothing. It fits someone who wants coverage that never ends and has no interest in the investment side.
What is Universal Life Insurance?
The biggest difference between universal life and whole life is flexibility. With universal life you can strip out the investment side entirely and have just insurance; whole life always combines the two. It covers you for life, the premiums are flexible, the death benefit can be adjusted, and any cash value growth is not guaranteed. More control, more responsibility.
The flexibility cuts both ways, so it helps to see it plainly:
What you gain
You pick a premium within a set range and can adjust it as your income shifts. The death benefit can usually be changed too. Lowering it is generally simple. Raising it normally means new underwriting, including a medical.
What you take on
The cash value is not guaranteed. Guaranteed-interest accounts carry a minimum rate, which can be as low as 0%, while index and managed accounts can go down as well as up. The bigger risk is a cost of insurance that rises every year: underfund that kind of policy and it can lapse.
This is the type I am most careful with. When someone shows me a universal life policy, the first thing I ask is whether it is a level cost or a yearly renewable term, because a yearly renewable cost of insurance rises every year. It can work well for someone with variable income or a real estate-planning reason who will actually manage it. For most people who just want lifelong coverage without homework, term-to-100 or whole life is the simpler call.
What is Funeral Expense Insurance?
Funeral insurance, also called burial or final expense insurance, is a small permanent policy built to cover the costs around your death rather than replace an income. Coverage is modest, usually enough for a funeral and related expenses, and it lasts for life as long as premiums are paid.
Think of it as a narrow tool, useful for one job and the wrong size for most others:
Built for the funeral and the bills right around it, so that final cost does not land on your family.
Not built for a mortgage, a child’s education, or lost income. For those you want term or a larger permanent policy, not this.
Where it fits is the older client with no dependents or big debts who just wants the funeral handled. It is often sold as a no-medical product, which is why it fills late-night ads aimed at seniors. Right tool for that person, oversized as a first reaction for everyone else.
What is No Medical Life Insurance?
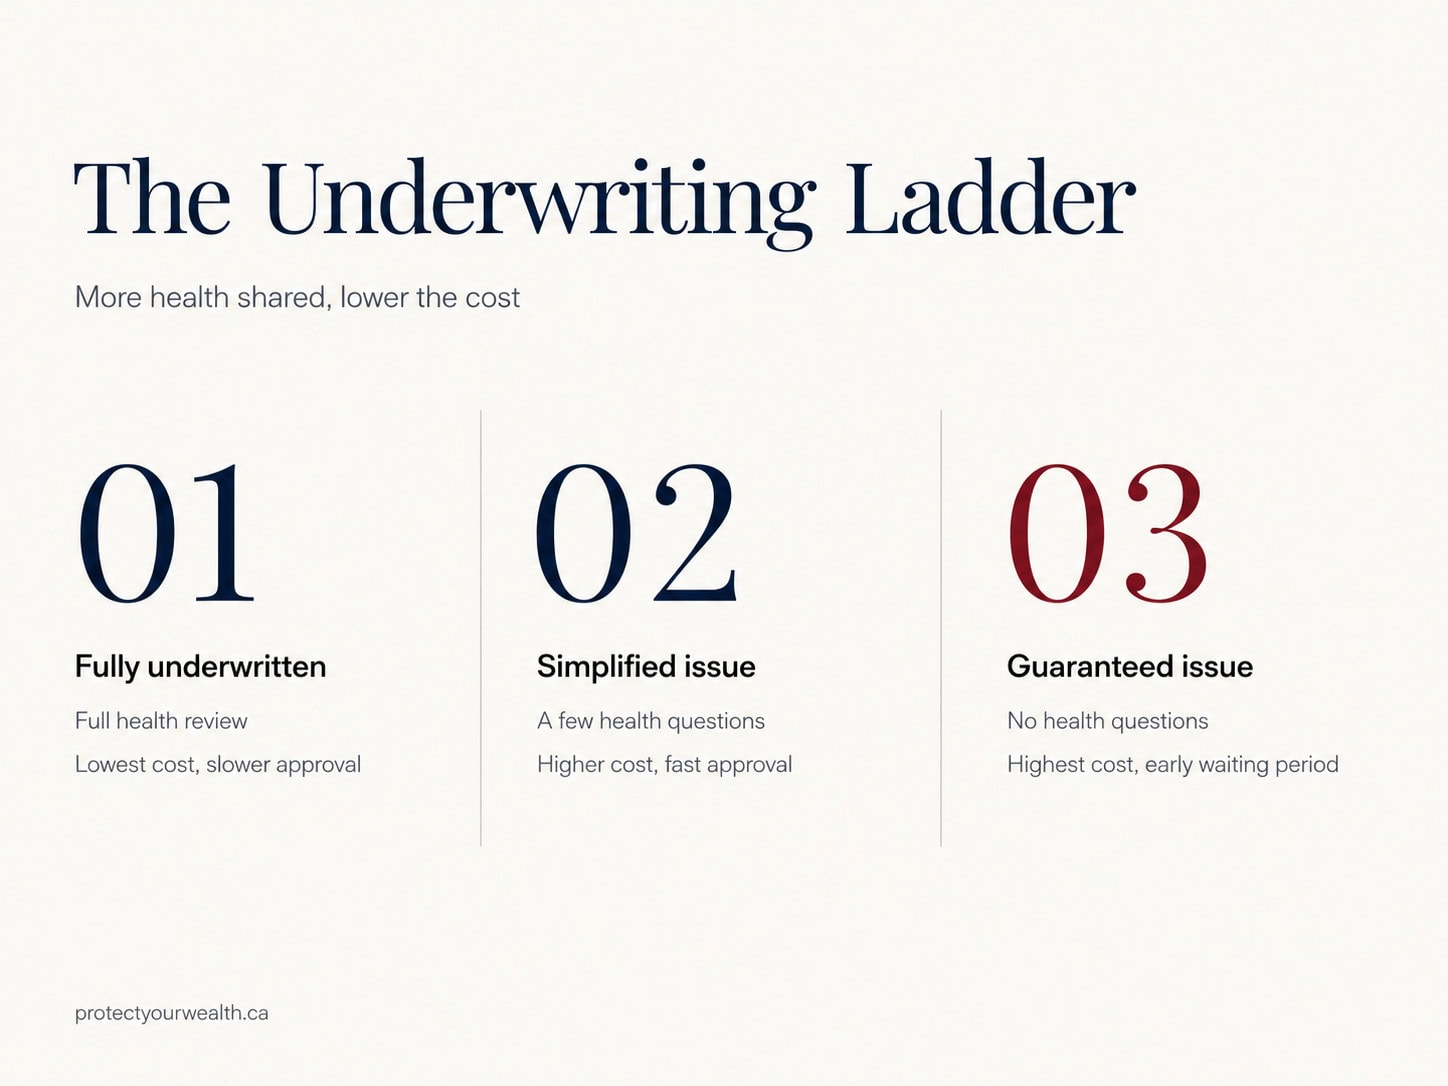
No-medical life insurance is coverage you can get without the exam. No nurse visit, no bloodwork. You answer a few health questions, or sometimes none at all, and approval is fast. That speed is the whole appeal.
The trade is price. When the insurer knows less about your health, they price in the unknown, so no-medical premiums generally run higher than a fully underwritten policy for the same coverage. You are paying for convenience, not getting a deal.
It really comes down to two groups:
Need it fast
You want coverage in days, not weeks, and would rather skip the underwriting wait.
Hard to insure
A health condition makes a traditional policy tough to land, or it would come back heavily rated.
One caution before you assume this is your route. No-medical is not one product, it is a ladder, and where you land on it changes the price a lot. A healthy person who grabs no-medical out of impatience is usually overpaying for something a quick underwritten policy would beat. Let a broker check whether you would qualify for standard coverage first. The two rungs below are where most of that decision gets made, and our simplified issue vs guaranteed issue guide goes deeper.
What is Simplified Issue Insurance?
Simplified issue is the higher rung on the no-medical ladder. No exam, but you do answer a set of health questions, and your answers decide whether you qualify and at what price. Fewer questions and cleaner answers generally mean a better rate.
It can be sold as term or permanent, and the question set is not one-size-fits-all. Carriers tier it, and the tier you land on drives the cost. To give a sense of how that ladder looks in practice:
Fewer, easier questions, immediate coverage. Canada Protection Plan, through its Simplified Elite and Express Elite tiers, and Assumption Life, through Platinum Protection and its lower tiers, both run multiple simplified levels. The cleaner your health answers, the higher the tier you reach and the lower the premium, with full coverage starting from day one.
More questions you cannot pass, graded or deferred coverage. If the health answers do not clear, you may still be approved on a tier where the full death benefit only applies after a waiting period, usually a couple of years. Covered, but with a catch in the early years.
This is exactly where a broker earns the fee, except there is no fee to you. The same health profile can land on very different tiers across carriers, and matching you to the one that grades your situation most kindly is the difference between a fair rate and an expensive one. Tiers, questions, and pricing vary by carrier and are subject to the insurer’s current rules.
What is Guaranteed Issue Insurance?
Guaranteed issue is the bottom rung: no exam, no health questions, approval is essentially automatic as long as you fit the age window. That is its only real advantage, and it is a big one for the right person. You cannot be turned down for your health.
The trade-offs are real, so go in clear-eyed:
Age-gated
Commonly available from about age 18 to 75, and to 80 with some carriers. Coverage is capped, usually at $100,000 or less.
Highest price per dollar
Because the insurer takes everyone, the premium per dollar of coverage is the steepest of any type here.
Graded early years
The full death benefit typically applies only after a waiting period, often two years, except for accidental death. A death from illness in that window usually returns the premiums paid instead of the full amount.
This is a last resort, not a starting point. It exists for people who genuinely cannot qualify anywhere else, often older applicants with serious medical conditions. Before anyone lands here, it is worth having a broker test whether a simplified tier or even a rated underwritten policy would take you, because either one usually beats guaranteed issue on price. Specifics vary by carrier and are subject to current rules.
What is Mortgage Life Insurance?
Mortgage life insurance, the kind the bank offers when you sign your mortgage, is creditor insurance: it pays the lender, not your family, and the payout shrinks as your balance drops. I rarely recommend it, and here is the plain reason why.
First, a naming trap worth clearing up. Bank mortgage life insurance is not the same as the mandatory CMHC-type default insurance required when your down payment is under 20%. That mandatory product protects the lender if you default. The optional one the branch upsells is life coverage tied to your mortgage. Different things, often confused at the same signing table.
Where it falls short against an individual policy:
The payout shrinks
As you pay down the mortgage, the benefit drops with it, but the premium usually does not.
The bank is the beneficiary
The money clears the mortgage. Your family does not get to decide how to use it.
It is not portable
Switch lenders or move, and the coverage usually ends. You start over, older, maybe less healthy.
A personally owned term policy for the mortgage amount fixes all three. The benefit stays level, your family controls it, and it follows you regardless of which lender holds the mortgage. Same job, better tool, and often a similar or lower price. If a bank has offered you mortgage insurance, that is the moment to compare it against your own policy before you sign.
What is Group Life Insurance?
Group life insurance is the coverage your employer provides as part of a benefits package. It is easy to get, usually requires no medical, and is often free or close to it. Treat it as a nice extra, not your real plan.
The good part is genuine. No exam matters if your health would make individual coverage hard to land, and the price is hard to beat when the employer foots the bill. Typical coverage runs about one to two times your salary, with the option to buy a bit more.
Here is why I never let a client lean on it alone:
- It leaves when you do. Change jobs or get laid off and the coverage usually ends with the paycheque, often at the worst possible time.
- It is rarely enough. One or two times salary does not clear a mortgage and raise a family. It is a top-up, not a foundation.
- You cannot shape it. It is a set package, with no choosing the amount, the length, or the structure to fit your situation.
Conversion to an individual policy on the way out is sometimes offered, but the price can jump sharply. The better move is to own a personal term policy that stays with you no matter where you work, and let the group coverage sit on top as a bonus. Keep the extra. Just do not build the house on it.
What Type of Life Insurance Should I Get?
I always recommend you address your need for insurance first: how much would have to be replaced, and for how long. For most Canadians that points to term, because most of what they carry has an end date. Permanent earns its place for the part of the need that never ends.
After 25 years of placing these, I treat it as two decisions, made in this order:
The second decision is the one people skip. I always look at fully underwritten as the first option to see if it is viable, simply from a cost perspective. Choosing the right product and then applying the wrong way can cost as much as choosing the wrong product.
What lifelong coverage costs compared with term
Coverage for life is expensive when you are young and much less so later. Here is the same healthy man priced both ways at four ages:
Age 30
20-year term $28 vs lifelong $233
about 8x
Age 40
20-year term $43 vs lifelong $363
about 8x
Age 50
20-year term $120 vs lifelong $570
about 5x
Age 60
20-year term $387 vs lifelong $976
about 2.5x
Green bar = term as a share of the lifelong premium. Starting monthly premiums for a man, non-smoker, $500,000. Lifelong is the lowest-priced permanent option at each age. Based on current carrier rates, illustrative only, subject to underwriting and change.
That shrinking gap is why permanent comes up most with older clients and smaller amounts. It is also why you do not have to be all or nothing on it: any amount of the coverage can be lifelong and the rest term, say $100,000 for life with $400,000 of term on top.
Where people usually start, by situation
A mortgage and young kids
Level term for 20 to 30 years, sized to the debt plus income. A small permanent piece only if the budget is comfortable.
A couple with no kids
Term sized to the mortgage. No need to over-buy.
Only bank or work coverage
Your own term on top. Keep the old cover until the new policy is approved and in force.
In your 60s, term ending
Term to 80 or 85, a partial conversion, or a small permanent policy, compared against the market first.
Final expenses, later in life
A small permanent policy, often $25,000 to $50,000. See our guide to life insurance for seniors.
A health issue or a past decline
Fully underwritten and simplified priced side by side, with simplified kept as the floor. More on pre-existing conditions.
Incorporated, with retained earnings
Term for personal debts, plus corporate-owned permanent only with a stated purpose.
Buying for a child
A small permanent policy, sized by the premium you want to pay, since there is no income to replace.
These are patterns from real files, not rules. Your budget, health and family can move any of them.
Match the tool to the job. For many families, term plus investing separately is the better fit. In the right situation, though, a well-funded cash-value policy is a genuine tax-advantaged asset: growth inside an exempt policy is sheltered within the tax limits, but taking money out can be taxable, so get tax advice before you rely on it. Estate planning, a corporation with retained earnings, a maxed RRSP and TFSA: that is where permanent earns its place as an investment, not just as coverage.
The reason a broker matters here is simple. I am not tied to one company, so I can put your situation in front of several carriers and find the one that prices yours most fairly. That comparison costs you nothing, and it is the whole point of working with an independent broker.
Frequently Asked Questions About Life Insurance Types
Q1
What is the difference between simplified issue and guaranteed issue?
Simplified issue asks a set of health questions and uses your answers to decide the tier and price, with no medical exam. Guaranteed issue asks no health questions at all and cannot turn you down for health, but it carries the highest price per dollar of coverage and usually a waiting period before the full benefit applies. Simplified is the better deal if your health answers can clear it.
Q2
What is a fully underwritten policy?
It is the standard application path most term and permanent policies go through. The insurer reviews your health history and, depending on your age and the amount, may ask for a nurse visit, bloodwork or a report from your doctor. Many younger applicants with clean files skip the exam entirely through accelerated underwriting, a faster review that relies on your answers and database checks. Because the insurer knows more, a healthy applicant generally gets a lower premium than on a no-medical policy.
Q3
What is underwriting?
Underwriting is how the insurer reviews your application, health, and lifestyle to decide whether to offer coverage and at what price. The more an insurer knows, the more precisely they can price the risk, which is why a clean underwritten file often beats a no-medical rate.
Q4
Is funeral insurance the same as life insurance?
Funeral or final expense insurance is a small type of permanent life insurance aimed only at covering end-of-life costs. It offers a smaller benefit than a standard term policy because its job is narrow: the funeral and the bills around it, not replacing an income or clearing a mortgage.
Q5
Which type of life insurance is best for most people?
For most Canadians, term is the right starting point. It is the most affordable way to cover the years you carry a mortgage, raise children, or support an income, and it fits the majority of needs. Permanent, no-medical, and final expense each solve a more specific problem. Comparing options across carriers with a broker is the simplest way to land on the right one for your situation and budget.
Q6
What are the three main types of life insurance?
The three most often named are term, whole life and universal life. Term covers a set period, while whole life and universal life cover you for life and can build cash value. Term-to-100 is a fourth, lifelong coverage with no cash value. Underneath the names there are really two families: term is like renting insurance for a period of time, and permanent is like owning your policy.
Q7
What should I do if I have been declined for life insurance?
Don’t assume the answer is the same everywhere. Just because one company declined you doesn’t mean every company will, because carriers read the same history differently. A broker gathers your full health and lifestyle picture and, where it helps, runs an anonymous preliminary check with an underwriter before anything new is submitted. Guaranteed issue, available from about age 18 to 75 with no health questions, is the last resort rather than the first move. Our guide to being denied life insurance covers the common reasons and next steps.
Finding the right type for your situation
The hard part is rarely understanding the types. It is matching the right one to your life and then finding the carrier that prices your situation fairly. That second step is where an independent broker earns their keep, and it costs you nothing.
Talk to a broker directly
I want to go through the options properly and design the coverage around your actual needs rather than simply choosing a policy based on price. That means looking at what you need covered, for how long, your health history and any coverage you already hold, before recommending a product or a carrier.
We are independent and work with nearly 20 Canadian carriers. We provide life insurance and segregated fund solutions, including term, permanent, no-medical, and critical illness coverage.
Get in touch or call 1-877-654-6119 to go over your options.
Based in Hamilton and serving clients across Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, New Brunswick, and Nova Scotia.





