 ·

How Life Insurance Riders Work in Canada
By Parvesh Benning, Licensed Life Insurance Broker
Not every rider on your carrier’s menu is worth the cost.
This guide covers every type of life insurance rider available in Canada: coverage riders, critical illness, disability, and other add-ons. For each one, we explain what it does, when it makes sense to add, and which clients we tell to skip it.
Updated: May 7, 2026
How Life Insurance Riders Work in Canada
By Parvesh Benning, Licensed Life Insurance Broker
Not every rider on your carrier’s menu is worth the cost.
This guide covers every type of life insurance rider available in Canada: coverage riders, critical illness, disability, and other add-ons. For each one, we explain what it does, when it makes sense to add, and which clients we tell to skip it.
Updated: May 7, 2026
A life insurance rider is an optional add-on to a life policy that gives you extra protection: critical illness, disability, child coverage, accidental death, and more. Some are free. Some you should skip.
Riders let you add critical illness, disability, child coverage, and other benefits to your life insurance policy without buying separate policies. The catch is that not every rider available on your carrier’s menu is worth the premium. Some are essentially free. Some are priced fine but rarely pay out.
This guide walks through every rider type sold in Canada, what each one does, our broker take on which clients should add them and which should skip them. We work with the best life insurance companies in Canada, and the rider menu varies meaningfully across them.
On this page:
What are life insurance riders?
Life insurance riders are optional add-ons that extend or enhance a base life insurance policy: critical illness coverage, disability protection, child coverage, accidental death benefit, and several others. They sit on top of your base policy. Most cost extra. A few come built in for free.
The reason riders exist is simple. A basic term or permanent policy pays out on death. That’s it. If you want anything beyond that, a lump sum on a cancer diagnosis, premiums waived if you become disabled, the option to add more coverage later without re-qualifying medically, you need either a rider or a separate standalone policy.
Both routes work. They trade off differently.
Add as a rider
One application. One policy to manage. Premium is usually lower than buying the same coverage standalone.
Coverage amounts cap lower than standalone equivalents. The rider is tied to the base policy: if the life policy ends, the rider ends with it.
Buy as a separate policy
Higher coverage amounts available. Independent of the life policy. You can choose the strongest carrier for that specific product, even if it’s not the same one writing your life policy.
Two applications. Two policies. Total premium is usually higher than the rider equivalent.
How do life insurance riders work?
Each rider has its own trigger, its own benefit type, and its own rules. Some pay a lump sum when a specific event happens (critical illness, accidental death). Some waive your premium if you become disabled. Some let you access part of the death benefit early while you are still alive (terminal illness, long-term care). Some let you buy more coverage later without re-qualifying medically.
Lumping them together as “riders” hides the real question. The real question is whether a specific rider does something useful in your specific situation. A waiver of premium rider on a term policy and a child term rider are not comparable products. They share the word “rider” and almost nothing else.
Riders are mostly offered on fully underwritten term and permanent life insurance. Simplified-issue and guaranteed-issue policies have a much shorter rider menu, sometimes none at all.
Types of life insurance riders
Riders fall into four broad categories: coverage riders that add extra death benefit, critical illness riders that pay on diagnosis, disability riders that protect your premium or pay an income, and a fourth bucket of everything else (long-term care, hospitalization income, family income, fracture).
Within each category, the menu is different at every carrier. Some riders are optional add-ons. Some are bundled into the base policy automatically. Some, like accelerated death benefit on a terminal diagnosis, are built into most policies whether you ask for them or not.

Life insurance coverage riders
Coverage riders add additional death benefit to your base policy. They include term riders, child term riders, spousal riders, parent protection riders, guaranteed insurability, accidental death and dismemberment, and accelerated death benefit. Each one extends or modifies the base coverage in a different direction.
Term rider
A term rider adds extra term life coverage to your base policy at a shorter duration than the base. The point is to layer protection where you actually need it most: the years when your mortgage is highest, your kids are youngest, and your income is most exposed.
The strategy is called laddering. Stack a Term 10 rider on top of a Term 30 base policy and your total coverage is high in years 1-10, then drops to the base amount once the rider expires. By that point your mortgage is paying down, your kids are independent, and your need for coverage is genuinely lower. This is one of the more useful rider categories on a family life insurance policy.
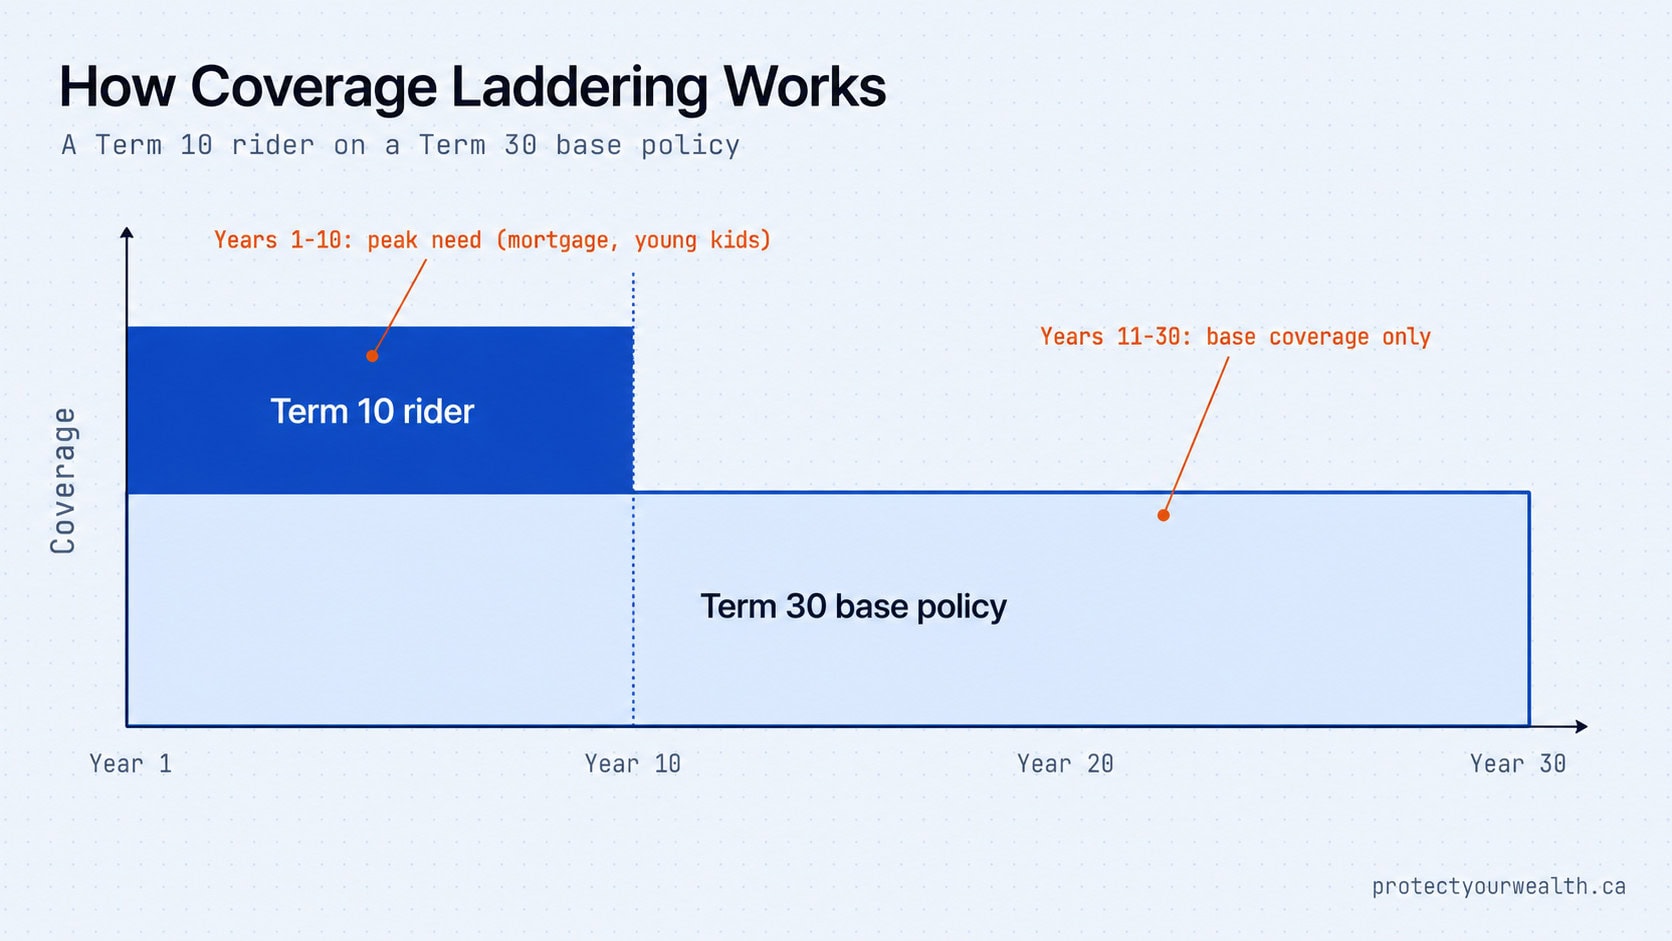
Three rules on laddering:
- The rider term must be equal to or shorter than the base. A Term 10 base with a Term 20 rider is a trap. We get into why in the critical illness section below.
- Use it when your need for coverage is genuinely time-bound. Mortgage. Young kids. Early-career income exposure.
- Don’t ladder beyond what the math supports. More layers means more renewals to manage. At some point a single longer term is simpler.
Child term rider
A child term rider provides life insurance coverage on your kids, usually up to a small benefit amount, attached to your policy at minimal extra cost. What I showed you is actually the exact same plan I did for my own kids.
The mechanics: one rider covers all your children, including kids born or adopted later. Coverage typically caps at $25,000 to $30,000 per child. No medical exam on the kids in most cases, though some carriers will ask basic health questions. The benefit is small but the price is small too. Many carriers price the rider in the $5 to $8 per month range regardless of how many children you have.
Two reasons it earns its place. First, if something happens to your child, you don’t want to be making funeral or counselling cost decisions on a credit card. Second, when the child turns 25 or so, the coverage usually converts to a permanent policy without medical underwriting. That conversion option is the real value. A child diagnosed with a serious condition between birth and adulthood is locked out of regular underwritten coverage. The rider preserves their insurability for life.
For more on coverage options for kids: life insurance for children in Canada.
Spousal rider
A spousal rider extends your life insurance coverage to your spouse on the same policy, instead of buying them a separate standalone policy. One application, one premium, two insureds.
The trade-off is coverage amount. Spousal riders typically cap at a lower amount than the base policy. If your spouse needs significant coverage, two separate policies is usually the better answer because each can be sized to the actual need. The spousal rider also ends if the base policy ends or if the primary insured dies, which means a surviving spouse can lose coverage at the worst possible time.
Where the rider works is short-term coupled coverage at modest amounts: young couples, early in the mortgage, both incomes needed. Where it falls apart is anything where each spouse has a different coverage need, a different timeline, or a meaningfully different health profile. Two policies is often cleaner. We compare both routes here: single life vs joint life insurance policies.
Parent protection rider
A parent protection rider adds life insurance coverage on your parents to your own policy, typically to cover final expenses or estate-related costs after they pass.
One rider per parent. Each parent is underwritten separately because age and health vary. Coverage amounts are limited and the rider is rarely the right product for serious final-expense or estate-protection needs. For most clients with aging parents, a small standalone policy on each parent (or guaranteed-issue coverage if the parent is uninsurable) is more practical than the rider.
Guaranteed insurability rider
A guaranteed insurability rider lets you buy additional coverage at set future dates without re-qualifying medically. No medical exam, no health questions, no risk of being declined or rated based on changes in your health since the original policy was issued.
There are two situations where I see this rider really stand out.
1. Disability insurance with rising income
A client sets up a disability policy at the coverage amount that matches their income today. With a guaranteed insurability rider on that policy, as their income rises over time they can increase their coverage to match without requalifying. Income goes up, coverage scales with it, no new medical, no underwriting risk that some condition has developed in the meantime. I see this used often.
2. Permanent policies on children
A child has a permanent life policy issued before age 18 with a guaranteed insurability rider. Years later that child can purchase additional coverage at fixed milestones without medical evidence. I have seen this play out firsthand. A child became uninsurable for normal life insurance, but the rider let them add $50,000 every few years up to $250,000 in additional coverage. That is real money the family could not have accessed any other way.
For most healthy adults buying a term policy in their 30s and 40s, the rider is rarely exercised because re-qualifying medically when you actually need more coverage usually produces a better rate. Where the rider earns its cost is the case where insurability itself is at risk, on a child policy, or where the original underwriting locks in a rate the client wants to preserve regardless of future health.
Accidental death and dismemberment (AD&D) rider
I do not like suggesting the accidental death and dismemberment rider. To me, it is a moot point. You already have the coverage, and statistically it is not something that pays out.
An AD&D rider pays an additional benefit on top of your base death benefit if you die or lose a limb or function in an accident. Lose one limb, you might get 50% of the death benefit. Lose two or more, you typically get 100%. Die in an accident, your beneficiaries receive an extra payout on top of the base policy.
In 25 plus years, I have personally never seen this rider pay out. I am not saying it does not pay, because obviously it can in the right situation. I just have not dealt with one of those claims.
The reason I steer clients away by default comes down to what insurance is actually for. Insurance is about peace of mind. Real peace of mind comes from knowing exactly what your beneficiaries will receive, regardless of how you die. AD&D creates a false sense of security where the client thinks they are getting an extra benefit, but the payout depends entirely on the circumstances of the death or injury. Die of a heart attack at 55? AD&D pays nothing. Die in a car accident at 56? AD&D pays the rider amount. Same family, same financial gap, completely different outcome.
I would rather make sure the client has the right amount of base coverage. If you need $1,000,000, I would rather get you the right $1,000,000 life insurance policy than have you carry $500,000 of base coverage plus an AD&D rider that only pays in specific accident-related situations.
Where AD&D can earn its place
There are specific occupations and lifestyles where AD&D is worth a real conversation. A crane operator, a miner, someone working in a more dangerous industrial setting, or someone whose lifestyle includes higher-risk activities like backcountry skiing, racing, or mountain climbing. The exposure to accidental injury or death is meaningfully higher than for the average client.
In those cases, if the client understands exactly what the rider does and does not cover, and they still want that extra layer of accident-only coverage on top of their proper base policy, then I will look at it with them. The base coverage still has to come first. AD&D is the supplement, never the primary plan.
The default position holds for most clients. Insurance is about peace of mind, and peace of mind comes from getting the right amount of base coverage at the right structure, not from layering accident-only riders on top of an undersized policy.
Accelerated death benefit
An accelerated death benefit lets you access part of your life insurance death benefit while you are still alive if you are diagnosed with a terminal illness. The funds come out of your future death benefit, so whatever you take now reduces what your beneficiaries receive later.
This rider is built into most modern term and permanent policies in Canada at no additional cost. You usually do not need to ask for it or add it. Check the rider list on your policy contract; if it is not there, your advisor can tell you whether the carrier offers it as an add-on.
Three things to know about how it works:
| Element | How it typically works |
|---|---|
| Trigger | Diagnosis of a terminal illness with life expectancy of 12 months or less, confirmed by a physician. |
| Maximum advance | Lesser of 50% of the death benefit or $250,000. On a $2M policy, the most you can advance is $250,000. The remaining $1.75M still passes to beneficiaries. |
| Use of funds | No restrictions. Medical bills, home modifications, paying off debts, travel. The carrier does not ask for receipts. The advance is paid as a lump sum to the policy owner. |
The rider is genuinely useful for the situations it is designed for. The thing to be clear on: it is an advance, not extra money. Whatever you draw down reduces the final benefit. For most clients this is the right trade because the cash matters most when the diagnosis is terminal, but the math should be explained clearly so the family understands what the beneficiaries will actually receive.
Critical illness benefit riders
Critical illness riders pay a lump sum if you are diagnosed with a covered illness, on top of your life insurance death benefit. The most common covered conditions are cancer, heart attack, and stroke. Comprehensive policies typically cover 24 to 26 illnesses depending on the carrier.
Critical illness rider
The biggest critical illness rider mistake I see is when the rider term is longer than the base life insurance term.
Here is the trap. Client buys a Term 10 life insurance policy and adds a Term 20 critical illness rider on top of it. After year 10, the life insurance side has to renew. Renewal rates on a Term 10 policy are typically several times the original premium, often more than the equivalent market rate for a fresh Term 20. The base policy is now hugely expensive, but the client has the critical illness rider locked to that base, so they keep paying.
The rule is simple. The rider term must be equal to or shorter than the base. A Term 20 base with a Term 10 or Term 20 critical illness rider works. A Term 10 base with a Term 20 critical illness rider is the trap.
As an industry, I think it should not be allowed to attach a longer rider to a shorter base. But that is my two cents. As long as carriers offer it, the responsibility falls on the broker to structure it correctly.
Bundle vs split-carrier decision
It does not always make sense to bundle life and critical illness with one carrier just because the rider option is on the table. Carriers price life and critical illness very differently from each other. Canada Life, for example, can be cheaper on critical illness but more expensive on life. So the cleanest answer for that client is to write the life policy at one carrier and the critical illness policy at another, even though it means two policies instead of one.
The exception is the client who specifically wants everything under one roof. That is a real preference and worth respecting. But cost-wise, split carriers will often beat the bundled rider. We cover this in more detail here: top critical illness insurance carriers in Canada.
Child critical illness rider
A child critical illness rider pays a lump sum if your child is diagnosed with a covered critical illness. Coverage and condition lists vary by carrier, but the typical Canadian setup covers 5 to 15 childhood illnesses including cancer, type 1 diabetes, congenital heart disease, cerebral palsy, cystic fibrosis, muscular dystrophy, and major organ transplant.
The benefit pays out to you, the parent, with no restrictions on how the funds are used. Medical bills, time off work, modifications to the home, travel for treatment.
The case for it is the same as the case for any child-focused coverage. If something serious happens, you do not want to be making coverage and treatment cost decisions while also figuring out how to pay for them. The benefit amount is meaningful, the cost is modest, and the rider operates independently of the base critical illness coverage on you.
Return of premium rider
A return of premium rider refunds your premiums at the end of the term if you outlive the policy and never make a claim. On the surface this sounds like free coverage. It is not.
The rider adds a significant cost to the base premium. Most clients are better served by taking the right amount of base coverage at the lower premium and putting the difference into a registered or non-registered account they actually control. The math on return of premium rarely beats the math on a separate investment account, especially over 20 to 30 years.
That said, two situations where return of premium genuinely earns its place:
- Critical illness on children. ROP on a child critical illness policy is popular for a reason. Premiums are paid for years, and if no claim happens, the policy returns the premiums to the family. It functions almost as a forced savings vehicle attached to coverage. Common strategy.
- Corporate-owned shared ownership critical illness. ROP can be structured under a shared ownership critical illness arrangement where the corporation pays the cost of insurance and the shareholder pays the ROP rider personally. The corporation gets the CI protection. The shareholder personally receives the refunded premiums on surrender or expiry. Tax-efficient when structured correctly with proper legal and accounting support.
For most personal-use clients on a standard term policy, return of premium is something to walk past. For the two situations above, it is something to look at seriously.
Disability riders
Disability riders fall into two distinct types that often get confused. Premium-waiver riders waive the cost of your life insurance if you become disabled. Income-replacement riders pay you a monthly benefit if you become disabled. They sound similar. They do completely different things.
Disability waiver of premium
A disability waiver of premium rider waives your life insurance premium payments if you become disabled and cannot work. Your coverage stays in force, but you stop paying for it. The waiver applies to both the base policy and any other riders you have attached.
The catch is the carrier’s definition of disability. Some carriers waive premiums on an own-occupation definition. Others use any-occupation. The difference matters at claim time, and it is the part most clients never read in the contract.
Own occupation
Premium is waived if you cannot perform the duties of your occupation.
Easier to qualify. Better for the policyholder.
Any occupation
Premium is waived only if you cannot perform any occupation you are reasonably suited for by training or experience.
Much harder to qualify. Carrier-friendly.
Several major Canadian carriers, including Sun Life on the Total Disability Waiver Benefit, use a hybrid: own occupation for the first 24 months, then any occupation after that. The first two years are easier to claim. After that, the bar moves significantly higher. Canada Life uses an own-occupation definition for waiver benefits. Manulife and Empire Life waiver definitions vary by product line and contract; the actual definition language must be confirmed in the policy document, not the marketing brochure.
What this means in practice: the broader the definition (own occupation throughout, no time limit), the more useful the rider at the moment you actually need it. The narrower the definition (any occupation from day one), the more likely the carrier finds reasons not to pay.
What to check on your policy before signing: the exact wording of “total disability” on the rider, the waiting period (six months is standard), the rider’s expiry age (typically 60 or 65), and whether corporate-owned policies are eligible if your structure requires it.
Mortgage disability insurance
A mortgage disability rider covers all or part of your mortgage payments if you become disabled and cannot work. Functionally similar to creditor mortgage insurance from a bank, but tied to your life insurance policy and underwritten by the life carrier.
For most clients, a standalone individual disability insurance policy from a strong DI carrier is a better answer than the rider. The benefit amount, definition language, and portability are all stronger on a standalone policy. The mortgage-specific rider is narrower in scope and the benefit ends when the mortgage is paid off, which is often the wrong timeline. Compare options here: mortgage insurance quotes.
Disability income rider
A disability income rider pays you a monthly income if you become disabled and cannot work. Different from the waiver-of-premium rider above: this one pays cash to you, the waiver-of-premium one waives your life insurance cost.
Three structural elements set the policy: the monthly benefit amount, the waiting period (typically 30 or 90 days from when disability starts), and the benefit period (how long the monthly payments continue). Standalone disability insurance gives you more flexibility on all three of these than the rider version. Most clients with serious income-replacement need are better served by a separate individual disability policy, not a rider on a life policy.
Extreme disability benefit
An extreme disability benefit lets you advance up to 50% of the death benefit, capped at $250,000 across all benefits on the insured, if you suffer a permanent disability before age 60 that lasts at least six months. Permanent disability is typically defined as the inability to perform at least four of six activities of daily living without assistance: mobility, eating, dressing, toileting, continence, and bathing.
Beneva offers this benefit on Simplified Term Life 10, Simplified Term Life 20, Simplified Whole Life, Term Plus, and Permanent Life policies. The benefit is included at no extra cost on those products. It is not available on Beneva Guaranteed Issue Whole Life. Other Canadian carriers offer similar benefits under different names and structures; coverage details and triggers vary, so the actual policy contract is the source of truth.
Extreme disability benefits are useful when the diagnosis is severe and permanent. The funds advanced are deducted from the eventual death benefit, so what your beneficiaries ultimately receive is reduced by whatever is drawn during your lifetime.
Other coverage riders
The remaining rider category is the everything-else bucket: long-term care, hospitalization income, family income benefit, and fracture coverage. Smaller market share than the categories above, narrower use cases. A few earn their place in specific situations.
Long-term care
Lets you draw part of the death benefit to pay for care if you cannot perform at least 2 of 6 daily activities (bathing, dressing, eating, mobility, toileting, continence) without help.
Broker take
Useful as supplemental coverage. For serious LTC planning, a standalone long-term care policy gives more benefit and flexibility.
Hospitalization income
Pays a fixed daily amount for each day you are hospitalized, up to a maximum number of days. Coverage is narrow and payout amounts are modest.
Broker take
Skip for most clients with provincial health and group benefits. Worth a look only for self-employed without group coverage.
Family income benefit
Changes how your death benefit is paid: fixed monthly income to beneficiaries for a set period instead of a single lump sum.
Broker take
Total benefit paid out is usually less than the lump sum equivalent. A properly sized lump sum invested through a planner produces more value.
Fracture rider
Pays a lump sum if you break a bone in an accident. Payout amounts vary by location and severity of the fracture.
Broker take
Closer to entertainment coverage than meaningful protection for most clients. Math can occasionally support it for active families or physically demanding work.
Best life insurance riders for most Canadians
The best life insurance riders are the ones that match your situation, not the ones with the highest carrier markup. Most clients only need two or three riders to get meaningful additional protection. Loading up on every rider on the menu adds cost without adding proportional value.
Riders most clients should consider
- Disability waiver of premium. If you become disabled, the carrier waives your life insurance premium. Coverage stays in force without you paying for it.
- Critical illness rider or standalone critical illness policy. Especially if there is family history of heart conditions or stroke. Standalone is often cheaper than the rider; we cover that decision in the critical illness rider section.
- Child term rider. Small cost, meaningful conversion option that protects your child’s future insurability if their health changes.
- Guaranteed insurability, where insurability itself is at risk. Especially on permanent policies for children, or on disability policies where income is expected to rise significantly.
The riders to skip for most clients are accidental death and dismemberment, hospitalization income (when you have provincial health and group benefits), family income benefit, and fracture coverage. Each has narrow real-world payout situations relative to cost. Working with a licensed broker who can compare riders across every major Canadian carrier means you get the right combination, not whatever the first carrier you talked to happened to offer.
Should I get a life insurance rider?
You should get a life insurance rider only if it solves a specific problem your base policy does not, at a cost that makes sense for the protection it provides. Loading riders onto a policy because they are available is the wrong reason. Skipping them when they actually fit your situation is also wrong.
A useful way to think about it
Build the base policy first. Get the right amount of life insurance for what your family actually needs. Then layer riders only where each one earns its premium by covering a specific gap.
One scenario where the layering matters is when a client wants both life and critical illness coverage at meaningful amounts. The right move is usually to stage the applications, not bundle them in one shot. Apply for life coverage first. Several major Canadian carriers offer accelerated underwriting at this stage, with no medical required up to certain age bands and coverage amounts (including up to $2 million in qualifying cases). Get that approved and in force. Then apply for critical illness, which triggers the nurse visit and full medical underwriting. Sequencing the two applications protects coverage even if the second application gets rated or declined for a finding that would not have affected the life side.
The same logic applies to riders. Build the base coverage first. Then add only the riders that pull weight: your life insurance needs at different life stages shift over time, and the right rider mix shifts with them.
Are life insurance riders worth it?
Riders are worth it when they pay back more than they cost in expected real-world value, factoring in the actual probability of triggering them. Most riders are inexpensive on a monthly basis. The question is not whether the price is small. The question is whether the rider does anything meaningful when you actually need it.
Generally worth considering
Disability waiver of premium
Most clients with single-income or income-dependent households. Cheap protection against a real risk.
Generally worth considering
Child term rider
Almost any client with kids. Low cost, meaningful conversion option that protects insurability for life.
Situational
Critical illness rider
Family history of cancer, heart disease, or stroke. Often cheaper as a standalone policy at a different carrier than as a rider.
Situational
Guaranteed insurability
Specific cases: child permanent policies, disability policies with rising income, clients who locked in a strong rate they want to extend.
Usually skip
Accidental death
High-risk occupations or lifestyles only. Default position for most clients is to skip.
Usually skip
Hospitalization, family income, fracture
Narrow real-world payout. Most clients can skip without losing meaningful protection.
The right rider mix depends on health, family history, occupation, dependents, and what your base coverage already does. There is no universal answer. A licensed broker comparing riders across multiple carriers will find combinations a single carrier’s product menu cannot.
Adding or removing a life insurance rider
The best time to add a rider is at the original application, when the carrier is already underwriting you and the cost of attaching the rider is lowest. Adding riders later is possible on most policies but requires fresh medical underwriting and the cost may be higher than if it had been bundled at issue. Removing a rider is a simpler administrative request.
At application (best time)
Riders attach at the same medical underwriting as the base policy. No additional exams, no separate questionnaire, no rate-class re-evaluation. The cost is built into the premium structure from day one. Most riders are also priced lower at this stage than if added later.
After issue (possible, but with conditions)
Most riders can be added to an existing policy by submitting an application. The carrier requires fresh medical underwriting on the rider, including health questions and possibly a paramedical exam. If your health has changed since the original policy issued, the rider rate may be higher or the rider may be declined entirely.
Removing a rider
Notify the carrier in writing, complete the rider removal form, and the rider is dropped from the policy. The premium is recalculated and your monthly payment goes down by the rider cost. No medical underwriting required to remove. The base policy stays in force exactly as it was.
One-way doors
Some riders cannot be added after the policy is issued. Guaranteed insurability is the most common example: it must be elected at original underwriting and cannot be retroactively bolted on. If a rider is built into the base policy structure (like accelerated death benefit on most policies), it is not separately addable or removable.
If you are reviewing an in-force policy and wondering whether to adjust the rider mix, the cleanest path is a fresh review with a licensed broker who can compare what you have against what the current market offers. Talk to a broker directly before initiating any rider change, especially if you are considering adding coverage that requires fresh underwriting.
Frequently asked questions about life insurance riders
Q1
Are life insurance riders worth it?
Some are, some are not. Disability waiver, child term, and critical illness riders earn their place for most clients. Accidental death and dismemberment, hospitalization income, and fracture coverage usually do not. Worth depends on your family situation, your existing base coverage, and the actual probability of triggering each rider.
Q2
What are the most common life insurance riders in Canada?
The most common riders sold in Canada are disability waiver of premium, accelerated death benefit, critical illness, child term, guaranteed insurability, and accidental death and dismemberment. Long-term care riders are growing in usage as the population ages.
Q3
Why would you not want riders on a life insurance policy?
Riders that do not match your situation add cost without adding meaningful protection. Accidental death and dismemberment, family income benefit, hospitalization income, and fracture riders are common examples. The premium is small per rider, but stacking several of them adds real cost over the life of the policy. The right answer is to skip riders that do not pull weight, not to load every rider on the menu.
Q4
Can I add riders to an existing life insurance policy?
Most riders can be added to an existing policy, but the carrier will require fresh medical underwriting on the rider. Health questions, possibly a paramedical exam, and a re-evaluation of rate class. If your health has changed since the policy issued, the rider rate may be higher than if it had been added at original application. Some riders, like guaranteed insurability, cannot be added after issue and must be elected at original underwriting.
Q5
Can I remove riders from my life insurance policy?
Yes. Notify the carrier in writing, complete the rider removal form, and the rider is dropped. No medical underwriting required to remove. Your monthly premium goes down by the rider cost. The base policy stays in force unchanged. Removing a rider is administratively simpler than adding one.
Q6
Can I add multiple riders to my life insurance policy?
Yes. Most major Canadian carriers allow several riders to be combined on the same policy, subject to product compatibility and underwriting. The cost stacks: each rider adds its own premium component. The right approach is to add only the riders that solve a specific need, not to add every available rider because it is offered.
Q7
Are the benefits from life insurance riders taxable?
Many personally owned rider benefits are received tax-free in Canada, though tax treatment depends on policy ownership structure and benefit type. Critical illness lump-sum benefits, accidental death payouts, accelerated death benefit advances, and disability waiver of premium are typically not treated as taxable income. Tax treatment can vary based on policy ownership structure (personal vs corporate) and how the benefit is used. Confirm with a tax advisor or the Canada Revenue Agency for situations involving corporate-owned policies, shared-ownership critical illness, or estate planning.





