·

Costco Life Insurance Review: Is It Worth It for Canadians?
By Parvesh Benning, Licensed Life Insurance Broker
Costco’s Manulife term plan looks like a discount, but it is actually a stripped-down product, and the missing features can cost you.
Updated: April 29, 2026
Costco Life Insurance Review: Is It Worth It for Canadians?
By Parvesh Benning, Licensed Life Insurance Broker
Costco’s Manulife term plan looks like a discount, but it is actually a stripped-down product, and the missing features can cost you.
Updated: April 29, 2026
Costco markets its life insurance as a members-only deal from one of Canada’s largest insurers. The product has improved, but what the marketing does not show you is what has been stripped away. This review compares the actual Manulife policy contracts side by side so you can see what you are paying for, and what you are giving up.
This guide walks through the actual policy documents and compares what you get through Costco against what the same insurer offers through a licensed broker.
Is Costco life insurance worth it?
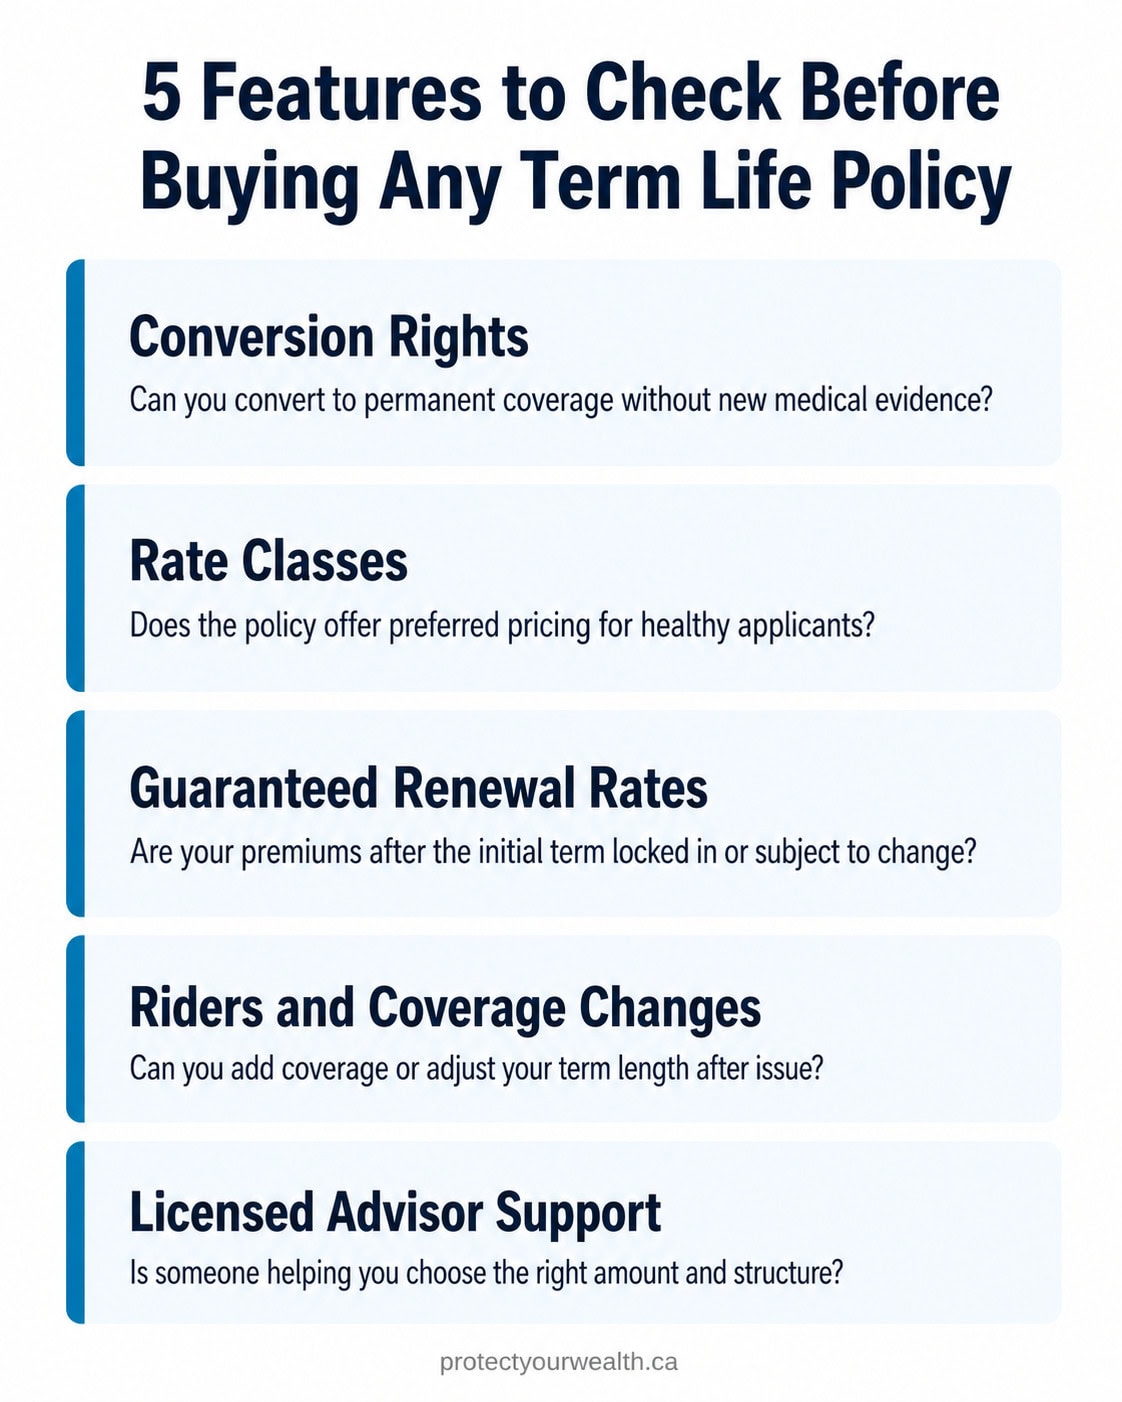
Having coverage and having the right plan are not the same thing. Costco’s term life insurance is real coverage underwritten by Manulife, and the price can work for healthy applicants on a basic 20-year term. But the contract is missing features that every individual Manulife policy includes by default.
What you get
- Term life insurance underwritten by Manulife
- 20-year terms, coverage up to $2 million
- Competitive pricing for standard healthy applicants
What’s stripped away
- No conversion to permanent life insurance
- No preferred rate classes
- No Vitality premium savings
- No riders or coverage option changes
- No licensed advisor support
- Renewal rates after the initial term are not guaranteed
Premium is not everything. The comparison below breaks down the actual Manulife contract documents so you can see what the price is leaving out.
Inside This Review
- What Costco Life Insurance Actually Offers (Updated)
- Costco Life Insurance Pros and Cons
- How Costco Compares to Buying Manulife Direct Through a Broker
- Costco Term Life Insurance Policy Details
- Why Costco Life Insurance May Not Be Your Best Option
- Costco Life Insurance Customer Reviews
- Frequently Asked Questions
What Costco Life Insurance Actually Offers (Updated)
Costco’s life insurance is a term policy underwritten by Manulife through its Affinity Markets division. It is presented as a discounted plan for members, but what you are actually getting is a stripped-down product. You must be a current Costco member or eligible spouse to apply.
Coverage
$50K to $2M
Increments
$25,000
Issue Ages
18 to 70
Terms Available
5, 10, or 20 years
What has been stripped away matters more than what is included. The contract allows exactly two changes after issue: decrease your coverage or change your smoking status. No conversion to permanent insurance. No term length changes. No preferred rate classes (Manulife’s direct products offer five through their Vitality program, the Costco contract does not reference them). No riders. Premiums are guaranteed for the initial term. What is not guaranteed is the renewal rate after that term ends.
Manulife is one of Canada’s largest life insurance companies. The Costco product uses their name and their underwriting, but it is not the same product the company sells through licensed advisors. Same insurer, fundamentally different contract.
Costco Life Insurance Pros and Cons
Some coverage is better than no coverage. I mean that. If someone knows the limitations and still wants a basic plan, I am happy they are protected. But premium is not everything, and this is a stripped-down product that could have significant impacts down the road.
Pros
- It is real term life insurance underwritten by Manulife, not some unknown carrier. That matters.
- The 20-year term is now available with coverage up to $2,000,000. That is a real improvement over earlier versions.
- For someone with a significant health history, a group-style product with simplified underwriting might actually be the better path because the underwriting requirements can be more lenient.
Cons
- No conversion to permanent insurance. Your health changes, your term is ending, and you have zero options to convert. You reapply from scratch or you lose coverage.
- No preferred rate classes. Manulife’s direct Family Term product has five Healthstyle categories. This contract does not mention them.
- The contract allows two changes after issue. Two. Decrease your coverage or change your smoking status. That is it.
- Renewal rates after the initial term are not guaranteed. Your premiums are locked in during the initial term, but the renewal rate is based on your attained age and Manulife’s rates in effect when your term is up.
- No advisor. No one to help you choose the right coverage amount, set up beneficiaries properly, or review your policy when your life changes.
Think about mortgages for a second. You can get a no frills, rock-bottom rate, but it may come with no prepayment flexibility, no portability, huge penalties. Sometimes you really do get what you pay for, and in this case it could be very costly.
How Costco Compares to Buying Manulife Direct Through a Broker
When you only focus on one product from one company, you get a very biased view of what is available. The Costco term plan and the Manulife Family Term with Vitality Plus are both underwritten by the same insurer. I have read both contracts side by side. These are not the same product.
| Feature | Costco Manulife T20 | Direct Manulife Family Term |
|---|---|---|
| Term options | 5, 10, or 20 years | T10, T20, T65, Term-Life |
| Max coverage | $2,000,000 | No published cap |
| Conversion to permanent | Not available | Full conversion, no medical evidence |
| Option changes | Decrease amount or smoking status only | T10→T20, T10/T20→T65, any→Term-Life without evidence |
| Rate classes | Not referenced in contract | 5 Healthstyle categories (HS1 through HS5) |
| Vitality savings | Not available | Up to 15% (Platinum status) |
| Riders | Not available | Available |
| Future renewal rate guaranteed? | No | Yes, per premium tables in contract |
| Advisor support | Self-service only | Licensed advisor included |
Every one of the nearly 20 companies I work with includes a conversion clause in their individual term products. Conversion is standard. The Costco contract is the exception. Section 4 lists two things you can change after issue, and that is it. No conversion section exists in this contract.
Imagine you had a major health event and had no opportunity to convert your term plan to permanent coverage. That is a massive difference. With a direct Manulife Family Term policy, you can convert all or part of your coverage to permanent before your conversion expiry date. No new medical evidence. You can even convert half and have the remaining half go into a new term at standard rates. None of that exists in the Costco contract.
If you want to see how a direct policy compares on price for your specific situation, compare term life insurance quotes across carriers with no cost and no obligation.
Costco Term Life Insurance Policy Details
The Costco Manulife term plan is a non-participating policy with no cash value. Premiums are guaranteed for the initial 20-year term, payable monthly by pre-authorized debit or credit card, with a 30-day grace period. A living benefit is included for terminal illness:
50%
of coverage accessible
$200K
maximum payout
2 yrs
minimum in force
< 85
age requirement
The payout goes directly to you and reduces your death benefit by the same amount. One detail most people miss: if you change your smoking status during the policy, the contestability period restarts from that date. And if you are paying monthly on any term policy, ask about annual payment. It saves 8 to 9 percent. That adds up.
Why Costco Life Insurance May Not Be Your Best Option
The frustrating part of this job is seeing someone realize the product they have is not what they thought they signed up for. It happens more than it should.
The question you should be asking is not “do I have life insurance?”
The question is: if I died tomorrow, would this fully protect the people depending on me, and what happens to that coverage later?
When it is just one company presenting their product, they have a bias and a responsibility to advertise it as the best option available. The Costco Manulife plan is designed to look like a discount when it is actually stripped away. And the $2 million cap sounds high until you calculate what it actually takes to replace a household income, cover a mortgage, and fund your children’s education.
The better approach: does this offer the best value, best conversion, best features, best underwriting? When you compare across the board with no bias, there are many situations where a different product gives a much better outcome. I am not going to say the Costco plan is never the right call. But you cannot evaluate that from inside one channel.
Costco Life Insurance Customer Reviews
Public reviews of the Costco Manulife term plan are limited, but the feedback that exists follows a consistent pattern. The issues customers report are often the same ones people only notice after buying.
What customers tend to like
Many people like the simple application process, the competitive initial pricing for healthy applicants, and the trust that comes with the Costco and Manulife names.
Where complaints tend to focus
Common concerns include renewal pricing surprises, health-related declines from applicants who thought simplified underwriting meant guaranteed approval, and missing conversion options that may only become obvious after someone’s health changes.
These are the same gaps described throughout this review. The difference is that customers often discover them after the fact, when the policy is already in place and the fine print matters more than the initial price.
Frequently Asked Questions
Is Costco life insurance available in Canada?
Yes. Costco’s life insurance is available to Canadian members through a term policy underwritten by Manulife’s Affinity Markets division. You apply through a designated brokerage channel, not through Costco stores or Manulife directly.
Do I need a Costco membership to apply?
Yes. You must be a current Costco member or an eligible spouse (legally married or in a conjugal relationship of two or more continuous years).
What is the maximum coverage amount?
The 20-year term offers coverage from $50,000 to $2,000,000 in $25,000 increments. Issue ages are 18 to 70.
Can I convert the Costco policy to permanent life insurance?
No. The Costco contract does not include a conversion clause. Section 4 of the policy allows only two changes: decrease your coverage amount or update your smoking status. If you need permanent coverage later, you would have to apply separately and re-qualify based on your health at that time.
What happens when my term expires?
The policy renews automatically every 20 years until the policy anniversary nearest your 90th birthday. Your premiums are guaranteed during the initial term, but the renewal rate after that term is not guaranteed. It is based on your attained age and Manulife’s rates in effect at renewal.
Is this the same as buying Manulife insurance directly?
No. The Costco product is a stripped-down version of what Manulife offers through licensed advisors. The direct Manulife Family Term with Vitality Plus includes conversion rights, five rate classes, coverage option changes, Vitality premium savings, and rider availability. Same insurer, different contract.
I am not a broker for Manulife. I am not a broker for Costco.
I am a broker for you.
You have seen what the Costco contract is missing. Let me show you what the same premium can look like when you compare across multiple Canadian insurers through a licensed broker.
No cost. No obligation. Independent life insurance and segregated fund solutions.
Proudly based in Hamilton. Serving clients across Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, Nova Scotia, and New Brunswick.