 ·

10 Biggest Life Insurance Companies in Canada (2026)
By Parvesh Benning, Licensed Life Insurance Broker
Bigger does not automatically mean better for your policy, and the gap between the two is where an independent broker earns their value.
This guide ranks Canada’s ten largest life insurers by total assets, with their financial strength ratings and most recent reported figures, then explains what those numbers actually mean when you decide where to apply.
Updated: June 19, 2026
10 Biggest Life Insurance Companies in Canada (2026)
By Parvesh Benning, Licensed Life Insurance Broker, Updated: June 19, 2026
Bigger does not automatically mean better for your policy, and the gap between the two is where an independent broker earns their value.
This guide ranks Canada’s ten largest life insurers by total assets, with their financial strength ratings and most recent reported figures, then explains what those numbers actually mean when you decide where to apply.
Roughly 70 companies sell life insurance in Canada, yet a handful of them hold most of the coverage in force.
This ranking sorts the ten largest by total assets, then adds what the big comparison sites leave out: a working broker’s read on when a company’s size genuinely matters to you, and when it is beside the point.
The short answer
Manulife is the largest life insurance company in Canada by the size of its insurance business. Manulife, Sun Life, and Canada Life are widely known as the Big 3, and together with Desjardins and iA Financial they form the top tier of the market.
Every carrier in the top ten is financially strong and federally supervised. Size mostly tells you about scale and product range. It does not tell you which company will price your specific health and situation best.
Sun Life
Canada Life
Desjardins
iA Financial
On This Page
The 10 Biggest Life Insurance Companies in Canada
The ten biggest life insurance companies in Canada, ranked by the size of their life insurance business, are Manulife, Sun Life, Canada Life, iA Financial, Beneva, Desjardins, RBC Insurance, Empire Life, BMO Insurance, and Co-operators.
I rank them by the size of their insurance business on purpose, not by total balance-sheet assets. Several of these companies sit inside much larger banking or holding groups, so a raw asset count tells you how big the parent is, not how much life insurance the company actually writes. Coverage on the books is the cleaner measure of who is genuinely a large life insurer in Canada.
Toronto, ON · AM Best A+ (Superior). The largest Canadian life insurer and the most global of the group.
Toronto, ON · AM Best A+ (Superior). Deep lineup across term, permanent, and health coverage.
Winnipeg, MB · AM Best A+ (Superior). Part of Great-West Lifeco, with broad group and individual reach.
Quebec City, QC · AM Best A+ (Superior). Formerly Industrial Alliance, strong on simplified and traditional issue.
Quebec City, QC · AM Best A (Excellent). The largest mutual insurer in Canada, formed from SSQ and La Capitale.
Levis, QC · Not rated by AM Best. Cooperative ownership, rated by other agencies, not a sign of weakness.
Mississauga, ON · AM Best A (Excellent). Bank-owned, with a strong disability and term presence.
Kingston, ON · AM Best A (Excellent). Independent Canadian insurer known for competitive term pricing.
Toronto, ON · AM Best A (Excellent). Bank-owned, with a focus on term and permanent solutions.
Guelph, ON · AM Best A (Excellent). Cooperative insurer with a wide multi-line footprint.
Ranked by size of life insurance business from each company’s most recent annual report. AM Best is an independent agency that grades insurers on financial strength, where A+ is “Superior” and A is “Excellent”; ratings are current as of the latest review and can change. Ivari sits just outside the top ten by coverage volume but remains a sizable national carrier.
One number worth knowing: the LICAT ratio
LICAT (the Life Insurance Capital Adequacy Test) is the federal safety-margin check every life insurer must pass. In plain terms, it measures how much capital a company holds against the risks on its books. The regulator’s floor is 90% and its target is 100%, so anything comfortably above that signals a healthy cushion to pay claims. The three largest carriers closed 2025 at 136% (Manulife), 140% (Sun Life), and 128% (Canada Life), all well clear of the minimum.
Here is the part a ranking cannot show you. For the exact same coverage, these carriers price the same person very differently, and the cheapest name is rarely the same twice. Comparing several at once is what keeps you from overpaying, and as an independent brokerage that is exactly what we do across more than 20 insurers at no cost to you. You can compare life insurance quotes to see where your situation actually lands.
The Canadian Life Insurance Industry by the Numbers
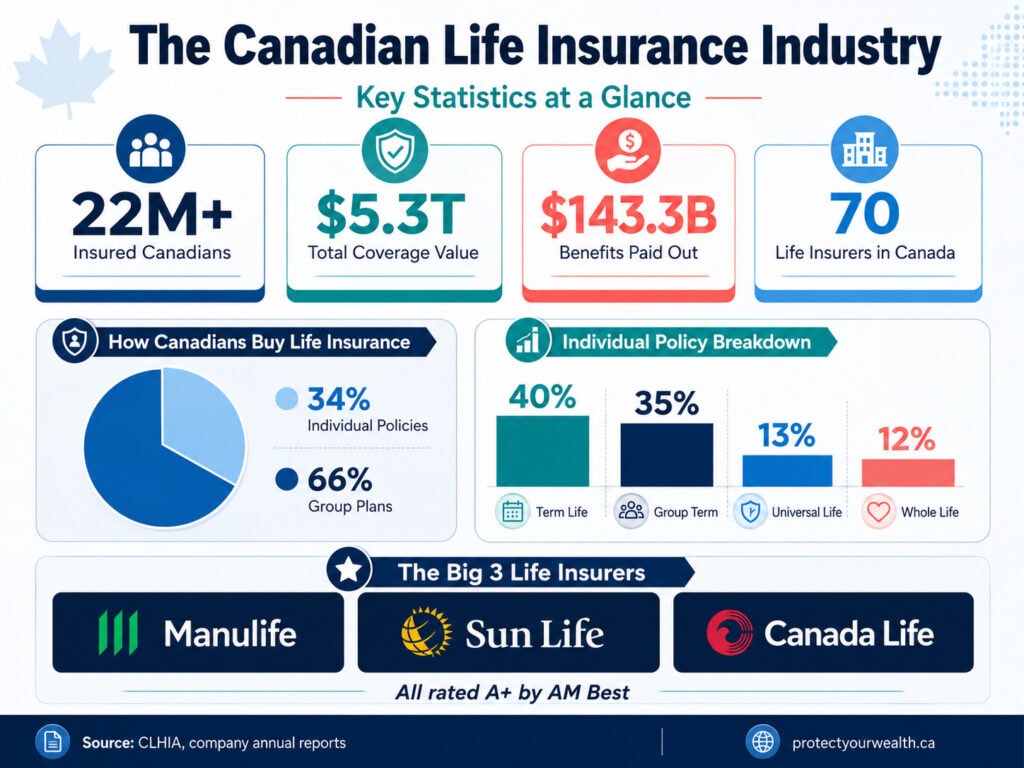
Canada’s life insurance industry is large, stable, and tightly regulated, which is the backdrop to every name on this list. In 2024, Canadian life and health insurers paid out a record $143.3 billion in benefits and retirement payments. Here is where that money went.
$143.3B
Total benefits and retirement payments in 2024
$71.4B
Paid from annuities and retirement income
$16.6B
Spent on prescription drug coverage
~$10B
Paid in disability benefits
Roughly 70 companies write life insurance in Canada, and about two-thirds of all coverage is held through workplace group plans, with individually owned policies making up the rest. On the individual side, term life is the most common choice, ahead of universal and whole life on the permanent side.
The safety net behind every Canadian policy
Every insurer on this list is federally regulated and supervised by OSFI, and each holds capital well above the LICAT minimum described above.
There is also a backstop most people never hear about. Assuris, the industry-funded protection body, guarantees you would keep up to $1,000,000 or 90% of a life insurance death benefit, whichever is higher, if a member insurer ever failed. That has happened only three times in Canadian history.
So in this market, size mostly buys you stability and a broad product shelf. It does not decide which carrier will treat your age, health, or budget most favourably, and that is where a ranking stops being useful and a real comparison begins.
What Is the Largest Life Insurance Company in Canada?
Manulife is the largest life insurance company in Canada by the size of its insurance business, ahead of Sun Life and Canada Life. The three of them together write most of the individual life insurance sold in this country.
Largest by insurance business
Manulife Financial
Operates across Canada, the United States, and Asia under the Manulife and John Hancock brands, with the widest product shelf of any Canadian carrier.
Here is the part most rankings skip. All three are about as financially secure as a company can be, so for nearly everyone the useful question is not which carrier is biggest. It is which one prices and underwrites your age, health, and budget most favourably.
Manulife is also the carrier behind Manulife Vitality, which ties your premiums to healthy-living activity. It is a clean example of biggest not meaning best fit: Vitality rewards some clients and adds friction for others who would rather keep things simple.
Who Are the Big 3 Life Insurance Companies in Canada?
The Big 3 are Manulife, Sun Life, and Canada Life. They are the three largest life insurers in the country and the three names most Canadians recognize, which is exactly why it helps to understand them before assuming one is your answer.
Manulife
Largest by insurance business, with the widest product shelf and the Vitality healthy-living program. Strong on permanent and complex cases.
Sun Life
Carries the highest LICAT capital ratio of the three at the operating-company level, with a deep lineup across term, permanent, and health.
Canada Life
Part of Great-West Lifeco, formed by merging Great-West Life, London Life, and Canada Life. Broad group and individual presence.
Being one of the Big 3 makes a carrier safe and well-stocked. It does not make it the cheapest or the most flexible for your age, health, or coverage type, which is the whole reason I compare across the wider market instead of steering everyone toward the same three names. For a fuller look at how the field stacks up, see our guide to the best life insurance companies in Canada.
Does the Biggest Insurer Mean the Best Policy for You?
No. The biggest insurer is rarely the deciding factor in which policy is right for you, and after years of placing coverage across these carriers, the gap between “largest” and “best fit” is the thing I spend most of my time on.
Here is what actually happens behind the scenes. Every carrier on this list runs its own underwriting rules, its own pricing on each age band, and its own appetite for specific health conditions. A 45-year-old with controlled high blood pressure can be standard at one of these insurers and rated up 50% at another, for the exact same coverage. Size has nothing to do with that. The underwriting manual does.
So when I assess a file, financial strength is a floor, not a tiebreaker. Once a carrier clears the bar of being well-capitalized and OSFI-regulated, which all ten of these do, its size stops mattering. What matters next is who prices your age and health best, who underwrites your specific situation most favourably, and whose product structure fits what you are actually trying to do.
Where the biggest name can cost you
I have seen plenty of buyers default to the most recognizable carrier and pay more than they needed to, or get rated on a condition a different insurer would have taken at standard rates. Brand recognition is not a discount. It is just brand recognition.
This is the entire reason an independent broker exists. I am not tied to any one of these companies, so I can run your file against several of them and let the actual offers decide, instead of starting with a logo and working backward. The biggest insurer might still win for you. The point is that it has to earn it.
Frequently Asked Questions
Question 01
Which is the largest life insurance company in Canada?
Manulife is the largest, measured by the size of its insurance business, ahead of Sun Life and Canada Life. These three are known as the Big 3 and together write most of the individual life insurance sold in Canada.
Question 02
Is a bigger insurance company safer than a smaller one?
Not in any way that affects your claim. Every federally licensed life insurer in Canada is supervised by OSFI and must hold capital above the LICAT minimum, and Assuris protects policyholders up to $1,000,000 or 90% of a life insurance death benefit, whichever is higher, if an insurer ever failed. Past a certain point, size buys stability and a wider product shelf, not a better outcome on your policy.
Question 03
What does the LICAT ratio actually tell you?
LICAT (the Life Insurance Capital Adequacy Test) measures how much capital an insurer holds against the risks it carries. The regulatory minimum is 100%, and Canada’s largest insurers sit well above that, generally in the 128% to 157% range as of December 31, 2025. A higher number signals a stronger capital cushion, but all of the carriers on this list clear the bar comfortably.
Question 04
Should I just buy from the biggest insurer?
Not automatically. The biggest carrier is not always the cheapest or the most willing to insure your specific age, health, or situation. The same applicant can be standard at one insurer and rated higher at another, which is why comparing several carriers usually matters more than picking the largest name. An independent broker can run your file across multiple companies and let the actual offers decide.
Find the Right Life Insurance Company for Your Situation
The biggest name is a starting point, not your answer.
Canada’s ten largest life insurers each bring different strengths. Financial strength and size matter, but so does how a carrier prices your specific health profile and which products they actually offer. The right fit depends on your situation, not the ranking. As an independent broker, I compare these carriers against each other and let the real offers decide.
We are proudly based in Hamilton and work with clients across Ontario, Alberta, British Columbia, Manitoba, Saskatchewan, New Brunswick, and Nova Scotia, including areas such as Waterloo, Maple Ridge, Grande Prairie, and Winnipeg. We offer life insurance and segregated fund solutions.





