·
Tax-Free Savings Account (TFSA) in Canada: The Complete Guide
By Parvesh Benning, Licensed Life Insurance Broker
Most Canadians leave their TFSA in a basic savings account or GIC, not realizing what they’re giving up in tax-free growth.
The Tax-Free Savings Account is the single most flexible registered account the Canadian government has ever created, and most people are using about 10% of what it can do. Whether you’re sitting on $109,000 in unused contribution room or just opened your first TFSA last year, the choices you make about account type, investment vehicle, and how your TFSA coordinates with your RRSP, FHSA, and RESP determine whether this account quietly compounds wealth or just collects dust.
Updated: April 2026
The Tax-Free Savings Account is the single most flexible registered account the Canadian government has ever created, and most people are using about 10% of what it can do. Whether you’re sitting on $109,000 in unused contribution room or just opened your first TFSA last year, the choices you make about account type, investment vehicle, and how your TFSA coordinates with your RRSP, FHSA, and RESP determine whether this account quietly compounds wealth or just collects dust.
This guide covers contribution limits and account types, withdrawal and recontribution rules, what happens to your TFSA when you die, and why most Canadians are better off with a segregated fund inside their TFSA than a GIC. Written by a licensed broker who works with these accounts daily across seven provinces.
TFSA Growth & Tax Savings Calculator
Track your contribution room, project tax-free growth, see exactly how much tax you save vs a non-registered account, and compare TFSA vs RRSP side by side.
Using Tax Year 2026 Brackets
Last updated: April 2026. Tax data verified against CRA T4127 and TaxTips.ca. TFSA limits per CRA annual announcements.
Enter at least a current balance or a planned contribution, plus your annual income. Other fields are optional.
Enter 0 if starting fresh.
$583/mo is approximately the 2026 annual limit ($7,000 / 12).
Needed for tax savings and TFSA vs RRSP comparison.
What this guide covers
- What Is a TFSA and Who Can Open One
- Types of TFSA Accounts
- TFSA Contribution Limits and Room
- Benefits and Advantages of a TFSA
- Disadvantages and Limitations
- Can You Lose Money in a TFSA
- How TFSAs Work: Deposits, Withdrawals, and Recontribution
- TFSA GICs and Guaranteed Investments
- TFSA vs RRSP, FHSA, and Other Registered Accounts
- Can You Have Multiple TFSAs or a Joint TFSA
- What Happens to Your TFSA When You Die
- Where a TFSA Fits in Your Overall Financial Plan
- Frequently Asked Questions
What Is a TFSA and Who Can Open One
A TFSA is a registered account created by the Canadian government in 2009 that lets you save and invest without paying tax on the growth, the income, or the withdrawals. Unlike an RRSP, contributions are not tax-deductible. But everything inside the account grows and comes out completely tax-free.
You can hold different types of investments inside a TFSA: high-interest savings deposits, GICs, mutual funds, segregated funds, stocks, bonds, and ETFs. The account itself is just the registered shell. What you put inside it determines whether your money sits flat or actually works for you.
To open a TFSA you need three things: you must be 18 years of age or older, have a valid Social Insurance Number, and be a Canadian tax resident. You can open one at a bank, credit union, insurance company, or through a licensed broker.
For new immigrants to Canada
Contribution room is set when you become a tax resident in Canada, not when you become a permanent resident. It is not backdated to 2009. Your room accumulates from the year you became a tax resident, and only from that year forward. If you arrived and became a tax resident in 2019, your cumulative room starts at the 2019 annual limit and builds each year from there.
Types of TFSA Accounts
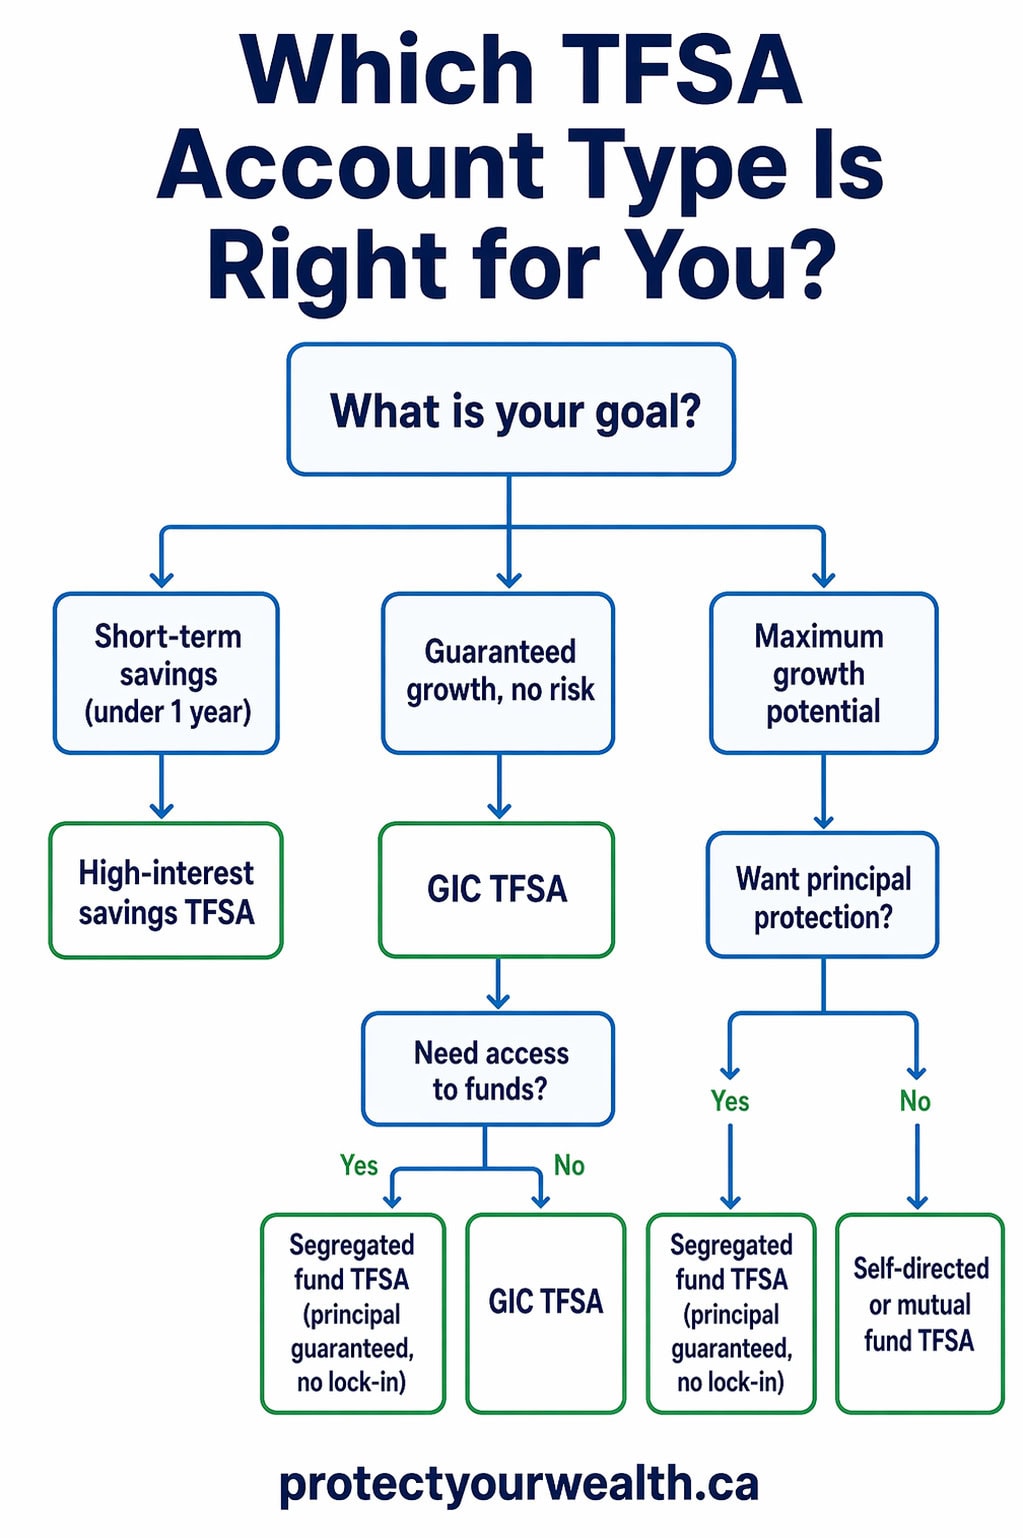
Not all TFSAs are the same. The “account” is just a registered shell, and what you hold inside it changes everything about how your money grows, what protections you have, and how much flexibility you get. Most Canadians default to whatever their bank offers, which is usually a savings deposit or GIC. But there are five distinct types.
Savings Deposit / High-Interest TFSA
The simplest version. Your money earns a variable interest rate with no market risk. Good for emergency funds or short-term savings you may need within a year. Growth is minimal but your principal is always safe.
GIC TFSA
You lock your money in for a set term (usually 1 to 5 years) at a guaranteed rate. Higher rates than a savings deposit, but your funds are not accessible until maturity. Protected by CDIC deposit insurance up to $100,000 per institution.
Mutual Fund TFSA
Your TFSA holds professionally managed mutual funds. More growth potential than GICs, but your account value fluctuates with the market. No principal guarantee unless you choose a money market fund.
Self-Directed / Brokerage TFSA
You manage everything yourself: individual stocks, bonds, ETFs. Full control and typically lower fees, but no guidance and no guarantees. This is the version fintech platforms and discount brokerages promote.
Segregated Fund TFSA
Offered through insurance companies, not banks. Segregated funds can provide 75% to 100% principal guarantees at maturity and death, plus the ability to name a beneficiary and bypass probate. More growth potential than a GIC with downside protection built in. Learn more about how segregated funds work.
Which type is right depends on your time horizon, whether you need access to the funds, and how much risk you’re comfortable with. Most people only hear about the first two because that’s what banks sell. The last three require either a brokerage account or a licensed broker to set up.
TFSA Contribution Limits and Room
Every Canadian who was 18 or older in 2009 and has never contributed has $109,000 in available TFSA contribution room right now. That number grows by $7,000 each year. If you turned 18 after 2009, your room starts accumulating from the year you turned 18.
The government sets a new annual limit each year, indexed to inflation and rounded to the nearest $500. It does not always go up. The limit sat at $5,000 for the first four years, jumped to $10,000 in 2015 under the Harper government, then dropped back to $5,500 the following year. It has been $7,000 since 2024.
Annual and cumulative TFSA contribution limits since 2009
| Year | Annual Limit | Cumulative Total |
|---|---|---|
| 2009 | $5,000 | $5,000 |
| 2010 | $5,000 | $10,000 |
| 2011 | $5,000 | $15,000 |
| 2012 | $5,000 | $20,000 |
| 2013 | $5,500 | $25,500 |
| 2014 | $5,500 | $31,000 |
| 2015 | $10,000 | $41,000 |
| 2016 | $5,500 | $46,500 |
| 2017 | $5,500 | $52,000 |
| 2018 | $5,500 | $57,500 |
| 2019 | $6,000 | $63,500 |
| 2020 | $6,000 | $69,500 |
| 2021 | $6,000 | $75,500 |
| 2022 | $6,000 | $81,500 |
| 2023 | $6,500 | $88,000 |
| 2024 | $7,000 | $95,000 |
| 2025 | $7,000 | $102,000 |
| 2026 | $7,000 | $109,000 |
Source: CRA TFSA contribution rules. Annual limits are indexed to inflation and rounded to the nearest $500.
Unused room carries forward indefinitely. If you contributed $3,000 in a year with a $7,000 limit, the remaining $4,000 rolls into the following year on top of that year’s new room. There is no deadline to use it and no penalty for leaving room unused.
One thing to watch: your contribution room is tracked by the CRA based on your tax returns and TFSA issuer reports. If you are unsure of your available room, log in to your CRA My Account before making a large deposit. Over-contributing triggers a 1% per month penalty on the excess amount, and the CRA does enforce it.
Benefits and Advantages of a TFSA
The biggest advantage of a TFSA is that every dollar of growth inside the account is permanently tax-free. Interest, dividends, capital gains, fund distributions: none of it is taxed while it sits in the account and none of it is taxed when you take it out. There is no other registered account in Canada that offers tax-free going in, growing, and coming out.
Compare that to a non-registered account where you are paying tax on interest income every single year, even if you never touch the money. Or an RRSP, where the growth is tax-deferred but every withdrawal gets added to your taxable income. A TFSA has neither of those drawbacks.
Beyond the core tax shelter, there are five specific advantages most guides skip over:
No impact on government benefits
TFSA withdrawals do not count as income for Old Age Security, the Guaranteed Income Supplement, or the Canada Child Benefit. RRSP and RRIF withdrawals do. For anyone planning for retirement, this is a major distinction. Pull $20,000 from your RRIF and it pushes you closer to the OAS clawback threshold. Pull $20,000 from your TFSA and the government does not even see it.
No age restrictions on holding the account
An RRSP must be converted to a RRIF by December 31 of the year you turn 71, forcing minimum annual withdrawals whether you need the money or not. A TFSA has no conversion deadline and no forced withdrawals. You can hold it and contribute to it for the rest of your life.
Full liquidity without penalty
You can withdraw any amount at any time with no tax hit, no withholding, and no waiting period. The only thing you need to track is your contribution room, which resets the following January 1.
Unused room carries forward forever
If you skip a year or contribute less than the annual limit, that room does not disappear. It accumulates indefinitely. Someone who has never opened a TFSA and was 18 or older in 2009 has $109,000 in available room right now.
Creditor protection (with the right structure)
A TFSA held at a bank has no creditor protection. But a TFSA held inside a segregated fund contract with a named beneficiary can be protected from creditors in most provinces, the same way life insurance proceeds are protected. This matters for business owners and professionals with liability exposure.
Disadvantages and Limitations
The main disadvantage of a TFSA is that contributions are not tax-deductible. Unlike an RRSP, putting money into a TFSA does not reduce your taxable income for the year. If you are in a high tax bracket and need the deduction, the RRSP gives you an immediate tax break that the TFSA cannot match.
There are three specific limitations worth knowing before you contribute:
$7,000
Annual room cap
Modest compared to RRSP space. It takes over 15 years of maxing out to accumulate what a single high-income year generates in RRSP room. For high earners, the TFSA alone is not enough to build a full retirement portfolio.
1%/month
Over-contribution penalty
The CRA charges this on any amount over your limit, with no warning. If you withdraw $10,000 mid-year and redeposit it before January 1, that redeposit counts as a new contribution. This catches people every year.
1%/month
Non-resident contribution tax
If you leave Canada and stop being a tax resident, any contributions made while non-resident are penalized. You can keep the account open and let it grow, but you cannot add to it.
None of these are reasons to avoid the TFSA. They are reasons to understand the rules before you start contributing.
Can You Lose Money in a TFSA
It depends on the type of investment and the time horizon. If you have a principal guaranteed product, then there is no opportunity to lose money. But if you’re in an exposed type of account, the account may fluctuate with actual market values if there’s no principal protection guarantee.
The TFSA itself does not create risk. What you hold inside it does. Here is how the five account types compare on principal safety:
Principal fully protected. Variable rate, no lock-in.
Principal guaranteed. Locked for term. CDIC insured up to $100,000.
75% to 100% principal guarantee at maturity and death. Market upside with downside floor.
No principal guarantee. Value fluctuates with markets. Long-term horizon reduces risk.
No guarantee. Individual stocks can lose significant value. Highest risk, highest potential return.
It is possible to protect your principal in the right investment vehicle: a seg fund, a market-tied GIC, or a high-interest savings account. Those are all protected. The people who lose money in a TFSA are typically in self-directed accounts holding volatile positions, or they have accidentally over-contributed and are paying the 1% monthly penalty without realizing it.
If protecting your principal matters to you, the account type you choose is the decision that matters most. Not whether to open a TFSA at all.
How TFSAs Work: Deposits, Withdrawals, and Recontribution
You can deposit and withdraw from a TFSA at any time with no tax consequences and no penalties, as long as you stay within your contribution room. No withholding tax, no waiting periods, no approval process. The money is yours.
Where people get tripped up is the recontribution timing. When you withdraw from the TFSA, that room doesn’t come back until January 1 the following year. Not the next day. Not the next month. January 1.
Here is how the cycle actually works:
You contribute during the year
Each dollar deposited reduces your available contribution room for that calendar year. You can contribute in lump sums or spread it out.
You withdraw whenever you need to
No tax. No withholding. No questions. Withdraw $500 or $50,000, the process is the same.
Wait. Do not recontribute in the same year.
The withdrawn amount is added back to your contribution room on January 1 of the following year, not immediately. Putting it back before then counts as a new contribution and can push you over your limit.
January 1: room resets
Your new room equals: last year’s unused room + amounts withdrawn last year + the new annual limit. Now you can safely recontribute.
I have seen situations where a client didn’t realize they over-contributed and got penalized. It is almost always this recontribution timing issue. They withdraw mid-year, put the money back a few weeks later thinking it is fine, and then get a letter from the CRA months later with a 1% per month penalty on the excess.
The simple rule: if you withdraw and want to put it back, wait until the new year. If you are not sure about your room, check CRA My Account before depositing anything.
TFSA GICs and Guaranteed Investments
A GIC inside a TFSA guarantees your principal and locks in a fixed rate for a set term, which makes it the default choice at most banks. Truly for a very short term, less than a year, a GIC or a high-interest savings account can make sense. Perhaps it’s a liquidity thing where money is needed in a short amount of time. But for anything beyond that, you are leaving a lot on the table.
The issue with GICs is straightforward. Your money is locked. Your rate is fixed. And in most years, that rate barely keeps pace with inflation. A 4% GIC sounds decent until you realize inflation is running at 3% and your real return is 1%. Inside a TFSA you are not paying tax on that 1%, which helps. But 1% real growth on money you cannot touch for five years is not building wealth. It is preserving it, slowly.
What most people do not realize is there is another guaranteed option inside a TFSA that does not have those limitations.
GIC inside TFSA
Principal protection: 100%, CDIC insured up to $100,000 per institution
Growth potential: Fixed rate only. Locked at purchase. No upside if markets rise.
Liquidity: Locked for 1 to 5 years. Early redemption penalties or not permitted.
Beneficiary: No named beneficiary. Goes through estate.
Creditor protection: None.
Segregated fund inside TFSA
Principal protection: 75% to 100% guarantee at both maturity and death
Growth potential: Market-linked. Much more upside because your principal’s protected. Reset feature locks in higher values.
Liquidity: Accessible. No lock-in period on most contracts.
Beneficiary: Named beneficiary. Bypasses probate entirely.
Creditor protection: Available in most provinces when beneficiary is named.
Seg funds can have 100% principal guarantees with lots of upside. Performance can far exceed a GIC, which may not be keeping pace with inflation. Plus there’s probate and named beneficiary benefits above and beyond that. And here is the part that gets missed: many seg fund contracts have guarantees that allow you to reset values. So your guarantees are based on the higher value. Your floor keeps moving up.
Seg fund MERs run higher than GIC rates. But when you factor in the guarantee, the probate bypass, and the tax-free compounding inside a TFSA, the net cost is often lower than it looks on paper. The fee pays for something a GIC simply does not offer.
Whatever rate of return you see on a policy like this should really be considered double in context. Because the growth is tax-sheltered. If it shows 5%, that’s 5% with no tax drag. A GIC or investment account at 5% has a tax bill every year. This doesn’t. Inside a TFSA, that advantage compounds even further because you were never paying tax on it to begin with.
The catch is you cannot walk into a bank and ask for a segregated fund TFSA. Seg funds are insurance products. They are only available through licensed brokers and advisors. Working with an independent broker means you likely have access to many different solutions from many different institutions, not just what one bank happens to sell.

TFSA vs RRSP, FHSA, and Other Registered Accounts
Under $50,000 in income, if you have TFSA room, I would lean heavily towards doing a TFSA contribution first and foremost. Above that threshold, the RRSP deduction starts to become a bigger lever. But this is not a fixed rule. It depends on your situation.
Banks and financial institutions have done a great job of really ingraining in clients that you should contribute to your RSP. But it doesn’t always make sense. The RRSP gives you a tax deduction on the way in, but you pay tax on every dollar you pull out. If you are in a low tax bracket now and expect to be in a similar or higher bracket later, the deduction you are getting today is not worth the tax bill you are creating in retirement.
My benchmark for RRSP contributions is at least a 30% return on contribution. That means you’re going to get back 30 cents on every dollar that you contribute. If your marginal rate is below 30%, the TFSA is almost always the better move.
How to think about which account comes first
First-time home buyer, no kids: FHSA first. You get the deduction of an RRSP while withdrawing from it is like a TFSA, and unlike an RSP, you don’t need to repay the funds. Up to $8,000 per year, $40,000 lifetime. Then TFSA, then RRSP.
Has kids: RESP first, at least to the $2,500 per year that triggers the full 20% CESG match. That is $500 per year in free government money, up to $7,200 over the child’s lifetime. Then RRSP or TFSA depending on your bracket.
Higher bracket, no kids, not buying a home: RRSP first for the deduction at a high marginal rate. Then TFSA with whatever is left.
Lower bracket: TFSA first. You could even transfer from a TFSA into an RSP with no tax implication, and make that contribution at a more optimal time when your income and marginal rate are higher.
One advantage that does not get enough attention: TFSA withdrawals do not count toward the OAS clawback threshold. RRSP and RRIF income does. In retirement, every dollar you pull from a RRIF pushes you closer to the point where the government starts clawing back your Old Age Security. TFSA income is invisible to that calculation. For anyone building a retirement income strategy, this is a significant planning lever.
Can You Have Multiple TFSAs or a Joint TFSA
You can have as many TFSA accounts as you want, at as many institutions as you want, but your total contribution room is shared across all of them. There is no such thing as a joint TFSA.
Yes: multiple accounts
You could have a savings TFSA at your bank, a GIC TFSA at a credit union, and a segregated fund TFSA through a broker. All three at the same time. The CRA does not care how many accounts you have. They care about the total going in across all of them.
No: joint accounts
A TFSA can only have one holder. You and your spouse each get your own room and your own accounts. You can contribute to a spouse’s TFSA using your own money without any attribution rules, but the account stays in their name only.
The most common mistake with multiple accounts is losing track of total contributions. If you max out at one institution and then open a second account somewhere else, the CRA sees both. There is no separate room per account. Check your total available room in CRA My Account before opening an additional TFSA anywhere.
What Happens to Your TFSA When You Die
Your TFSA can transfer to a surviving spouse tax-free, or be paid out to any named beneficiary tax-free. No tax on the principal, no tax on the growth up to the date of death. How it transfers depends on whether you named a successor holder or a beneficiary, and most people do not realize these are two very different things.
A successor holder can only be a spouse. The account just continues as is. Same account, same holdings, same contribution room structure. It rolls over seamlessly. A beneficiary can be a spouse, children, or anyone else. But the account gets collapsed and the funds are paid out directly.
Most advisors default to recommending the successor holder option. I often do the opposite.
Contrarian take
I often do advise clients to actually have named beneficiaries rather than successor holders. In an account such as a seg fund that has a 100% principal guarantee, it can actually be advantageous to set up the account as a beneficiary. Why? Because if the market value has dropped below the guaranteed amount at the time of death, the insurance company pays out the full guarantee, not the lower market value.
With a successor holder, the account just continues. The guarantee does not crystallize. The spouse inherits whatever the current market value is. With a named beneficiary and a 100% death benefit guarantee, the payout is the higher of the two numbers. That difference can be significant.
Compare this to what happens with an RRSP or RRIF on death. Unless it rolls to a surviving spouse, the entire balance gets added to the deceased’s final tax return as income. On a large RRSP, that can mean a tax bill approaching 53.5% on the balance. A $400,000 RRIF could lose over $200,000 to taxes in a single year.
A TFSA on death? Zero tax. No matter who receives it. That is one of the biggest planning advantages the TFSA has over any other registered account, and it rarely gets the attention it deserves.
Whatever you decide on successor holder versus beneficiary, make sure you also have a will in place. A named beneficiary on a TFSA overrides your will for that specific asset, but everything else in your estate still needs to be directed somewhere.
Where a TFSA Fits in Your Overall Financial Plan
The TFSA works best as the flexible core of a broader registered account strategy, not as your only account and not as an afterthought. Where it sits in your priority order depends entirely on your income, goals, and what other accounts you have access to.
One strategy I use regularly with clients that most people have never heard of: you could transfer from a TFSA into an RSP with no tax implication. Contribute to your TFSA throughout the year. Let it grow. Then at RRSP season, move a portion into your RRSP to generate the tax deduction. The TFSA withdrawal is not taxable income, so there is no cost on the way out. The RRSP contribution gives you the deduction on the way in. You’ve effectively used the TFSA as a staging account.
Take the tax refund you get from that RRSP contribution and put it right back into the TFSA the following January when your room resets. Now the cycle repeats.
The TFSA-to-RRSP cycle
Contribute to TFSA throughout the year → transfer to RRSP before deadline → claim the tax deduction → receive refund → recontribute refund to TFSA in January → repeat.
This works best when your income is climbing year over year and you want the RRSP deduction at a higher marginal rate. The TFSA acts as a holding account until the timing is right.
The other planning angle that ties directly to the TFSA is what happens to your RRSP at death. A large RRSP or RRIF balance can trigger a tax bill approaching 53.5% on the final return. Life insurance can be structured to offset that exact liability, dollar for dollar. The proceeds come in tax-free and cover the tax bill your estate would otherwise have to absorb. An insured retirement plan takes this a step further by using permanent life insurance as part of the overall income strategy.
The TFSA, by contrast, creates no tax problem at death. No tax on the balance, no tax on the growth. So the more wealth you can accumulate inside a TFSA during your lifetime, the less your estate has to deal with when you are gone. That alone is reason enough to max it out before anything else if your income allows it.
Frequently Asked Questions
Q1
Are TFSAs safe?
Yes. The TFSA itself is a government-registered account, not an investment product. How safe your money is inside it depends on what you hold. A savings deposit or GIC inside a TFSA is protected by CDIC insurance up to $100,000 per institution. A segregated fund TFSA provides 75% to 100% principal guarantees from the insurance company. Self-directed accounts holding stocks carry market risk, but the registration of the account is not the source of that risk.
Q2
Are TFSAs worth it?
For almost every Canadian, yes. The tax-free growth alone makes it one of the strongest wealth-building tools available. Even if you only use it as a savings account at a modest interest rate, you are still avoiding tax on that interest every year. If you use it for investments with higher growth potential, the compounding advantage over a non-registered account becomes significant within a few years. There is no scenario where having a TFSA is worse than not having one.
Q3
Are TFSA contributions tax deductible?
No. Unlike RRSP contributions, TFSA contributions do not reduce your taxable income. The trade-off is that withdrawals are completely tax-free. With an RRSP you get the deduction now and pay tax later. With a TFSA you get no deduction, but you never pay tax on the growth or withdrawals.
Q4
What happens if you over-contribute to a TFSA?
The CRA charges a penalty of 1% per month on the excess amount for as long as it remains in the account. They do not send a warning before the penalty starts accruing. The most common cause is withdrawing money mid-year and redepositing it before January 1, which counts as a new contribution against your current room. Check your available room in CRA My Account before making any large deposits.
Q5
Can you have a TFSA if you are not a Canadian citizen?
Yes, as long as you are a Canadian tax resident with a valid SIN. Citizenship is not required. Permanent residents, temporary residents, and work permit holders can all open a TFSA if they file Canadian taxes. Your contribution room starts accumulating from the year you became a tax resident, not from when you received permanent residency.
Q6
Is a high-interest savings account the same as a TFSA?
No. A high-interest savings account is a type of account you can hold inside a TFSA, but they are not the same thing. The TFSA is the registered shell that provides the tax-free status. A high-interest savings account is one of several options you can put inside that shell. You could also hold GICs, mutual funds, segregated funds, or stocks inside the same TFSA registration.
Q7
Can you transfer a TFSA from one institution to another?
Yes. You can request a direct transfer between institutions without affecting your contribution room. The key is to use the formal transfer process through the receiving institution, not to withdraw from one and deposit into another. A withdrawal followed by a deposit counts as a new contribution and could push you over your limit if your room is already used.
Q8
How do you check your TFSA contribution room?
Log in to your CRA My Account online. Your TFSA contribution room is listed under the TFSA section and is updated after each tax season based on issuer reports. Keep in mind the number may not reflect very recent transactions if your financial institution has not yet reported them. If you have multiple TFSA accounts at different institutions, the CRA tracks the total across all of them.
Independent. Multi-carrier. Licensed across 7 provinces.
Your TFSA deserves more than whatever your bank happens to sell
Whether you’re comparing GICs to segregated funds, figuring out contribution room, or coordinating your TFSA with your RRSP and FHSA, a broker who works across carriers can show you what a single institution never will.
Call 1-877-654-6119
Serving clients in Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, Nova Scotia, and New Brunswick since 2007.