 ·

Life Insurance After Divorce in Canada
By Parvesh Benning, Licensed Life Insurance Broker
The surprise after a divorce is not who you name as beneficiary, it is who controls the policy once your name is on it.
Divorce does not change your life insurance on its own. Your old policy, your old beneficiary, and any cash value all stay exactly as they were until someone takes action, and a court order can add requirements on top. Knowing what to change, what you control, and what you cannot, is what keeps support payments and your family protected.
Updated: June 16, 2026
Life Insurance After Divorce in Canada
By Parvesh Benning, Licensed Life Insurance Broker, Updated: June 16, 2026
The surprise after a divorce is not who you name as beneficiary, it is who controls the policy once your name is on it.
Divorce does not change your life insurance on its own. Your old policy, your old beneficiary, and any cash value all stay exactly as they were until someone takes action, and a court order can add requirements on top. Knowing what to change, what you control, and what you cannot, is what keeps support payments and your family protected.
After a divorce, the life insurance questions that actually matter are not really about paperwork, they are about control: who owns each policy, who is allowed to change the beneficiary, and whether a court order locks any of it in place.
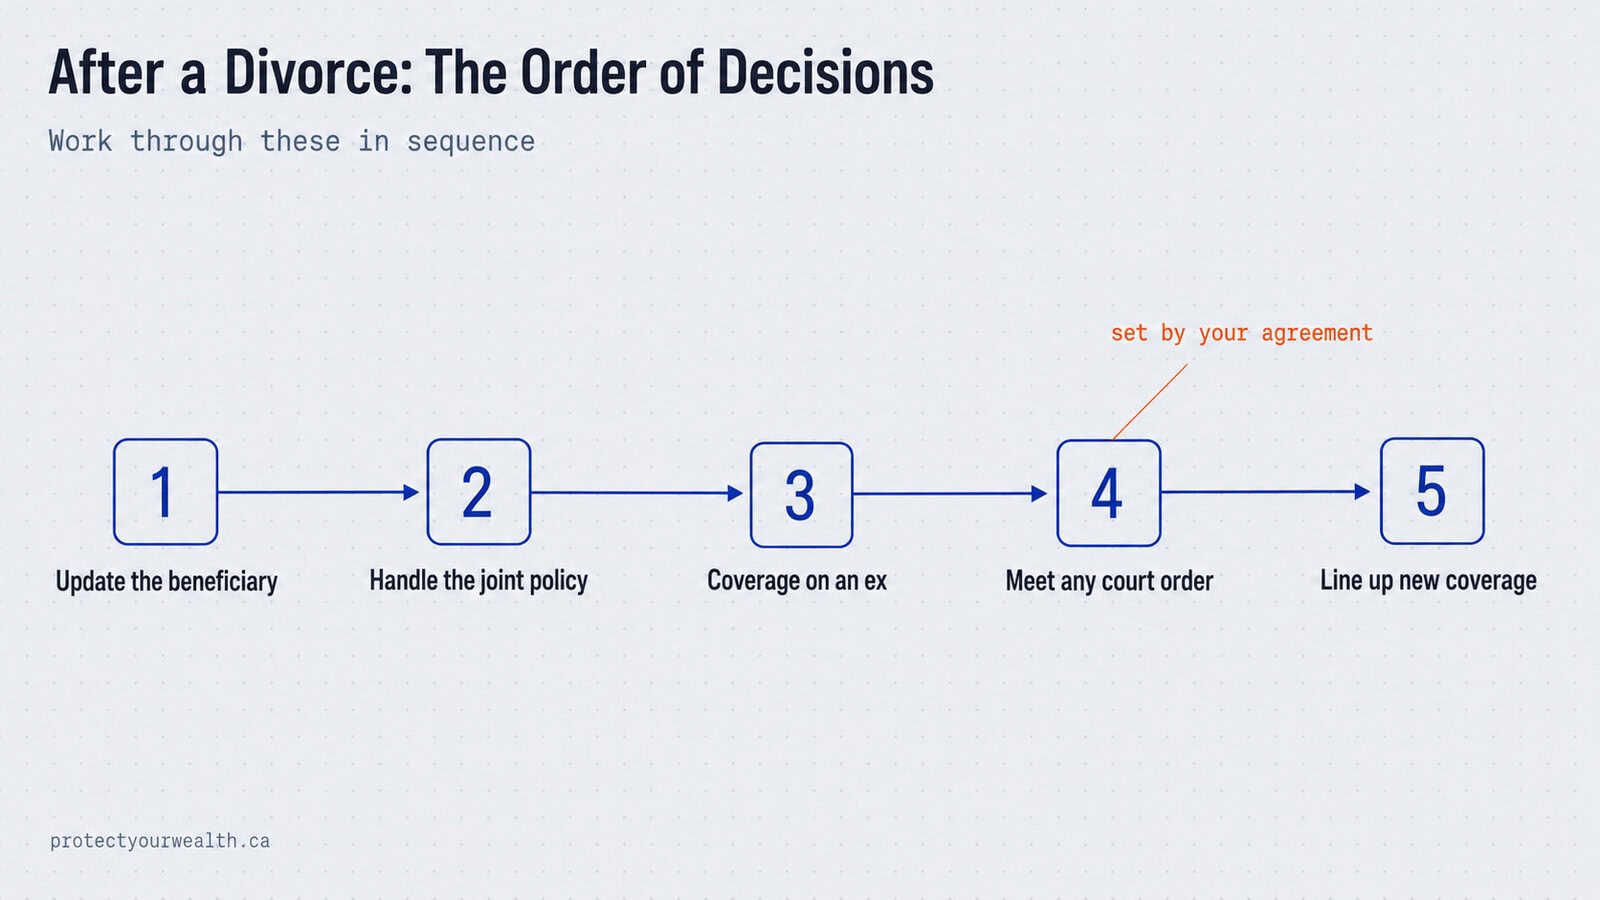
This guide walks through the real decisions in order: updating beneficiaries, handling a joint policy, keeping or owning coverage on an ex, meeting a court-ordered requirement, and lining up new coverage that fits your budget. Because an independent broker can compare more than 20 Canadian insurers in the time it takes to call one company, you can sort this out once, properly, instead of guessing.
Here is what shifts after a divorce, and what holds steady on its own:
What divorce does not change on its own
- Your existing policy stays in force. Premiums, coverage, and any cash value continue exactly as before.
- Your named beneficiary stays whoever you last named, even an ex-spouse, until you file a change.
- Being separated rather than divorced changes nothing about a policy already in force.
What you will usually need to update
- The beneficiary, unless a court order or separation agreement says to keep it as is.
- Ownership and who pays, especially on a joint policy or a court-ordered one.
- The coverage amount and type, to match your new budget and any support you owe.
Life Insurance After Divorce: Where to Start
Divorce does not divide your life insurance for you. The first move is separating two things it blurs together: the policy you own, and the policy someone owns on you.
Property and savings get discussed early in a separation. Life insurance usually does not, and that gap is where people get caught later. What counts as a marital asset depends entirely on the type of coverage you hold.
Term life
No cash value, so on its own it is rarely something to divide. Each spouse usually just keeps or replaces their own policy.
Whole life or universal life
Builds cash value, and that value can be treated as family property to divide under provincial law.
A separation agreement or court order may require one spouse to carry life insurance when child support, spousal support, or another financial obligation needs to be protected.
The Quebec exception
Quebec automatically revokes a spouse as beneficiary on divorce. Everywhere else in Canada, including every province we work in, nothing is automatic. Your ex stays your beneficiary until you file the change yourself.
After a separation, your coverage usually moves in one of four directions:
Keep it. Hold an existing policy in force to protect a child or an ex who still depends on the coverage.
Divide it. Treat the cash value in a permanent policy as part of how property gets split.
Add to it. Put new coverage in place to satisfy a court order securing support.
Replace it. Move from a joint or shared policy to individual coverage you fully control.
This article explains the insurance side of divorce planning. For legal advice about your separation agreement, court order, or property division, speak with a family lawyer in your province. Which path fits depends on what you own, what the agreement says, and what you can qualify for now. This is where comparing carriers pays off, because the same situation gets priced and underwritten very differently from one insurer to the next. For the legal side, the federal Department of Justice family law resources are a useful starting point.
Updating Your Beneficiary After Divorce
Outside Quebec, your ex stays your beneficiary until you file the change in writing with the insurer. The divorce itself does not do it.
This is the step people assume happens automatically. It does not. A separation agreement does not override it. A new will does not override it. The insurer pays whoever is on the beneficiary form, and that form is the only thing that decides where the money goes at claim time.
Whether you can change it depends on how the beneficiary was set up:
So the real question is not just whether you want to change it. It is whether you are allowed to yet. If support is in play, your agreement may require you to keep an ex or your children named for a set period. Read the agreement before you file anything, because filing a change you were not allowed to make can put you offside a court order.
One more piece that catches people. If you name a minor child directly, the payout cannot go straight to a child under the age of majority. Without a trustee named in the policy, the money can sit under court control until the child grows up. Naming a trustee, or setting the designation up properly, keeps that from happening. Our guide on naming a life insurance beneficiary in Canada covers how to do it.
Not sure whether your designation is revocable or irrevocable, or who is even listed right now? That is worth a quick check. A broker can pull the policy and read it with you. Get in touch and we will confirm where things stand.
Managing a Joint Policy After Divorce
Not every company will let you split a joint policy into two, so do not assume it is automatic. Some carriers allow it. Plenty do not.
This is the part that trips couples up. A joint first-to-die policy was built around two people staying together. When that ends, you cannot always just cut it down the middle and walk away with half each. At some carriers the only clean exit is for one person to requalify for new coverage on their own, at their current age and health.
And that is the catch. Requalifying years later, often after a stressful divorce, can mean a higher premium or a tougher underwriting outcome than the original joint rate. So the policy you thought you could simply divide may not divide on the terms you expected.
Here is how the two common setups actually behave when a relationship ends:
This is exactly why, when clients ask me about joint coverage up front, I walk them through the trade-off before they sign. A joint first-to-die looks cheaper on day one. Two individual policies cost a bit more but give each person full control and remove the splitting problem entirely if the relationship ever ends. For couples who want to understand the structures before deciding, our overview of joint life insurance in Canada breaks down how each option works.
If you are already holding a joint policy and going through a separation, the move is to find out, in writing, what your specific carrier allows before you make any decision about cancelling or dividing it. A broker can check that for you across insurers rather than you calling one company and taking a single answer. Talk to a broker directly before you touch the policy.
Court-Ordered Life Insurance
When timing is of the essence, we look at providers where we can get coverage in place as quickly as possible. If the client is healthy and the case is straightforward, some fully underwritten applications can move quickly, but timing depends on the insurer, the amount, age, health history, and whether medical evidence is required.
A lot of separation agreements and court orders attach life insurance to support. The idea is simple: if the person paying child or spousal support dies, a policy keeps that money flowing to the kids or the other spouse. The order usually names a coverage amount, who has to be insured, and a deadline to prove the coverage exists.
That deadline is where people panic. They think any policy will do as long as it is in force by the date. It will not. Here is the part that matters most:
The no-medical trap
Some quick no-medical policies have graded or deferred death benefits, meaning they may return premiums instead of paying the full death benefit if death happens in the first couple of policy years. Grab the wrong one to hit a court deadline and the policy can technically satisfy the order while leaving your kids with almost nothing if something happens early. The deadline gets met. The protection does not exist yet.
So the goal is coverage that is both fast and pays in full from day one. When health allows it, a fully underwritten policy is the cleaner answer, and it is not always slow. When there are health concerns, or the underwriting will take longer, that is where we lean on traditional simplified plans to get something solid in place quickly. The key is matching the product to the deadline without quietly downgrading what the coverage actually does.
Who pays
Usually the person ordered to carry it, but the agreement can assign it either way. The payer keeps the policy in force.
Who owns it
Often the supported spouse owns the policy so they control it and can confirm it stays active. Control matters more than people expect.
Proof and monitoring
The order may require ongoing proof the policy is in force. Owning it, or being an irrevocable beneficiary, is how you keep eyes on it.
If you are staring down a court deadline right now, the worst move is grabbing the first policy you can find online. A broker can line up the fastest option that still pays in full and matches what the order actually requires. No-medical and simplified options have their place here, but only the right ones. Talk to a broker directly and we will work to the deadline with you.
New Coverage After a Divorce
Being separated rather than divorced does not impact a policy that is already in force. If the coverage is being paid for and it is active, it continues, no matter your marital status.
People assume separating freezes or cancels something. It does not. The one thing to remember is that beneficiary changes can only be made by the owner, or owners. On a joint policy with two owners, both parties have to sign off on a change. So your status does not touch the policy, but who controls it still does.
“Your marital status does not impact a policy that’s already in force. Beneficiary changes can only be done by the owner or owners.”
The harder question is usually money. After a split, one income is covering what two used to, and the premium that felt fine before can suddenly feel like too much. The instinct is to cancel. That is almost always the wrong first move.
When the premium stops fitting the budget, here is the order I work through:
Whether reducing is even viable depends on the scenario, and that is an honest assessment, not a sales pitch. Sometimes the policy is worth keeping at a lower amount. Sometimes a fresh policy elsewhere is cheaper. The point is to look before you cancel, because once coverage is gone, getting it back means requalifying at your current age and health. If you are rebuilding coverage from scratch, our guide to term life insurance in Canada is a good starting point. If you would rather just have someone run the numbers, talk to a broker directly and we will compare the options side by side.
Frequently Asked Questions
Q1
Does divorce automatically remove my ex as my beneficiary in Canada?
No, not outside Quebec. In every province we work in, your ex stays your named beneficiary until you file a change form with the insurer. Quebec is the lone exception, where divorce revokes a spouse beneficiary automatically. Everywhere else, the divorce decree does not touch the policy on its own.
Q2
Can I keep a life insurance policy on my ex-spouse after divorce?
Yes, if your ex agrees and signs as the insured, and there is a genuine reason for the coverage such as ongoing support. You can own the policy, be the beneficiary, and pay the premiums. If you already owned a policy on them before the divorce, you can usually continue it as the owner. A new policy needs the insured person’s signed authorization.
Q3
Can a joint life insurance policy be split when we divorce?
Sometimes, but not always. Some carriers allow a joint first-to-die policy to be separated into individual coverage, many do not, and splitting can require one or both people to requalify at their current age and health. Do not assume a clean split is possible until your specific insurer confirms it in writing.
Q4
Who pays for court-ordered life insurance after a divorce?
Usually the person ordered to carry the coverage, which is typically the spouse paying support, though the agreement can assign it either way. Often the supported spouse owns the policy so they control it and can confirm it stays in force. Check what your specific order requires before assuming.
Q5
Does being separated but not divorced change my life insurance?
No. A policy already in force continues as long as it is being paid, regardless of marital status. The one thing to remember is that beneficiary changes can only be made by the owner or owners, so on a jointly owned policy both parties have to sign off on any change.
Q6
What happens to the cash value in a permanent policy during a divorce?
The cash value in a whole life or universal life policy can be treated as family property and divided under provincial law. A term policy has no cash value, so on its own it is rarely something to divide. How the value is handled depends on your province and your agreement, so confirm the tax and division details with your lawyer.
Q7
Can I name my children as beneficiaries instead of my ex?
Yes, but a payout cannot go directly to a child under the age of majority. Without a trustee named in the policy, the money can end up under court control until the child comes of age. Naming a trustee, or setting the designation up properly, avoids that delay. A separation agreement may also require you to keep the children named for a set period.
Q8
I cannot afford my premium after the divorce. What are my options?
The first option is usually reducing the coverage amount, which lowers the premium while keeping a policy in force. Check that any court-ordered minimum still allows it, then compare the market, because another carrier may price the same coverage lower. Cancelling should be the last resort, since getting coverage back later means requalifying at your current age and health.
Q9
How fast can I get coverage to meet a court-ordered deadline?
If you are healthy and the case is straightforward, some fully underwritten applications can move quickly, depending on the insurer, the amount, your age, your health history, and whether medical evidence is required. When there are health concerns or underwriting will take longer, a traditional simplified plan can get coverage in place quickly. The key is choosing one that pays in full from day one, not a plan that only returns premiums in the early years.
Q10
What happens if my will and my policy beneficiary say different things?
The beneficiary form on the policy wins. A life insurance payout passes outside your will, so the named beneficiary on the policy is who gets paid, even if your will says otherwise. This is exactly why updating the beneficiary form after a divorce matters as much as updating the will.
Finding the Right Coverage After Your Divorce
After a divorce, the right move is rarely the dramatic one. It is usually a few correct adjustments: the beneficiary, the ownership, the amount, and proof of anything a court ordered.
None of that has to be overwhelming. Most of it comes down to reading your policy and your agreement side by side, then matching the coverage to what you actually need now. As an independent brokerage, we compare options across more than 20 Canadian insurers, so you can sort it out once instead of calling one company and hoping their single answer is the right one. If you are weighing whether to keep, reduce, or replace coverage, our guide to types of life insurance in Canada is a useful next read.
Let’s talk through your options
Licensed life insurance and segregated fund solutions across Ontario, Alberta, British Columbia, Manitoba, Saskatchewan, New Brunswick, and Nova Scotia. No pressure, no obligation.
Prefer to call? Reach us at 1-877-654-6119 and speak with a licensed broker directly.





