·
Life Insurance in Canada for Any BMI
By Parvesh Benning, Licensed Life Insurance Broker
Two insurers can look at the exact same height and weight and reach opposite answers, and that gap is the whole story.
Most people think the problem is their weight. It is not. The problem is which insurer the application lands on. I have seen one carrier offer standard rates and another decline the same person on the same day. That is a routing decision, not a weight decision, and it is fixable.
Updated: June 8, 2026

Life Insurance in Canada for Any BMI
By Parvesh Benning, Licensed Life Insurance Broker, Updated: June 8, 2026
Two insurers can look at the exact same height and weight and reach opposite answers, and that gap is the whole story.
Most people think the problem is their weight. It is not. The problem is which insurer the application lands on. I have seen one carrier offer standard rates and another decline the same person on the same day. That is a routing decision, not a weight decision, and it is fixable.
Build charts are not standardized in Canada. Every carrier sets its own height and weight limits, and the gap between the most and least flexible is wide enough to change your rate, or your approval outright.
Empire Life’s thresholds look nothing like Manulife’s, and even within one company different products draw the line in different places. A person declined at one carrier can qualify easily at another. There is usually more than one path:
Fully underwritten. Standard rates, or a higher premium called a rating.
Simplified issue. Fewer medical questions, more flexible on build.
No-medical. Some products never ask height or weight at all.
From my own files
One client’s BMI exceeded the charts of nineteen of the twenty insurers I reviewed. The twentieth said yes. He walked away with $300,000 in coverage. That is what knowing the differences actually buys you.
Your weight alone often does not disqualify you. Applying to the wrong carrier can, and that part is fixable.
On this page
- What is BMI?
- Free BMI calculator
- How insurers use BMI in Canada
- BMI on simplified issue policies
- How to qualify if you’re overweight
- When BMI combines with another condition
- Bariatric surgery, by carrier
- Getting a better rate after weight loss
- If you’re underweight
- What life insurance costs at a healthy BMI
- Frequently asked questions
What is BMI?
Body Mass Index (BMI) estimates body fat from your height and weight. It is your weight in kilograms divided by your height in metres squared (BMI = kg/m²). Insurers treat it as one baseline measure of build, not the full picture.
Underweight
Below 18.5
Healthy
18.5 to 24.9
Overweight
25 and above
A number outside the healthy range does not decide the outcome on its own. It is the starting point underwriters work from, alongside your health, your history, and which carrier sees the file.
BMI Calculator (Metric & Imperial)
How Do Insurers Use BMI for Life Insurance in Canada?
Every insurer uses BMI as a starting point, but the chart they measure you against is theirs alone, and no two are the same. That is the part most people miss. They think there is one standard. There isn’t.
Take a 6’0″ client at 310 lbs. At Industrial Alliance, that person can land standard rates on a fully underwritten policy. Same specs at Empire Life on the same kind of product? You’re looking at a rating that can nearly double the premium. Same person. Same health. The only thing that changed was whose desk it went to.
It gets stranger inside a single company. A client rated on that carrier’s fully underwritten product can sometimes qualify standard on its simplified issue product. The spread within one insurer can be as wide as the spread between two.
So the numbers below are real maximums for standard rates, height by height. Watch the right-hand column. Industrial Alliance isn’t a little more generous, it is in a different league on build alone, which is exactly why I’m checking it first for a heavier client.
| Height | Manulife | Canada Life | Empire Life | Desjardins | Industrial Alliance |
|---|---|---|---|---|---|
| 5’2″ | 143 lbs | 145 lbs | 148 lbs | 150 lbs | 204 lbs |
| 5’4″ | 150 lbs | 152 lbs | 155 lbs | 157 lbs | 217 lbs |
| 5’6″ | 158 lbs | 159 lbs | 162 lbs | 164 lbs | 230 lbs |
| 5’8″ | 166 lbs | 168 lbs | 170 lbs | 172 lbs | 244 lbs |
| 5’10” | 175 lbs | 176 lbs | 178 lbs | 180 lbs | 258 lbs |
| 6’0″ | 183 lbs | 184 lbs | 186 lbs | 188 lbs | 273 lbs |
| 6’2″ | 192 lbs | 194 lbs | 195 lbs | 197 lbs | 288 lbs |
Maximum weight for standard rates, illustrative only, subject to underwriting and change. Verify against current carrier guidelines. Scroll the table sideways on mobile.
At 5’8″, four of these carriers cut standard rates off somewhere around 166 to 172 lbs. Industrial Alliance goes to 244. That is a 70-plus pound difference on the same line, and it is the entire reason I never let a client assume a decline at one company means anything about the next. If a rating does come back, that is usually the moment I pull simplified issue options alongside it to compare.
How Is BMI Treated on Simplified Issue Policies?
Simplified issue is where a lot of people who get rated or declined on a regular policy actually get covered. No medical exam, just a short health questionnaire, and the build limits run a good deal higher. Assumption Life and Humania, for instance, will not knock you back on weight alone unless it is extreme or paired with other risk.
The trade is real, though. You pay more per dollar of coverage and the maximum face amounts are lower. But if you are sitting above the fully underwritten cutoff, a standard simplified rate beats a heavy rating or a flat no. I would rather get someone covered today on simplified than chase a regular policy that was never going to land.
Look at the same heights below versus the regular chart above. The whole range shifts up. And the last column is the safety net: guaranteed issue asks no build question at all.
| Height | Beneva | CPP | iA | Assumption | Guaranteed |
|---|---|---|---|---|---|
| 4’10” | 199 | 185 | 190 | 192 | no max |
| 5’0″ | 213 | 199 | 200 | 205 | no max |
| 5’2″ | 228 | 215 | 220 | 219 | no max |
| 5’4″ | 243 | 220 | 220 | 233 | no max |
| 5’6″ | 258 | 235 | 240 | 247 | no max |
| 5’8″ | 274 | 260 | 260 | 262 | no max |
| 5’10” | 290 | 260 | 260 | 278 | no max |
| 6’0″ | 307 | 282 | 280 | 294 | no max |
| 6’2″ | 325 | 305 | 300 | 310 | no max |
Maximum weight in lbs for standard simplified issue rates, illustrative only, subject to underwriting and change. Verify against current carrier guidelines. Scroll the table sideways on mobile.
How Do I Qualify for Life Insurance if I’m Overweight?
Unless you have other serious health concerns, your weight alone will not stop you from getting covered. It may cost more, but it rarely closes the door.
When someone calls me worried about their build, I am not shopping the whole market. I already know which companies run more flexible height and weight thresholds, so I am pulling two or three guides, not twenty, to see where this person actually lands.
If the read is a rating on a fully underwritten policy, I am checking no-medical and simplified options in the same breath. Here is why. A fully underwritten file near the top of the build chart usually means a full nurse visit, blood and urine, sometimes a report from your doctor. Simplified skips all of it. A lot of the time it ends up being the cheaper and faster path anyway, not the fallback people assume it is.
One detail most people miss: some carriers use a single unisex build chart, others split it by sex. If you are female, a unisex chart can work in your favour. That is the kind of thing a broker who actually reads these guides catches before anything gets submitted.
Do not assume a decline. Unless your BMI clears most insurers’ decline thresholds, you have a real shot at standard or lightly rated terms, especially if your other health markers are stable. Build is not the whole story. Someone active and muscular at 5’5″ and 155 lbs often reads better than someone sedentary at the same number.
Should You Lose Weight Before Applying?
A lot of advice online says lose the weight first, then apply. I think that is risky advice.
The risk you are insuring against exists today, not after twelve months of dieting. There is nothing wrong with locking in the best coverage available right now and treating it as a bridge. If your health improves later, we go back to the market and look for something cheaper at that point.
Things happen. People develop conditions in the year they spend waiting to “qualify better,” and then they are insuring a higher BMI plus a new diagnosis instead of just a higher BMI. I treat it the same as a smoker: get the plan today, and if they stay quit for twelve months, we reapply for better rates down the road. You do not leave them uncovered in the meantime.
Address the risk today. Optimize later.
When Your BMI Combines With Another Condition: How Carriers Actually Decide
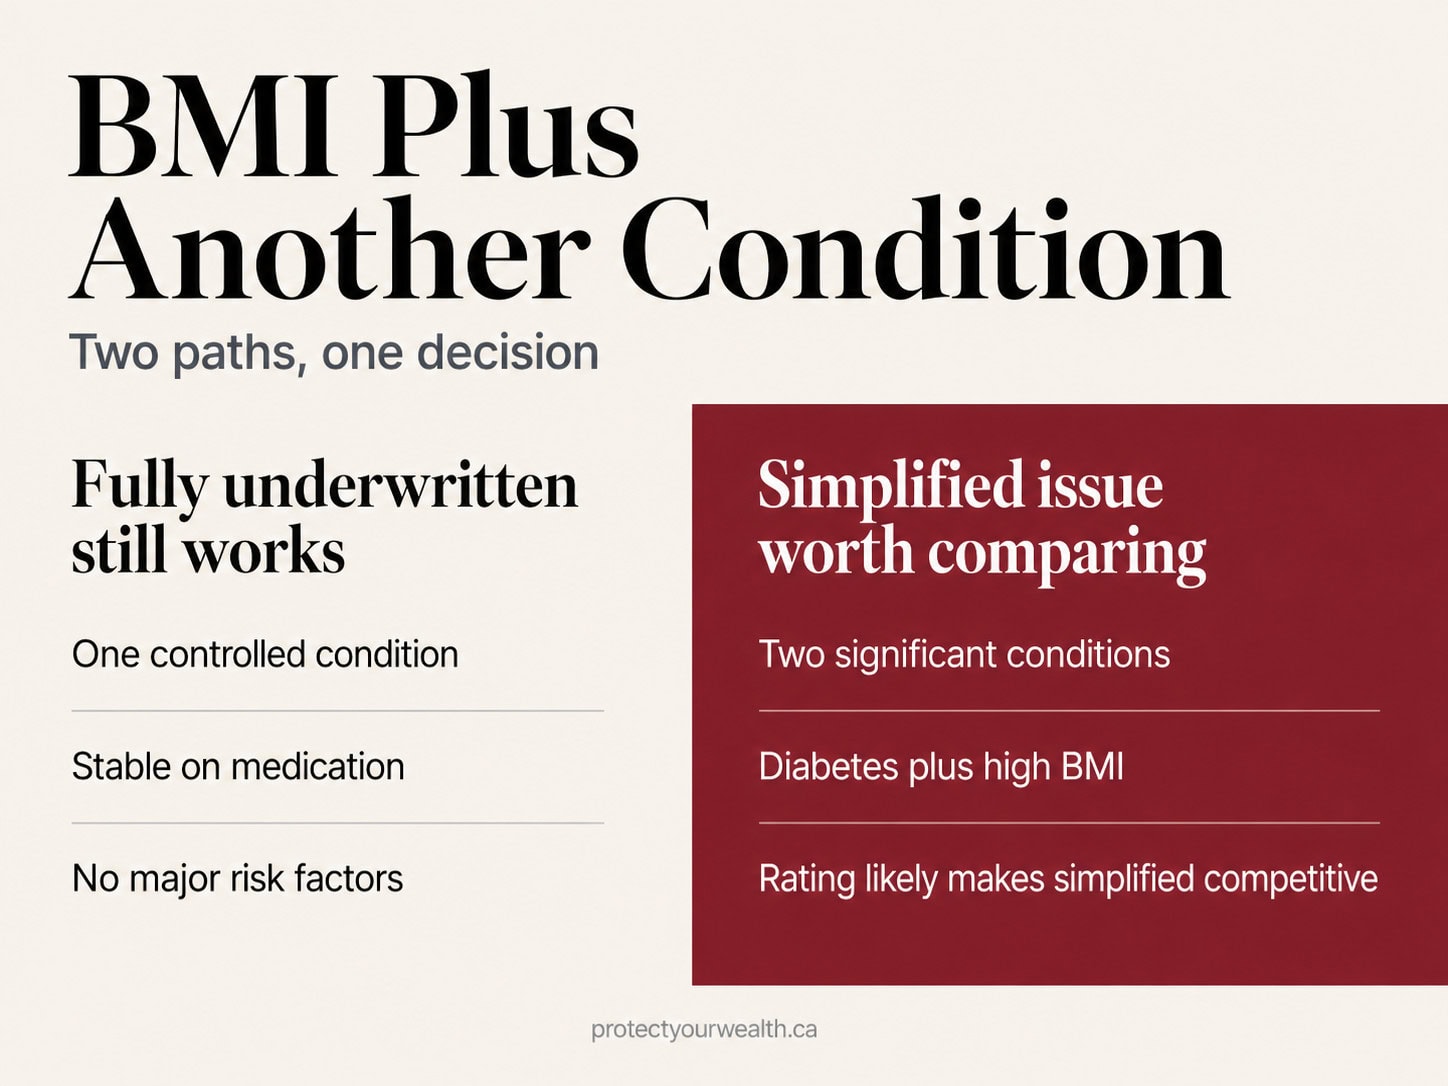
One condition alongside a higher BMI does not close the fully underwritten door. Two significant ones can. What decides it is which conditions, how well controlled they are, and whose underwriting desk sees the file.
Build on its own is one conversation. Build plus a second factor is a different one, because underwriters stop pricing your weight and start pricing the pattern it points to.
Controlled Conditions: The Fully Underwritten Path May Still Be Open
Here is how I actually think about it. A client with a BMI of 33 and well-controlled high blood pressure, stable readings on medication, no complications, is still a realistic candidate for standard rates at the right carrier. The phrase that matters is well controlled. Underwriters are not just asking what conditions exist. They are asking whether those conditions are managed and stable.
Sleep apnea works the same way. Someone on CPAP and compliant is sending a positive signal, not a negative one, because the condition is being treated. Pair that with a higher BMI, and an anonymous check with the underwriter before anything is formally submitted tells me fast whether we are in standard or rated territory.
When Two Significant Conditions Shift the Path
Type 2 diabetes alongside a high BMI is where the path shifts more decisively. At a fully underwritten carrier that combination usually means a significant rating, sometimes large enough that a simplified issue policy ends up cheaper. I run both side by side in those cases, because a rated fully underwritten premium is not automatically lower once the multiplier hits. Life insurance with diabetes walks through the carrier-by-carrier picture on that condition in more detail.
The Decision Framework in Plain Terms
Fully underwritten is still the right path when:
A high BMI sits with one controlled condition (hypertension, sleep apnea on CPAP, mild cholesterol).
Medications are stable, with no recent hospitalizations and consistent follow-up care.
No additional significant risk factors are on the file.
Simplified issue is worth comparing when:
A high BMI combines with Type 2 diabetes or multiple conditions.
The fully underwritten application is likely to draw a significant rating.
The simplified premium may match or beat a rated fully underwritten plan.
The right carrier for a clean file is often the wrong one once a second factor is in play. Matching the full picture to the company that prices it best, before anything is submitted, is the entire job.
Bariatric Surgery and Life Insurance: Waiting Periods by Carrier
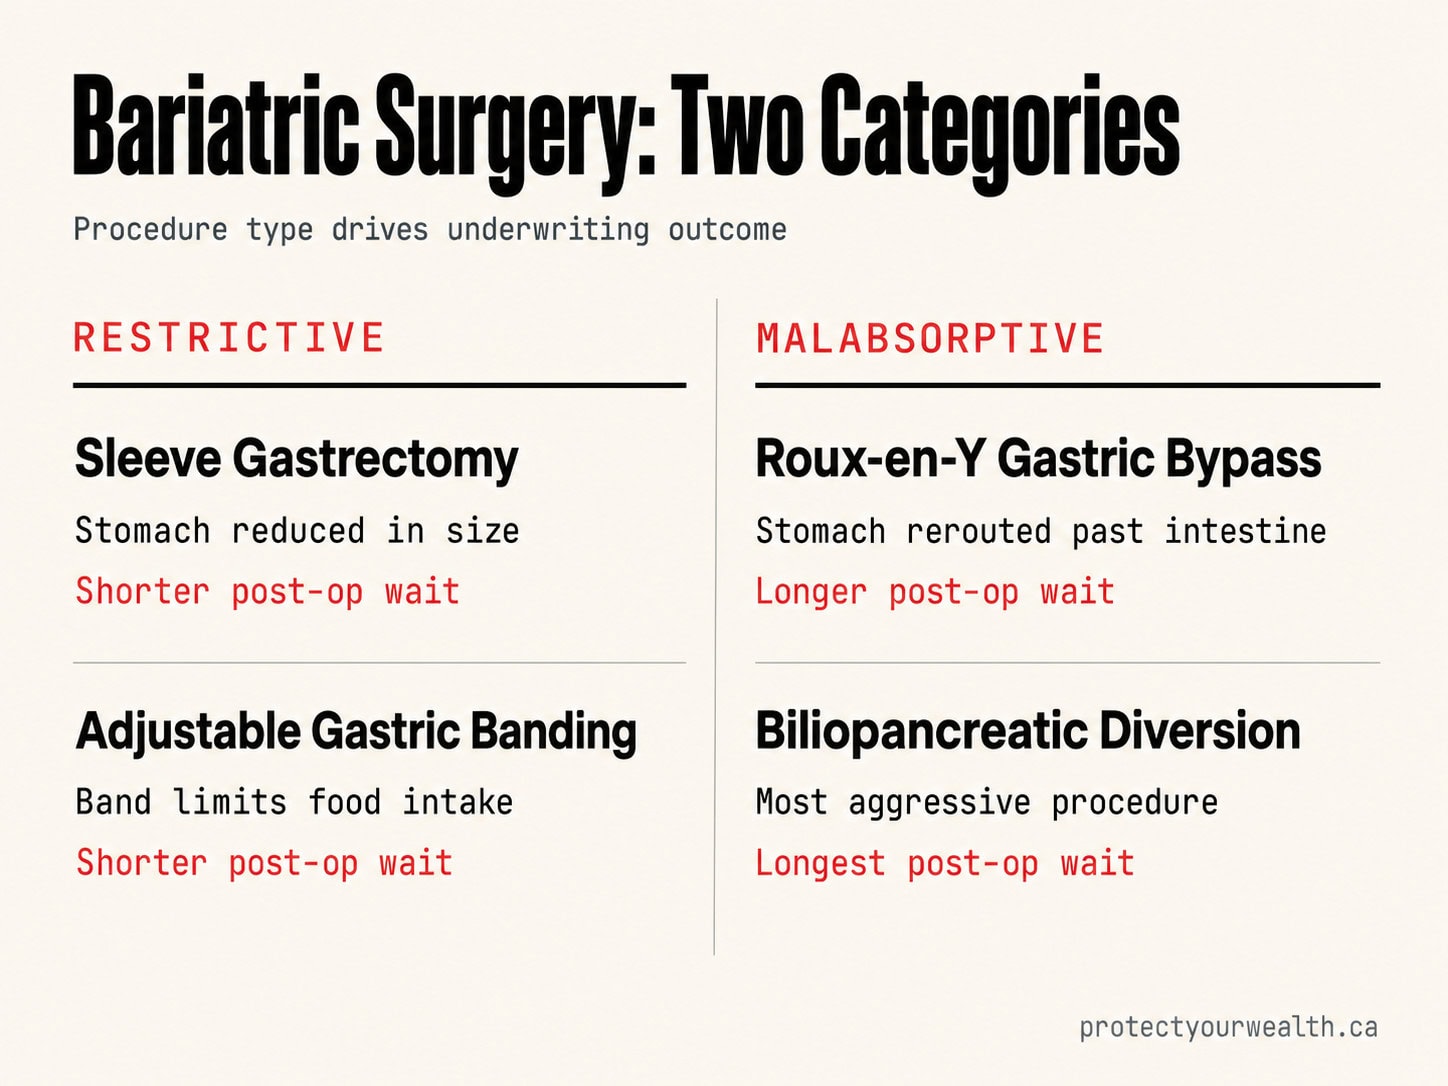
You can get life insurance after bariatric surgery. Timing is the thing that matters most, and the rules shift by carrier and by which procedure you had. The split that drives underwriting is whether your surgery was restrictive or malabsorptive.
The Four Main Types of Bariatric Surgery
Bariatric surgery is used for clinically severe obesity, generally a BMI of 40 or above, or 35 and above with serious related conditions. Gastric bypass is the most common procedure in Canada. Which category yours falls into matters before you apply, because insurers use that split to set both your waiting period and your rating.
Sleeve Gastrectomy
Part of the stomach is removed, reducing its size and limiting food intake.
Restrictive
Generally better terms. Some carriers consider applications as early as 3 months post-op.
Adjustable Gastric Banding
A band around the upper stomach restricts how much can be eaten at one time.
Restrictive
Generally better terms. Some carriers consider applications as early as 3 months post-op.
Roux-en-Y Gastric Bypass
The stomach is reduced and rerouted to bypass part of the small intestine, cutting both intake and absorption.
Malabsorptive
Longer waits. Most carriers require at least 6 months post-op before considering an application.
Biliopancreatic Diversion
The most aggressive procedure: removes a large part of the stomach and bypasses a significant section of small intestine.
Malabsorptive
Longest waits. Ratings tend to run higher than other procedure types at most carriers.
How Different Carriers Handle Bariatric Applications
Carrier rules differ on waiting periods, procedure type, and how complications affect the rating. Here is what underwriting actually looks like at the major Canadian insurers.
| Carrier | Waiting period | Typical rating range |
|---|---|---|
| Canada Life | 3 months restrictive, 6 months malabsorptive | Standard to +150% restrictive, up to +175% malabsorptive |
| Empire Life | 6 months minimum, declines within 6 months of surgery | Based on current height and weight, complications assessed separately |
| Industrial Alliance | 6 months post-op | Standard to +150% with no complications, +100% to decline with complications |
| RBC Insurance | Postpone or decline within 6 months | Standard to +175%, with more possible depending on current build |
| Beneva | 6 months minimum post-surgery | Based on current height and weight at time of application |
Ratings illustrative only, subject to underwriting and change. Verify against current carrier guidelines. Scroll the table sideways on mobile.
What all carriers look for
Across every insurer, three signals carry the most weight: weight stabilization, no surgical complications, and consistent follow-up with your surgeon.
A report from your doctor or surgeon is usually required. Underwriters want evidence the surgery worked and your health is trending in a stable direction.
The practical takeaway: six months is the standard threshold at most carriers. Apply before that window closes and you almost always get a postpone. Apply just after it, with good weight stabilization and clean follow-up records, and you are in a far stronger spot than someone who waited years and lost the documentation trail.
How to Get a Better Rate After Losing Weight
Getting covered now at a rated premium is not a permanent outcome. If your health improves and your weight comes down meaningfully, you go back to the market, and that first policy becomes the bridge it was always meant to be.
The threshold most carriers want is one year of weight stability at the lower level. Not a year of active loss, a year at the new weight. Insurers care about your BMI at the time of the new application, not how many pounds you dropped or how fast. A slow, steady loss held for 12 months reads better than a dramatic recent drop that is still unproven. Loss explained by diet and exercise is straightforwardly positive. Unexplained significant loss is a flag, not a benefit.
1
Call your broker and review where you land. We check your current BMI across the carrier guides and see whether the picture has improved enough to change your rating class.
2
Pick the right move. Depending on how much your build has changed, that is a fresh fully underwritten policy at a better rate, a formal reconsideration request to your current carrier, or a short wait for more stability before submitting anything.
3
Hit the threshold, then move. A wait is not a failure. It is the same advice I give a newly quit smoker: you have 12 months of non-smoker status to earn before the better rates apply. Keep the coverage in place, reach the mark, then reapply.
One thing worth knowing: a new application may ask whether you have lost 10 or more pounds in the past year. That question screens for unintentional loss, it is not there to penalize people who worked at it. If the answer is yes and the reason is diet and exercise, that context matters and belongs in the application.
Life Insurance When You’re Underweight
Being underweight can affect your application, but rarely because of the number itself. Underwriters want to know why.
A naturally lean build that has held steady for years is a non-issue at most carriers. The flag goes up when the low weight is recent, unexplained, or still moving. I treat it like a medication question: if someone is on thyroid medication and their weight has held on it, that stability is the story, not the diagnosis. Recent instability gets priced. A decade-steady lean build does not.
The cause is the whole question. A low BMI alongside a managed thyroid condition, a gastrointestinal absorption issue, a stable eating disorder history, an autoimmune or chronic illness, or longer-term bone density concern is assessable once it is explained and stable. A low BMI with no explanation and a recent drop is what slows things down.
Assessable
Bloodwork requested, recent weight history reviewed, stable cause confirmed. Standard or lightly rated.
Held back
Weight still moving, so a decision is delayed until it stabilizes, or a rating is applied for a manageable cause.
Pivot
Fully underwritten declined in the hardest cases. This is where I move to a no-medical or simplified option.
The reason behind the number decides the outcome, not the number. Matching that reason to the right carrier is what gets someone covered.
What Does Life Insurance Actually Cost at a Healthy BMI?
At a standard build with no other concerns, term life insurance is cheaper than most people expect. These are illustrative starting points for a healthy, non-smoking applicant on a 20-year term:
Male, age 40, $500,000
from $43.65/month
Female, age 40, $500,000
from $32.40/month
Illustrative standard rates for non-smokers on a 20-year term, based on current carrier rates, subject to underwriting and change. Your own quote depends on age, health, and coverage amount.
Here is the part that matters for build. A rating does not add a flat fee, it multiplies the standard premium. A +50% rating on that $43.65 male example puts it near $65 a month. A +100% rating roughly doubles it to about $87. That is why which carrier you apply to matters so much: a standard approval at one company can cost less than a rated approval at another, for the same person on the same day.
Frequently Asked Questions
Q1
Can I get life insurance if I am overweight in Canada?
Yes. Being overweight alone rarely prevents someone from qualifying for life insurance in Canada. The outcome depends heavily on which carrier you apply to, since each insurer uses its own build chart with different thresholds. Some carriers offer standard rates at weights where others would apply a rating or decline.
Q2
Can you be denied life insurance for being overweight?
Outright denial purely for weight is uncommon unless your BMI exceeds the maximum threshold across all carriers. Most overweight applicants qualify for coverage, though premiums may be higher depending on build and other health factors. If fully underwritten coverage is declined, simplified issue and no-medical options remain available.
Q3
What is a build chart in life insurance?
A build chart is a proprietary height and weight table used by life insurers to assign underwriting classifications. Each Canadian insurer maintains its own build chart, and the thresholds vary significantly. At 5’8″ and 240 lbs, for example, iA Financial and Beneva offer standard rates while Empire Life applies a 150 to 200 percent rating on the same applicant.
Q4
What BMI is too high for life insurance in Canada?
There is no single BMI threshold that applies across all Canadian insurers. Fully underwritten carriers typically decline applications at a BMI above 50, though rating adjustments begin well before that point. At a BMI of 40 or above, simplified issue and no-medical life insurance options remain accessible, with some products offering up to $300,000 in coverage without asking about height or weight.
Q5
Is there life insurance with no height or weight questions in Canada?
Based on current application wording, Humania’s no-medical life insurance product does not ask about height or weight at any point. Coverage is available up to $300,000 and the application is completed entirely online. This option is accessible regardless of BMI.
Q6
Can I get life insurance after bariatric surgery?
Yes, but the timing and terms depend on the type of surgery and the carrier. Most Canadian insurers require a minimum six-month waiting period after malabsorptive procedures such as gastric bypass. Restrictive procedures like a gastric sleeve may be considered as early as three months post-op at some carriers including Canada Life. Weight stabilization and a report from your doctor are typically required.
Q7
Can I get a lower life insurance rate after losing weight?
Yes. Most Canadian insurers want to see one year of stability at the new weight before considering a rate review. BMI at the time of the new application matters more than the number of pounds lost. If the weight loss is explained by diet and exercise, insurers generally view it positively. A broker can assess whether reapplying is likely to improve your rate class.
Your BMI is rarely the whole story. The carrier you apply to is.
We hold build charts from nearly 20 Canadian carriers. Before anything formal is submitted, we check your height and weight against the actual guides, find the path that fits your situation, and give you real numbers to compare.
20
Canadian carrier guides on hand
25+
Years helping Canadians with complex underwriting
$0
Cost to compare your options with a broker
Call us: 1-877-654-6119
Based in Hamilton. Serving Ontario, BC, Alberta, Manitoba, New Brunswick, Nova Scotia, and Saskatchewan, including Guelph, Medicine Hat, Burnaby, and Portage la Prairie.