 ·

Life Insurance Beneficiary Rules in Canada
By Parvesh Benning, Licensed Life Insurance Broker
The beneficiary section takes two minutes at the application stage, and it is the part of a policy I see done wrong most often.
Your beneficiary designation decides who receives your death benefit, how quickly it arrives, and whether anyone can interfere with it. This guide covers the rules in Canada: who you can name, how irrevocable designations actually work, and the mistakes that are easiest to prevent.
Updated: June 12, 2026
Life Insurance Beneficiary Rules in Canada
By Parvesh Benning, Licensed Life Insurance Broker, Updated: June 12, 2026
The beneficiary section takes two minutes at the application stage, and it is the part of a policy I see done wrong most often.
Your beneficiary designation decides who receives your death benefit, how quickly it arrives, and whether anyone can interfere with it. This guide covers the rules in Canada: who you can name, how irrevocable designations actually work, and the mistakes that are easiest to prevent.
Most people treat the beneficiary line as a form field: write a name, sign, done. In my practice it is closer to the steering wheel of the whole policy, because every dollar of the death benefit follows that designation, not your will, and not what you told your family you intended.
Here is the short version before we get into the rules.
A life insurance beneficiary is the person or organization you name to receive your policy’s death benefit, paid directly to them when you die.
Tax-free. In most cases the payout is not taxable income to the beneficiary.
Bypasses your estate in most cases. A named beneficiary is usually paid directly, outside probate.
Yours to change. Designations are revocable unless you deliberately lock them in.
In this guide
- What is a life insurance beneficiary?
- Who can be a beneficiary in Canada?
- The four types of beneficiaries
- How irrevocable beneficiaries actually work
- Naming options: estate, trust, charity, or a minor
- The beneficiary mistakes that are easiest to prevent
- How to change a beneficiary
- What happens if you never named one
- Taxes and how the payout is made
- Frequently asked questions
What is a life insurance beneficiary?
A life insurance beneficiary is the person or organization named in your policy to receive the death benefit when you die, paid directly by the insurance company without passing through your estate. That last part matters more than most people realize. The money does not wait for your will to be read or your estate to be settled. The insurer pays the named beneficiary the death benefit payable under the policy, and in most cases the beneficiary pays no income tax on it.
The rule that surprises people
Your designation outranks your will. If your policy names your brother and your will says everything goes to your spouse, the insurance payout goes to your brother. A will does not reach into a policy with a valid named beneficiary.
I see the full comparison of these two documents trip people up constantly, which is why we wrote a separate guide on life insurance beneficiaries vs wills in Canada.
Privacy is the other piece. Your will becomes public record through probate. An insurance payout to a named beneficiary does not. No public filing, and no insurance company even knows the payout from another. For some families that privacy is the entire reason the designation exists.
Who can be a beneficiary in Canada?
Almost anyone can be named, although the insurer may ask questions when the relationship is not obvious or when someone else owns or applies for coverage on the insured person, and insurable interest comes down to one thing: showing why this person would be financially or emotionally impacted if you passed away. For a spouse, your kids, your parents, that is automatic. Nobody questions it. For anyone else, you may need to explain the connection, and I have placed policies for non-standard relationships by doing exactly that. It is about demonstrating the impact, not fitting a category.
Spouse or common-law partner
One warning. A common-law partner is never automatic. If their name is not on the designation, they are not the beneficiary, no matter how long you have been together.
Family members
Children, parents, siblings, other relatives. Named individually, each with a percentage of the payout that you choose.
A friend or dependant
This is where insurable interest may need explaining, but it can be done. Setting up life insurance involving someone else works the same way.
A registered charity
A way to leave a legacy with your policy. There is a whole strategy around charitable life insurance as a gift in Canada.
A trust, a business, or your estate
All three are legal. Each has consequences worth understanding before you pick one, covered in the naming options section below.
The beneficiary does not need to live in Canada or hold Canadian citizenship. And this all applies to workplace group coverage too. Your basic life insurance through an employer has its own beneficiary form, and it is usually the most neglected designation a person has.
What are the types of life insurance beneficiaries?
There are four types of beneficiaries in Canada: primary, contingent, revocable, and irrevocable. And the simplest way to understand them is that every designation answers two separate questions. Who is in line for the money, and can you change your mind later.
Question one, the order of the line:
Question two, whether the decision is locked:
You will sometimes see articles count three types, sometimes four. Same concepts, different slicing. What matters is that your designation is really both choices at once: a primary who is revocable, a contingent who is irrevocable, any combination you set.
How do irrevocable beneficiaries work in Canada?
An irrevocable beneficiary cannot be removed from your policy, and their share of the death benefit cannot be reduced, without their written consent. In my practice, irrevocable designations in divorce settlements are quite common. That is the real-world home of this designation: a separation agreement requires one ex-spouse to keep a policy in force with the other named irrevocably, so support obligations survive even if the policyholder remarries or changes their mind. The lock is the entire point.
What the lock actually covers surprises people. With an irrevocable beneficiary in place, you generally cannot change the designation, and depending on the contract you may also need their consent to do things that affect their interest, like assigning the policy or cancelling it. You have handed over a measure of control of your own policy. Deliberately.
Where I have seen it go wrong is with children. I have seen a child named irrevocable, and that becomes a genuine issue if a payout or change is needed before they turn 18, because a minor cannot legally consent to anything. Neither can their parent or trustee on this specific question. The designation is effectively frozen until the age of majority. This is typically not something ideal, and it is usually done by a well-meaning parent who wanted to make the protection permanent without being told what permanent means.
Where irrevocable makes sense
- Divorce or separation agreements securing support, which often go hand in hand with the coverage questions in life insurance and divorce in Canada
- A lender or agreement that requires a guaranteed, untouchable designation
- Estate situations where the named person must have certainty the designation cannot quietly change
Where it backfires
- Naming a minor child irrevocably. Nobody can consent to changes until they reach majority, so the policy is frozen on that point
- Any relationship that might change. An uncooperative irrevocable beneficiary can refuse consent forever
- Defaulting into it without realizing, which is a Quebec-specific trap covered below
One province plays by different rules. In Quebec, a legally married spouse you name as beneficiary is automatically irrevocable unless you specifically mark the designation revocable. In every other province, revocable is the default. We are licensed outside Quebec, so for Quebec policies confirm the details with a Quebec-licensed advisor, but every Canadian should know the rule exists because plenty of people buy a policy in one province and move.
My general position: revocable unless something specific, usually a legal agreement, requires the lock. If you are signing a separation agreement that calls for an irrevocable designation, get the policy side reviewed before you sign, not after.
Estate, trust, charity, or a minor: how each option plays out
You are not limited to naming a person, but each alternative changes how the money moves. The problem with naming your estate is simple: if the estate has liabilities or creditors, they can go after the life insurance benefits. A directly named beneficiary is paid outside the estate and that protection disappears the moment the estate itself is the beneficiary. Here is how I walk clients through the options.
WHO
An individual (or several)
The standard route, and usually the right one. Direct payment, no probate, creditor protection, privacy. Split between people in any percentages you want. If one of them has died, the share follows your contingent instructions, which is why that line exists.
ESTATE
Your estate
Legal, but you give up the three big advantages at once: the payout joins the estate, may face probate costs and delays, and sits exposed to creditors. Would I ever do it deliberately? If someone genuinely has no one in particular to leave the benefit to, or wants everything distributed exactly as the will directs, perhaps. But ideally name a beneficiary where possible. If your estate plan is doing the heavy lifting, make sure the will itself is solid; we cover that in why you should have a will.
TRUST
A trust
A trustee receives and manages the payout under your instructions. This is the serious tool for two situations: beneficiaries who cannot manage money yet, and beneficiaries who should never receive a lump sum directly, including family members with disabilities where a direct payout could affect their support. Parents in that second situation should read our guide on life insurance for parents of disabled children. Trust setup is lawyer territory; the designation side is ours.
CHARITY
A registered charity
Name the charity directly and the payout goes to the cause, with potential tax credits depending on how the gift is structured. Structure matters here, because naming the charity as beneficiary and transferring ownership of the policy are taxed differently. Worth a conversation before you set it.
MINOR
A minor child
You can name your kids. What you cannot do is have the insurer hand a cheque to a twelve-year-old. Without a trustee appointed on the designation, the money can end up held by the courts or a public guardian until the age of majority. Naming a trustee for your kids takes a minute at the application stage, and it is one of the two omissions I flag most. The full picture of insuring and protecting kids is in our life insurance for children guide, and what happens when there is no trustee is exactly where the next section starts.
The beneficiary mistakes that are easiest to prevent
Not naming secondary beneficiaries is easily preventable. So is naming a trustee for your kids. Unfortunately I have seen situations where horrible things can occur from skipping these, and both take two minutes at the time of setting up the policy.
Mistake 1: No trustee for minor kids
I have seen the court or public guardian become involved in managing the money. Courts deciding on guardians, whether there was a will, the family waiting months. Naming a trustee at setup is one line on a form.
Mistake 2: No contingent beneficiary
Most people name their spouse and stop. No backup means the payout defaults to your estate and lands in probate. Common in families where kids were born after the policy was set up.
Mistake 3: The wrong decade
The ex-spouse still named from before the remarriage. The parent named at 24, three kids nowhere on the policy. Outside Quebec, one form fixes it. The bad ones are the claims where nobody checked.
Most articles get this backwards. They tell you to review your beneficiaries constantly. In my experience, a designation set up correctly the first time rarely needs touching. It is the major life events that demand a review: a marriage, a divorce, a death in the family, kids being born. If one of those happened since you signed, check it this week.
Cannot remember who is on your designation? That just means the policy predates a chunk of your life. Checking is part of any proper policy review, and it costs nothing.
How do you change a life insurance beneficiary?
For a revocable designation, you change your beneficiary by filing one form with your insurance company: no consent needed, no notice to the old beneficiary, no cost. Every insurer has its own version of the change form, most handle it electronically now, and the change is official once the insurer records it. Keep the confirmation.
The steps, in the order they actually happen:
When should you do this? Going back to what I said above: not on a schedule, on events. Marriage. Divorce, where the designation question gets legally complicated fast. A death. A birth, especially kids born after the policy was set up, who need to be added as contingents. A new policy, where the form starts blank and the old designation does not carry over. Group coverage at a new job, same thing.
Two cautions. An irrevocable beneficiary who will not consent cannot be forced off the policy; that is the lock working as designed, and no form fixes it. And changing the beneficiary in your will does not change the policy. The policy designation wins, so the two documents need to agree, or the policy version is the one your family lives with.
This is also the moment to say the quiet part: most of the beneficiary problems on this page get caught in a twenty-minute policy review, and fixing them costs nothing. If your policy predates your marriage, your kids, or your divorce, get in touch and we will pull the designation apart with you, whether or not we sold you the policy.
What happens if you never named a beneficiary?
If no beneficiary is named, or every named beneficiary has died before you, the death benefit is paid to your estate by default. Three things follow from that, none of them good.
Probate
The payout waits for estate settlement instead of going straight to your family.
Costs
Estate administration tax and legal fees come off the top before anyone inherits.
Creditors
Money in the estate is reachable by the estate’s debts. A named beneficiary’s payout generally is not.
Every one of those is avoided by a designation that takes two minutes. That asymmetry is the whole argument of this page.
Is the payout taxable, and how does it actually arrive?
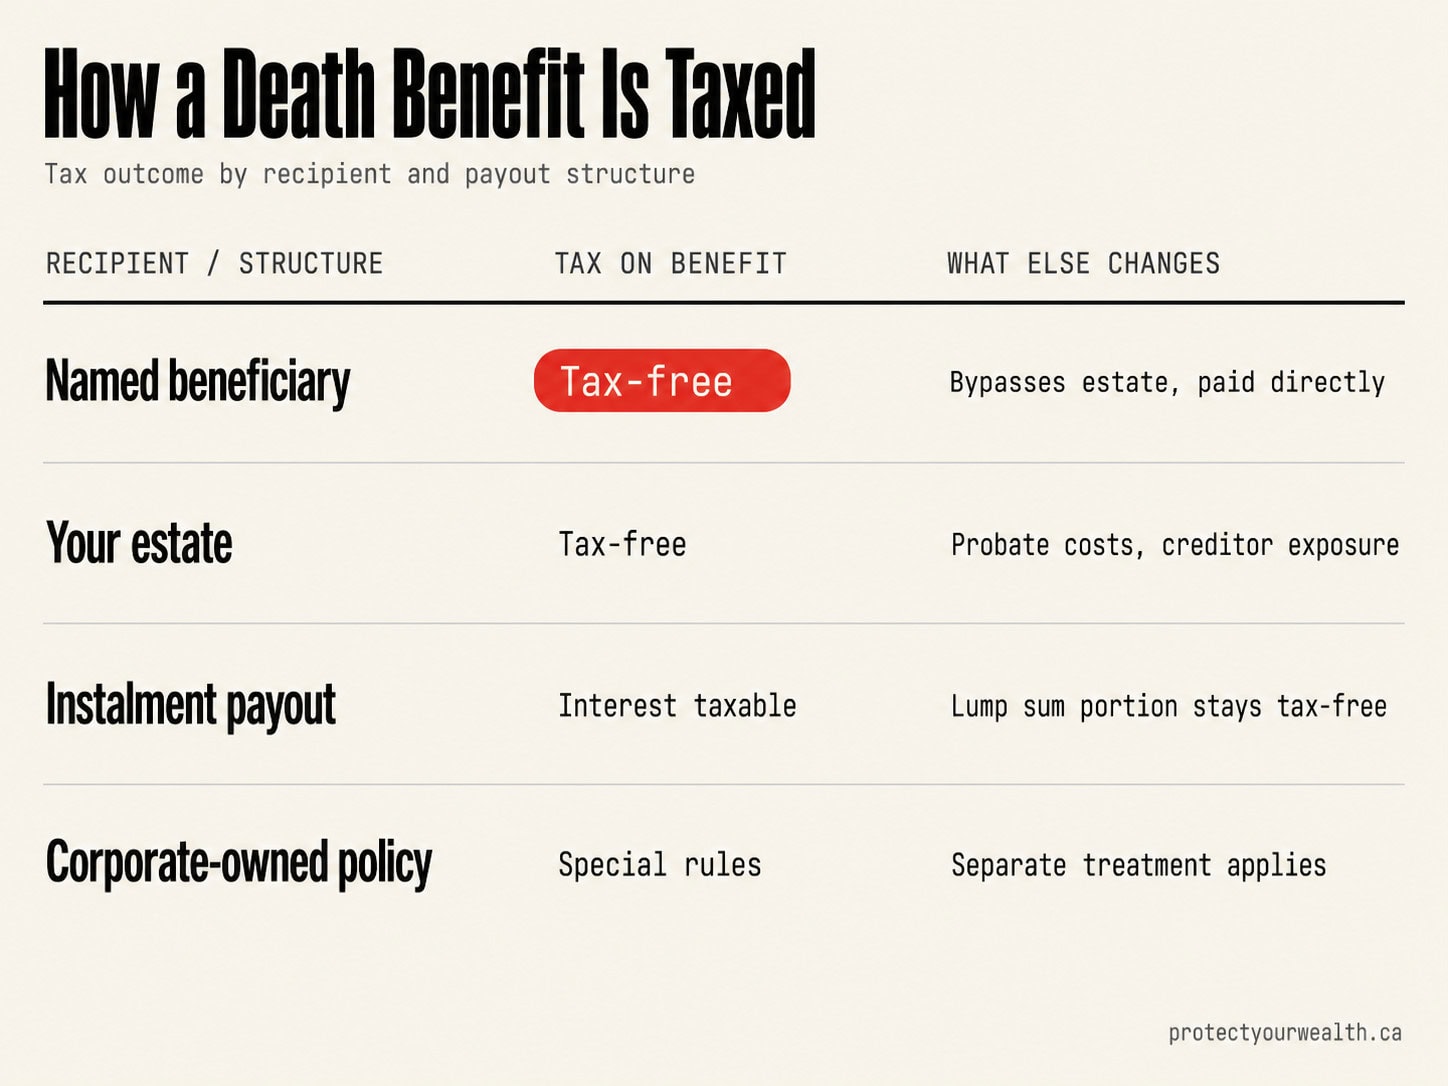
In Canada, a life insurance death benefit paid to a named beneficiary is generally received tax-free, and in my practice the money typically arrives within 5 to 10 business days of a completed claim, by direct deposit, with most claims handled through the insurer’s online portal these days. The beneficiary files the claim with a death certificate, the insurer reviews, the deposit lands. For families this is usually faster and cleaner than they expected.
Where it can slow down is when the insurer asks for more. I had an unfortunate situation where a client who was 35 died suddenly. The policy had been in force four years, the claim was paid, but the insurance company required the physician’s records and the autopsy report first, which was surprising to the family. Unexpected deaths get extra review. That is normal claim practice, not a sign the claim is in trouble, but nobody warns families it can happen. The cases where claims genuinely do not pay are a different topic, covered in why life insurance claims get denied in Canada.
The tax exceptions worth knowing:
- Estate as beneficiary. The benefit itself stays tax-free, but inside the estate it becomes subject to probate costs and creditor claims, the problems above.
- Instalment interest. Take the payout as instalments instead of a lump sum and any interest the insurer pays on the balance is taxable income.
- Corporate-owned policies. Different rules entirely; the full picture is in our guide on whether life insurance is taxable in Canada.
One contrast that puts the tax-free payout in perspective: registered accounts do not get this treatment. An RRSP left to someone other than a spouse or financially dependent child is generally taxed as income on the deceased’s final return. The insurance death benefit does not face that tax. An RRSP inherited by the next generation can lose roughly half to tax on the final return. The insurance designation is one of the few places in Canadian planning where the full number on the page is the number your family receives. If no percentages are listed, the insurer will usually divide the payout equally among surviving beneficiaries, but it is better to state the percentages clearly.
Frequently asked questions about life insurance beneficiaries
Q. What are the 3 types of beneficiaries?
Most lists count primary, contingent, and revocable or irrevocable as the third. In practice there are four concepts in two pairs: primary and contingent set the order of payment, revocable and irrevocable set whether the designation can be changed without consent.
Q. Can I name multiple beneficiaries on one policy?
Yes. Name as many as you want and assign each a percentage; the shares must total 100. If you name several without percentages, insurers divide the payout equally among the surviving beneficiaries.
Q. Is my common-law partner automatically my beneficiary?
No. A common-law partner receives the death benefit only if they are named on the designation. Years together do not create a designation, and this is one of the most painful gaps I see on older policies.
Q. Does a will override a life insurance beneficiary?
No. A valid beneficiary designation on the policy is paid regardless of what the will says. The will only controls the death benefit when the estate itself is the beneficiary, by choice or by default.
Q. What happens if my beneficiary dies before me?
Their share goes to your contingent beneficiary if you named one. If you did not, and no other primary survives, the payout defaults to your estate, with the probate, cost, and creditor exposure that brings.
Q. Who can change the beneficiary on a policy?
The policy owner, not the person insured. The insured signs at setup and essentially gives control to the owner from that point on. On most policies the owner and the insured are the same person, but when they are not, the owner holds the pen.
Q. Who is the beneficiary on my group life insurance at work?
Whoever you wrote on the enrolment form, often years ago, and if you left it blank the benefit defaults to your estate. Group coverage has its own designation separate from any personal policy, and it is usually the most outdated one a person has.
Q. Can a beneficiary be denied the payout?
Yes, in limited situations: the policy lapsed before death, an exclusion applied, or the application contained misrepresentation inside the contestability window. We break down each scenario in when and why death benefits are denied.
Get the designation right while it is still a two-minute job
Whether you are setting up a new policy or have one that predates your marriage, your kids, or your divorce, we will review the beneficiary side with you at no cost. As an independent brokerage providing life insurance and segregated fund solutions since 2007, we compare policies from Canada’s top insurers and make sure the two-minute details are done right the first time.
Get a Quote Talk to a Broker Directly
Or call 1-877-654-6119. Based in Hamilton, serving clients anywhere in Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, Nova Scotia, and New Brunswick.





