 ·

Infinite Banking in Canada: How It Actually Works
Written by Parvesh Benning, Licensed Life Insurance Broker
Four real carrier illustrations, one identical setup, and the year your cash value passes what you actually put in.
Infinite banking gets sold as a system. Strip the marketing away and it is a max-funded participating whole life policy built to stack cash value early, with more than one way to borrow against it. This guide shows the real structure, real numbers from four Canadian carriers, and where the loans actually come from.
Updated: June 11, 2026
Infinite Banking in Canada: How It Actually Works
Written by Parvesh Benning, Licensed Life Insurance Broker, Updated: June 11, 2026
Four real carrier illustrations, one identical setup, and the year your cash value passes what you actually put in.
Infinite banking gets sold as a system. Strip the marketing away and it is a max-funded participating whole life policy built to stack cash value early, with more than one way to borrow against it. This guide shows the real structure, real numbers from four Canadian carriers, and where the loans actually come from.
The proper structure for this concept is simple to describe and easy to get wrong: minimum base coverage, maximum additional deposit option (the extra money you are allowed to pay into the policy on top of the base premium), with dividends buying more paid-up coverage. That combination builds cash value fast. Whether you ever borrow against it is up to you. Most of my clients don’t borrow until a need or opportunity shows up, and some never do. The flexibility is the point.
Below you will see the same $50,000-a-year setup illustrated at four different Canadian insurers, the year the cash value passes what you put in, and an honest look at where the loans should actually come from.
What infinite banking actually is
Infinite banking in Canada is a participating whole life policy funded to its maximum allowed deposit level so cash value builds quickly, which you can then borrow against for any purpose. The policy keeps growing on the full cash value even while a loan is outstanding.
The structure: minimum base, maximized deposit option, dividends buying paid-up additions
The access: two borrowing routes, a policy loan from the insurer or a bank line of credit against the cash value
The timeline: in the max-funded designs shown below, cash value passes total deposits in 4 to 5 years (current dividend scale, not guaranteed)
Skip ahead:
- Infinite Banking in Canada: A Concept, Not a Product
- What Is Infinite Banking?
- What Type of Whole Life Policy Does Infinite Banking Require?
- How Infinite Banking Works in Canada
- The Pros of Infinite Banking in Canada
- The Cons of Infinite Banking in Canada
- How to Set Up an Infinite Banking Policy in Canada
- Real Infinite Banking Examples: Four Carrier Illustrations
- Policy Loans vs Bank Loans: Which Way to Borrow?
- Risks and Limitations of Infinite Banking in Canada
- Is Infinite Banking Legit or a Scam?
- Tax Advantages of Infinite Banking in Canada
- Corporate Infinite Banking: Using Retained Earnings
- Is Infinite Banking Right for You?
- Frequently Asked Questions About Infinite Banking
Infinite Banking in Canada: A Concept, Not a Product
Infinite banking is really just a concept, and honestly, the name doesn’t do it justice. There is no infinite banking product sold in Canada. What actually gets set up is a participating whole life insurance policy built one specific way: minimum base coverage, maximum deposit option, dividends buying more paid-up coverage. The “banking” part is just one thing you can do with the cash value that design creates.
Here’s my issue with how this gets marketed. Programs sell it as a system you need certification to understand. Mandatory borrowing, repayment schedules to yourself, the whole framework. The reality is simpler. You build cash value inside a life insurance policy that grows tax-sheltered, and you can borrow against it when a need or opportunity shows up. Repay on your schedule, or let it settle from the death benefit later. The policy keeps compounding on the full cash value the whole time, even with a loan outstanding.
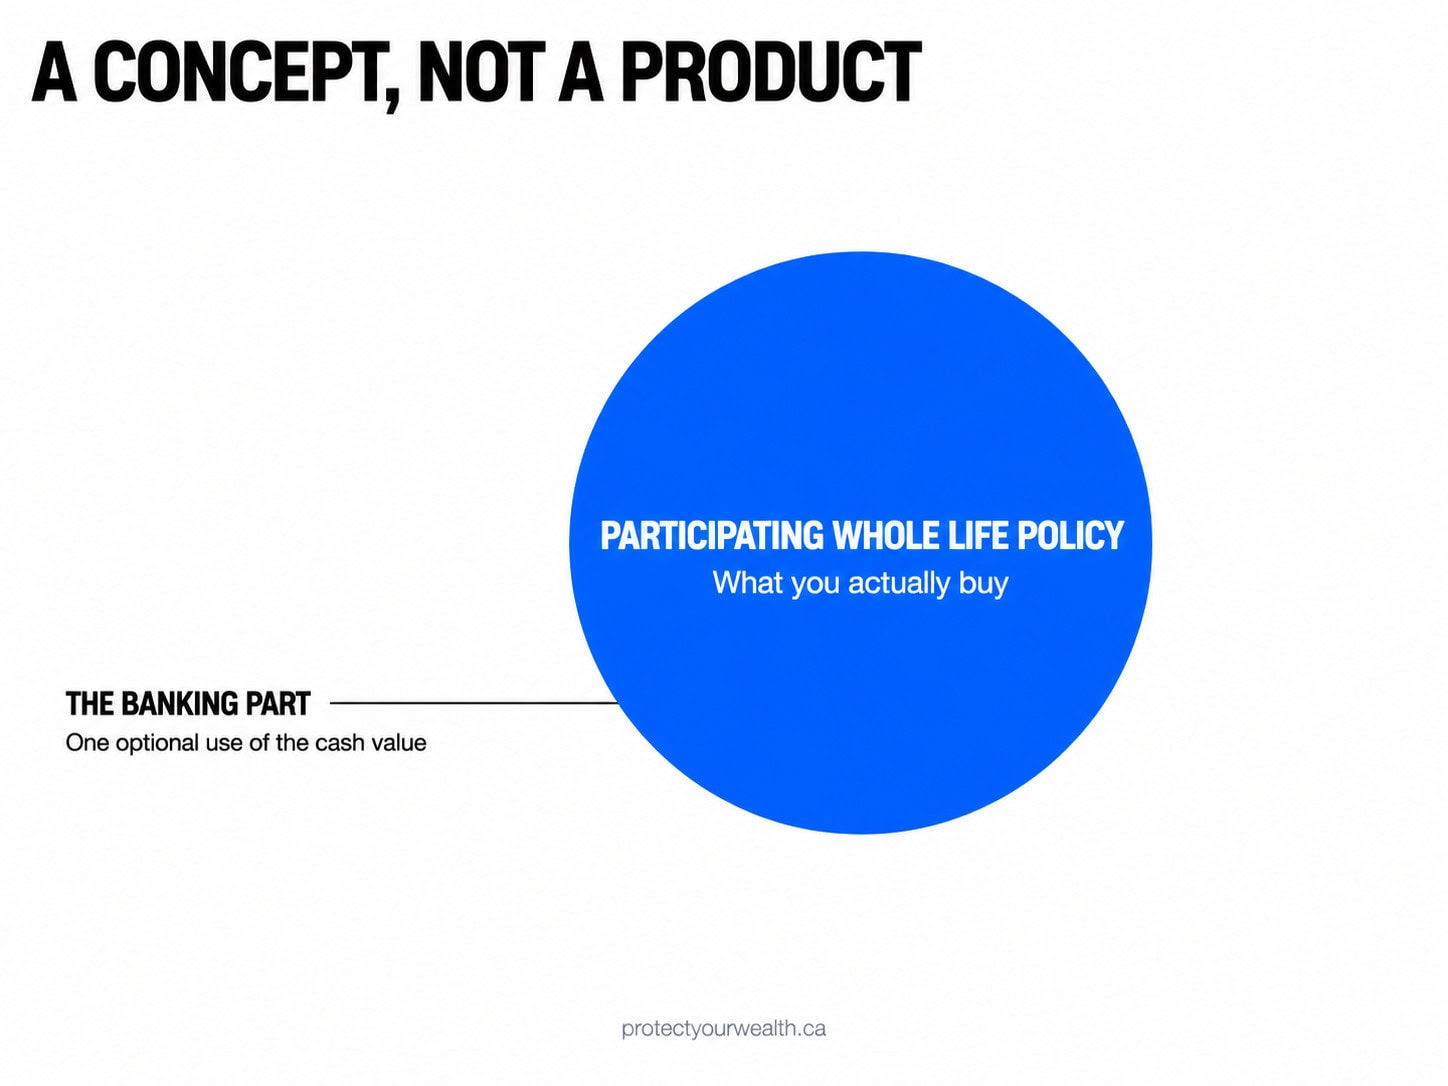
And you don’t have to borrow at all. Most of my clients don’t necessarily borrow unless they have a need or opportunity. The idea of the concept is what is appealing, the flexibility to execute. That doesn’t mean all take out loans.
Same chassis, retirement use: the identical max-funded policy powers an insured retirement plan, where the borrowing waits until retirement.
Same chassis, corporate use: businesses run the structure on retained earnings, covered in the corporate section below.
That’s the lens for this guide: the actual setup, real illustration numbers from four Canadian carriers, and a straight answer on where the loans should come from when you do borrow.
What Is Infinite Banking?
Infinite banking is a strategy where you use the cash value of a participating whole life policy as your own borrowing capacity, instead of going to a bank every time you need capital. You borrow against the policy, use the money, repay on your own terms. The policy keeps growing in the background the entire time.
The part most people miss: not all whole life policies, even from the same insurance company, are designed the same. Two policies with the identical annual premium can produce completely different cash values depending on how that premium splits between base coverage and the additional deposit option. Wrong split, wrong tool.
Built for death benefit: higher base coverage, slower early cash value. Strong estate tool. Poor infinite banking chassis.
Built for early cash value: minimum base, maximized deposit option, dividends buying paid-up additions. This is the design infinite banking actually needs, and it shares the same core whole life benefits either way.
Funding level matters as much as the product. Later in this guide the same insurer’s policy crosses break-even in year 4 when max-funded, year 9 at a lower funding level, and far later on a base-only design. Same product family. Three different outcomes. None of those timelines are guaranteed, they depend on the dividend scale, but the gap between the designs is the point.
What Type of Whole Life Policy Does Infinite Banking Require?
Infinite banking requires a participating whole life policy. No exceptions. Whole life is permanent coverage that lasts your entire lifetime, and it comes in two flavours.
Dividends are not guaranteed, and that needs saying plainly. But the track record at the major Canadian par carriers is long. Canada Life, founded in 1847 as Canada’s first domestic life insurer, has paid participating policyholder dividends every year since 1848. Through wars, depressions, and the entire low-rate decade, the big par accounts kept paying, with dividend scale rates that held around the 6 percent range through years when GICs paid next to nothing. Past results, not a promise. Still worth knowing.
What Are the Dividend Options?
Your dividend option decides what the policy does with each dividend, and for infinite banking only one of the four choices makes sense.
The one infinite banking uses
Paid-up additions. Each dividend buys a small block of fully paid permanent coverage. That block carries its own cash value and earns its own dividends, which buy more coverage, which earns more dividends. More cash value means more borrowing room later. This is the compounding engine.
The other three options exist, and I steer infinite banking clients away from all of them.
Premium reduction shrinks your out-of-pocket premium. Comfortable, but it starves the cash value growth you set the policy up for in the first place.
Cash payment sends the dividend to you directly. Taking the money out defeats the compounding, and depending on the policy’s tax position a cash dividend can have tax consequences where paid-up additions would not.
Enhanced coverage points the dividend at a bigger death benefit. Fine if the estate is the priority. For infinite banking it pulls fuel away from cash value, and cash value dictates how much you can borrow.
Availability and mechanics vary by insurer and by product, so confirm the options on the specific policy you are looking at. For the wider picture of how participating whole life compares to other permanent designs, this guide to the types of life insurance in Canada covers it.
How Infinite Banking Works in Canada
Infinite banking works by max funding a participating whole life policy so the cash value builds as fast as the rules allow, then using that cash value as collateral whenever you need capital. You own the policy, you are the insured, and the borrowing decision is entirely yours.
The structure is where it is won or lost. Every dollar you commit each year gets split two ways, and the split is the design decision that separates a real infinite banking policy from an ordinary whole life policy.
Your annual deposit
$50,000
(real illustration design, deposits for 20 years)
↓
Base premium: $19,491
Kept as small as the design allows. Pays for the permanent coverage itself and the guaranteed cash value schedule in the contract.
Additional deposit option: $30,509
Maximized to the policy limit. This extra money buys paid-up coverage immediately, which is what front-loads the cash value in the early years.
↓
One policy, two engines running. Guaranteed cash value builds on schedule while dividends buy more paid-up coverage on top, and each new block earns its own dividends. The death benefit grows alongside the whole way. Borrow against the cash value or leave it compounding, your call either way.
That split is from a real Manulife Par illustration for a male 45 non-smoker, roughly 40 percent base and 60 percent deposit option. I ran the identical setup, same client, same $50,000 a year, at four Canadian insurers. The figures below and throughout this guide are examples using current dividend scales, not guarantees or recommendations for a specific carrier. Here is what the same money produces:
Manulife Par
Cash value, year 10
$588,756
Death benefit, year 1
$1,038,352
Cash value passes deposits: year 4-5
Canada Life Wealth Achiever
Cash value, year 10
$577,580
Death benefit, year 1
$882,924
Cash value passes deposits: year 4
Sun Par Accumulator II
Cash value, year 10
$605,535
Death benefit, year 1
$926,315
Cash value passes deposits: year 5
RBC Growth Insurance Plus
Cash value, year 10
$637,003
Death benefit, year 1
$912,558
Cash value passes deposits: year 4
Four real examples of the same setup: male 45 non-smoker, $50,000 per year, minimum base plus maximized deposit option, deposits for 20 years, paid-up additions dividend option. Values use each insurer’s current dividend scale. Dividends are not guaranteed and actual values will vary. These are examples, not a ranking; insurer illustrations cannot be compared on non-guaranteed values.
Notice these are not estimates or industry averages. Cash value sitting between $577,000 and $637,000 at year 10 on $500,000 deposited, with seven-figure death benefits from day one. The full year-by-year breakdown for all four, out to year 50, is in the illustration walkthrough below.
The growth inside the policy is tax-sheltered while it stays in the policy, and accessing it through loans has its own tax rules covered later in this guide. If you want the broader rules first, here is how life insurance is taxed in Canada.
The Pros of Infinite Banking in Canada
The real advantage of infinite banking is capital you control: borrowing capacity that does not depend on a bank’s approval, growing inside a policy that compounds whether you use it or not. Here is what that actually gets you.
01
No qualification to borrow
A policy loan from the insurer needs no credit check, no income verification, no purpose explanation. The cash value is the collateral. Try getting that from a bank after a job change or in a slow business year.
02
The money compounds while borrowed
A loan against the policy is not a withdrawal. The full cash value keeps earning dividends as if nothing left, because nothing did. The loan sits beside the policy, not inside it.
03
Tax-sheltered growth, tax-efficient access
Cash value grows without annual tax inside an exempt policy. Policy loans within the policy’s adjusted cost basis are generally received tax-free, though the rules have edges, covered in the tax section below.
04
The estate piece is built in
This is still life insurance. In the illustrations below, the death benefit runs well into seven figures from year one, many multiples of any loan you would realistically carry. Outstanding loans settle from the death benefit and the rest pays to your beneficiaries tax-free.
05
Repay on your terms, or don’t
No amortization schedule, no penalty for early repayment, no forced payments at all on a policy loan. Interest accrues either way, so discipline matters, but the schedule is yours.
06
Optionality without obligation
Most of my clients don’t borrow until a need or opportunity shows up. Some never do. The policy works as a long-term asset either way, which is exactly why the borrowing flexibility costs you nothing to hold.
One honest caveat before the cons. If all you need is family protection on a budget, this is the wrong tool. Affordable term coverage protects a family for a fraction of the cost. Infinite banking makes sense when the permanent asset itself fits your plan and the borrowing flexibility is a bonus on top.
The Cons of Infinite Banking in Canada
The biggest con of infinite banking is the commitment: the deposits need to be sustainable for years, and the early exit penalty is real. Anyone selling you the upside without walking through these is doing half the job.
It’s a multi-year commitment at any size
The illustrations in this guide use $50,000 a year, but the same structure works at much smaller premiums. What doesn’t scale down is the commitment: whatever the deposit level, it needs to be comfortable for years, not just this year. Smaller policies build smaller cash values, which simply means the borrowing capacity takes longer to become meaningful.
Quitting early costs you
Even max-funded, cash value sits below total deposits for the first 4 to 5 years on current dividend scales. Cancel in year 2 or 3 and you walk away with less than you put in. This is a 10-year-minimum decision, ideally a permanent one.
Loans reduce the death benefit until repaid
Any outstanding loan plus accrued interest is deducted from the payout. With death benefits running 20 to 30 times a typical loan that is rarely a crisis, but a family counting on the full benefit needs to know it shrinks while a loan sits unpaid.
Unmanaged loans can compound against you
No forced repayment schedule cuts both ways. Let interest capitalize for years and the loan can grow toward the cash value, and in extreme cases force a taxable disposition or threaten the policy. Flexibility needs discipline behind it.
Bad setups are common
I see policies sold as infinite banking with high base premiums, enhanced coverage dividend options, or no deposit option at all. Same premium, a fraction of the early cash value. The structure mistakes are quiet and expensive, which is exactly why the setup matters more than the brand on the policy.
None of these kill the strategy for the right client. They define who the right client is: surplus cash flow the deposit fits inside comfortably, a long horizon, and the discipline to treat loans as loans. The deposit option can also start smaller and scale up later if the room is built into the design from day one.
How to Set Up an Infinite Banking Policy in Canada
Setting up an infinite banking policy comes down to four design decisions made before the application ever goes in: the insurer, the base-to-deposit split, the dividend option, and the funding schedule. Get those right and the policy runs itself. Here is the sequence:
STEP 1
Pick the right participating product
Most insurers offer two versions of participating whole life: one tuned for early cash value (often the wealth or accumulator version) and one tuned for long-term death benefit (the estate version). Infinite banking wants the early cash value version, every time.
STEP 2
Minimize base, maximize the deposit option
The proper structure is max deposit-option funding to generate as much cash value as possible. The only reason to leave room below the maximum is a planned future event, like a business sale, where you want capacity to add more later. Build that room in deliberately or not at all.
STEP 3
Set dividends to paid-up additions
Covered above, and worth repeating because it gets missed on real applications: paid-up additions is the only dividend option that compounds the cash value. Not premium reduction, not cash, not enhanced coverage.
STEP 4
Fund it, let it build, then access on your terms
Deposits run on schedule while the cash value compounds. On the max-funded designs in this guide, cash value passes total deposits around year 4 to 5 on current dividend scales. Borrow when a need or opportunity shows up, or let it grow. At death, any outstanding loan settles from the death benefit and the remainder pays tax-free to your beneficiaries.
Which Insurance Companies Fit Infinite Banking?
The carriers I actually place this business with are the major participating accounts: Manulife (Manulife Par), Sun Life (the Sun Par line), Canada Life (the Achiever line), Empire Life (EstateMax and OptimaWealth), and RBC (Growth Insurance and Growth Insurance Plus). One detail on RBC worth knowing: Growth Insurance Plus is the version built for early cash value, while base Growth Insurance builds later. Same company, different tools.
Desjardins and Industrial Alliance technically offer participating whole life too. In 25 years I have almost never placed infinite banking business there, and the illustrations explain why.
Product names and features change, and the right fit depends on your age, health, and how the underwriting lands at each company. A conversation with a broker who runs these illustrations side by side is the fastest way to see which account fits your numbers.
Real Infinite Banking Examples: Four Carrier Illustrations
I ran the exact same infinite banking setup at four Canadian insurers so you can see what the strategy actually produces, not what a marketing deck claims. Same client every time: male, 45, non-smoker, standard rates. Same money: $50,000 a year for 20 years, then deposits stop. Same structure: minimum base coverage, maximized additional deposit option, dividends buying paid-up additions. These are real illustrations run this year, printed values only.
One thing before the numbers. These are four examples of the same setup, not a ranking. Every insurer’s illustration carries the same warning: non-guaranteed values cannot be compared across companies, because each dividend scale is built differently. What the four examples show together is the shape of the strategy. Where one company lands a few thousand higher or lower in a given year tells you almost nothing about which policy you should own.
Total cash value by policy year
Same dollars in every illustration. Deposits stop at year 20; everything after that is the policy compounding on its own.
Swipe sideways on mobile to see all four carriers →
| Year | Manulife Par | Canada Life Wealth Achiever | Sun Par Accumulator II | RBC Growth Insurance Plus |
|---|---|---|---|---|
| 1 $50k in | $46,246 | $44,798 | $43,282 | $45,469 |
| 5 $250k in, break-even | $252,647 | $258,470 | $253,426 | $265,890 |
| 10 $500k in | $588,756 | $577,580 | $605,535 | $637,003 |
| 20 $1M in, deposits stop | $1,622,302 | $1,446,986 | $1,596,718 | $1,687,437 |
| 30 10 yrs, no deposits | $2,656,324 | $2,382,924 | $2,568,990 | $2,821,069 |
| 50 30 yrs, no deposits | $6,138,869 | $5,813,501 | $6,040,007 | $7,580,109 |
Male 45 non-smoker, $50,000/year, minimum base plus maximized deposit option, deposits years 1-20, paid-up additions. Current dividend scale; dividends are not guaranteed and values will vary. Premium offset illustrated from year 21 is not guaranteed and depends on the dividend scale. Examples, not a ranking.
Read the year 5 row again. Roughly $250,000 deposited, and all four policies sit at or above $252,000 in cash value. That is the break-even story, and it is the number that separates a properly structured policy from everything else sold under this label:
Manulife
Year 4-5
CV passes deposits
Canada Life
Year 4
CV passes deposits
Sun Life
Year 5
CV passes deposits
RBC
Year 4
CV passes deposits
Now the part nobody shows you: funding level changes that break-even more than carrier choice does. I have a Manulife illustration on file for the same product at $25,000 a year instead of $50,000, and the crossover moves from year 4 to year 9. A base-funded policy with no deposit option at all builds guaranteed cash value of a few hundred dollars in year 1 and takes decades to catch its deposits. You will hear that whole life is “terrible for the first 17 to 20 years.” That is a base-funded story. Maximize the deposit option and the math above is what happens instead.
Total death benefit by policy year
Swipe sideways on mobile to see all four carriers →
| Year | Manulife Par | Canada Life Wealth Achiever | Sun Par Accumulator II | RBC Growth Insurance Plus |
|---|---|---|---|---|
| 1 | $1,038,352 | $882,924 | $926,315 | $912,558 |
| 10 | $2,121,160 | $1,816,817 | $1,887,167 | $1,990,066 |
| 20 | $3,528,542 | $2,895,014 | $3,094,743 | $3,338,039 |
| 30 | $4,263,679 | $3,527,730 | $3,792,160 | $4,268,603 |
| 50 | $6,755,685 | $6,319,073 | $6,665,506 | $8,452,372 |
Same setup and disclosures as the cash value table. Current dividend scale, not guaranteed, values will vary. Examples, not a ranking.
Two things the death benefit table tells you. First, the estate side of this strategy is not a footnote: every design starts near or above a million dollars of permanent coverage in year 1 and grows from there. Second, deposits stopped at year 20 in every example, and both the cash value and death benefit keep climbing for the next 30 years on the illustrated scale. The premium offset, where the policy carries its own premium from dividends, is illustrated from year 21 and is itself not guaranteed, but the structure is built for exactly that handoff.
Running these four illustrations side by side for your own age, health, and deposit level is a 20-minute exercise with the right access, and it answers more than any article can. Get in touch and I will run the real numbers for your situation before you commit to anything.
Policy Loans vs Bank Loans: Which Way to Borrow?
I have had multiple cases where bank loans were more attractive than the policy loan, simply from a rate of interest perspective. That surprises people, because infinite banking gets taught as borrow-from-the-policy, period. In practice there are two ways to access the cash value, and the right one depends mostly on how much you are borrowing.
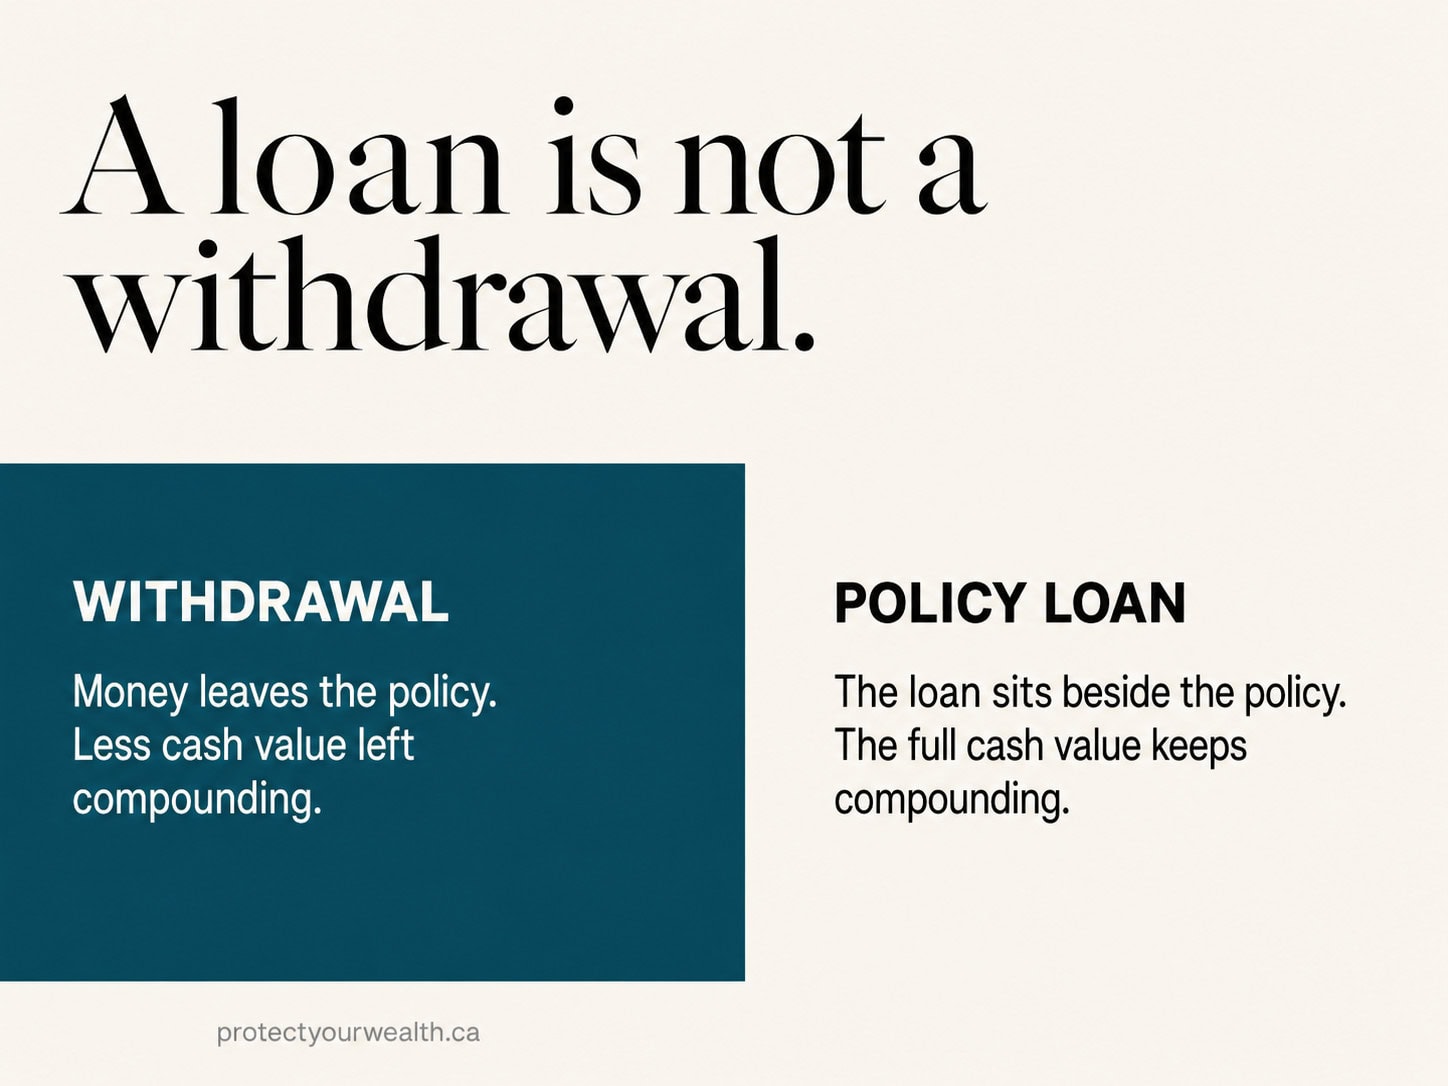
Both paths share the feature that makes this strategy work: the cash value stays in the policy, untouched and compounding, while the loan sits beside it as a separate balance. You are borrowing against the policy, not out of it. A loan is not a withdrawal.
So my positioning is the opposite of the packaged-program script: the policy loan is the convenience tool, the bank loan is usually the cost tool. Small and quick, use the insurer. Large and long, shop the rate. Rates change constantly and your numbers depend on the lender, the amount, and your file, so treat the $25,000 line as a rule of thumb, not a law.
Either way the loan eventually settles, on your schedule or from the death benefit, which in these designs runs 20 to 30 times the size of a typical loan. The borrowing capacity sits on top of everything else the policy already does, which is exactly why the benefits of whole life insurance hold up with or without the loans.
Risks and Limitations of Infinite Banking in Canada
The risks of infinite banking come from three directions: the dividend scale, the loan, and the policyholder. The cons section above covered the commitment side. These are the mechanical risks that live inside the strategy itself, and each one has a management answer.
Dividend scale risk
Every non-guaranteed number in this guide moves with the insurer’s dividend scale, and scales get adjusted. The management answer: the guaranteed cash value schedule in the contract is the floor, dividends once paid are vested and cannot be taken back, and the long par account track records exist for a reason. Plan on the guarantees, and treat the illustrated scale as one possible path, not a promise.
Interest rate risk
Loan rates float. A bank line of credit that looked cheap can reprice, and insurer policy loan rates adjust too. If you carry a balance for years, the borrowing cost is a moving number. The management answer: shop both paths before borrowing, revisit the rate annually on any standing balance, and remember repayment is always allowed without penalty on a policy loan.
Lapse risk
Stop paying premiums before the policy can carry itself and coverage can lapse, which unwinds everything including the tax shelter. The management answer is in the design: in the illustrations above, dividends are projected to cover the premium from year 21 on the current scale. The offset is not guaranteed, so the real protection is funding a policy sized to your cash flow with room to spare.
Over-borrowing risk
Let a loan plus capitalizing interest grow toward the cash value and the policy can be forced into a taxable position or, in the extreme, collapse. The management answer: keep the loan balance well inside the cash value, monitor it yearly like any other liability, and treat the no-payments-required feature as flexibility, not free money.
Tax boundary risk
Policy loans are generally tax-free only up to the policy’s adjusted cost basis, a line that moves every year and that most owners never check. Cross it unknowingly and part of the loan becomes taxable income. The management answer: have the boundary checked before any large loan, not after. The tax section below covers how this works.
None of these are reasons to avoid the strategy. They are reasons to run it with someone watching the dials. The packaged programs sell the borrowing as the whole point; the risks above are why I treat the borrowing as the optional layer on a policy that has to stand on its own first.
Is Infinite Banking Legit or a Scam?
Infinite banking is a legitimate strategy built on a participating whole life insurance policy, not a scam. The policy is a real contract with a regulated Canadian insurer, the cash value is real, the loans are real, and the numbers in the illustrations above came off real carrier software. The concept was developed by Nelson Nash in the United States and has been implemented in Canada for decades, built on participating whole life policies that have paid dividends through every market cycle in living memory.
It is a concept, not a product: what actually gets purchased is a participating whole life policy from a licensed Canadian insurer, arranged through a licensed life insurance broker. The skepticism people bring to it usually comes from somewhere real, though. When someone calls infinite banking a scam, what they almost always encountered is one of three things:
A policy structured wrong
High base premium, no deposit option, wrong dividend election. Same annual cost, a fraction of the early cash value. The owner waits years for borrowing capacity that a proper structure would have built by year 4 or 5.
Projections sold as promises
Dividends are not guaranteed, and any presentation that skips that sentence sets the owner up for disappointment. The guaranteed column in the illustration is the floor; the rest is the current scale.
A strategy that didn’t fit
Sold to someone whose cash flow couldn’t sustain the deposits, who then surrendered early at a loss. The right strategy for the wrong situation produces the same bad story as a bad strategy.
All three are implementation problems, not concept problems. And every one of them is visible in the illustration before you sign anything: the base-to-deposit split, the dividend option, the guaranteed column, the deposit schedule against your actual cash flow. That is exactly the review I walk clients through before any application goes in.
So the honest answer: a legitimate strategy, real contracts, long dividend track records at the major participating carriers, and an outcome that depends almost entirely on getting the structure and the fit right. Both of those are checkable upfront, which is more than you can say for most financial strategies.
Tax Advantages of Infinite Banking in Canada
The core tax advantage of infinite banking is that cash value grows inside an exempt life insurance policy without annual taxation, and policy loans within the policy’s adjusted cost basis are generally received tax-free. Compare that to a non-registered investment account, where growth gets taxed every year as interest, dividends, or capital gains, and the appeal is obvious. The whole strategy lives inside one of the few remaining tax-sheltered structures in Canada that has no contribution limit tied to your RRSP or TFSA room.
Four tax features do the work:
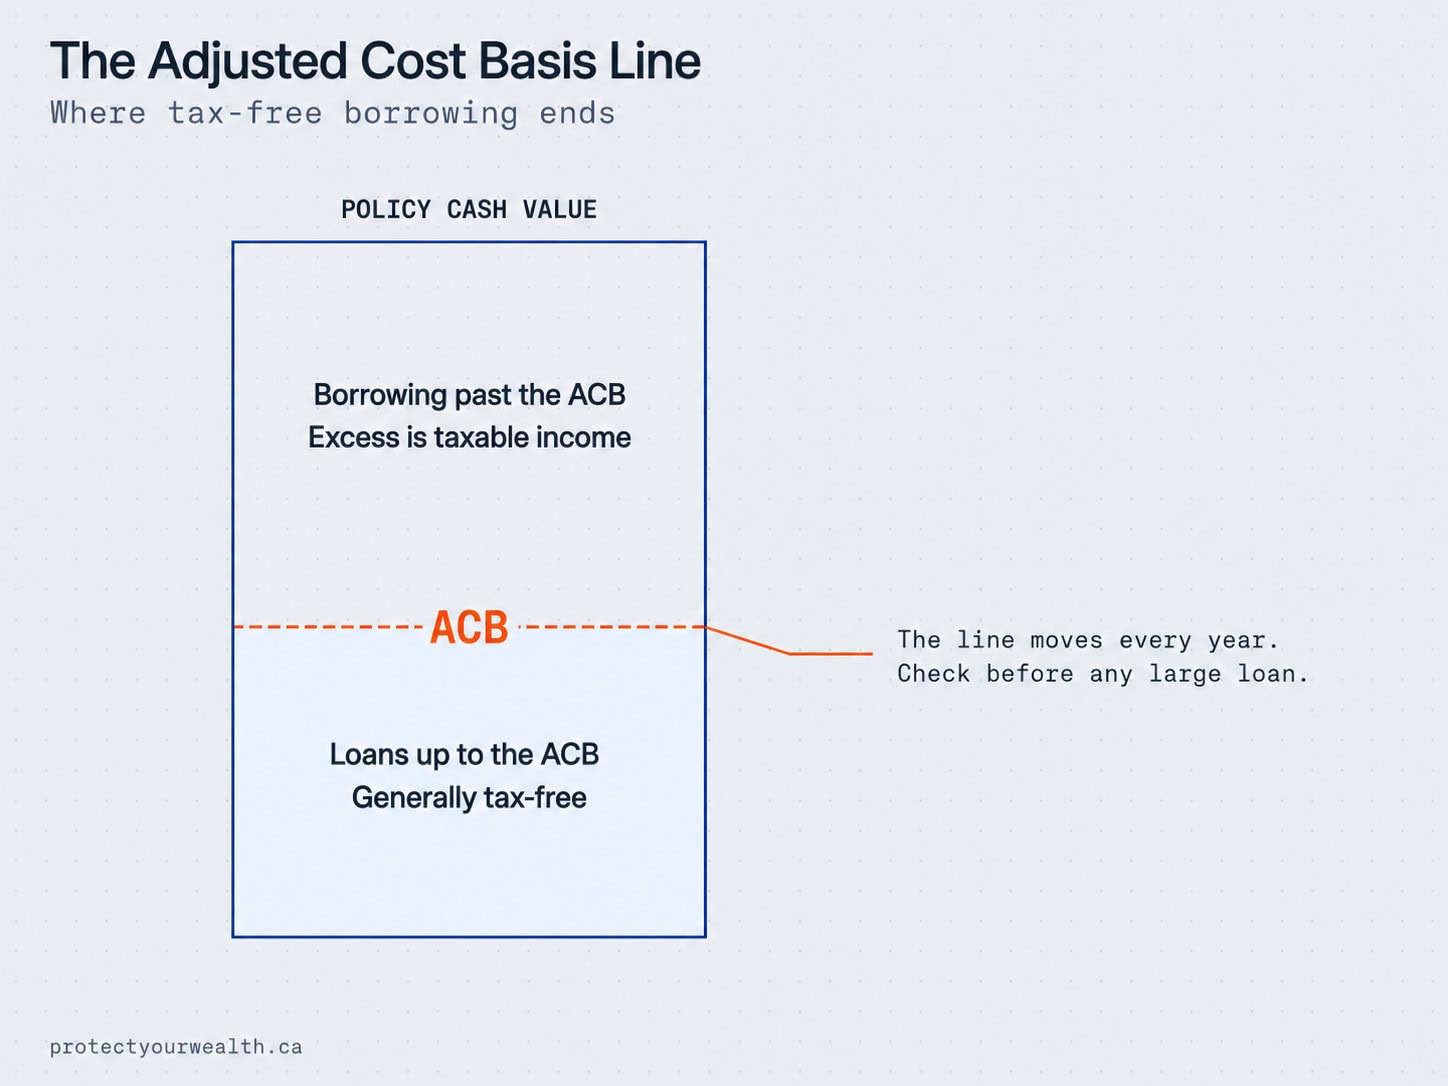
The boundaries are as important as the benefits. Withdrawals (as opposed to loans) above the adjusted cost basis are taxable. Surrendering the policy can trigger a gain. An unmanaged loan that forces a disposition can create taxable income at the worst possible time. None of these happen by accident in a monitored policy; all of them happen in abandoned ones.
Tax rules change, and how they land depends on your situation, so treat this as the map, not the route. The fuller picture of when policies, payouts, and withdrawals are taxed is in this guide on whether life insurance is taxable in Canada, and your accountant should be in the loop on any borrowing plan that touches deductibility.
Corporate Infinite Banking: Using Retained Earnings
Corporate-owned participating whole life can make a lot of sense when there is a corporation with sustained retained earnings beyond operating needs. It’s corporate money versus personal money: funding the policy with dollars that were only taxed at the corporate rate, instead of paying yourself first and funding it with after-tax personal dollars. For an incorporated business owner or professional, that difference alone can change the math more than any carrier choice.
The structure rules are strict, and this is where I see the mistakes. The corporation should be the owner, the beneficiary, and the payor of the policy. Get any of those three wrong and you create tax problems that are expensive to unwind. And one expectation to set straight from the start: the premiums are generally not tax-deductible. This is not a write-off. The policy is an asset on the corporate balance sheet, the same way a corporate investment account is, except it grows tax-sheltered inside the exempt policy rules.
Here is the same strategy from the illustration section, run as a corporate design. Real Manulife Par illustration: $100,000 a year of corporate retained earnings for 10 years, then nothing.
Corporate design: $100,000/year, deposits years 1-10 only
Total deposited: $1,000,000. Zero deposits after year 10. Follow the timeline:
Year 4: break-even
$402,228
cash value vs $400,000 deposited. From this point on, the policy is worth more than every dollar the corporation put in. Cancel-and-lose-money risk is behind you.
Year 10: deposits stop
$1,183,211
cash value vs $1,000,000 deposited. The corporation never writes another cheque. Everything after this row is the policy compounding on its own.
Year 30: zero deposits for 20 years
$3,196,786
cash value has more than tripled the total deposits, with nothing added since year 10. By year 50 it sits at $7.35 million on the illustrated scale.
The whole time: death benefit
$2,086,761
of permanent coverage from year 1, double the total the corporation will ever deposit, growing past $8 million by year 50 on the illustrated scale.
Manulife Par, corporate owned, current dividend scale. Dividends are not guaranteed and values will vary. Example only, not a ranking or a projection of your results.
Why the corporate version works so well: retained earnings sitting in passive corporate investments get taxed hard, in the range of 50 percent on investment income in most provinces, and large passive income can grind down the small business deduction. Moving those dollars into an exempt corporate-owned policy takes that annual tax drag to zero while the corporation keeps the asset on its books. The borrowing layer works the same as the personal version: policy loan from the insurer, or corporate line of credit against the cash value.
There is an estate bonus most owners have never heard of. At death, the death benefit minus the policy’s adjusted cost basis credits the corporation’s capital dividend account, which lets the company pay capital dividends to shareholders tax-free. The mechanics are their own topic, covered in this guide to the capital dividend account and life insurance, and the broader strategy of holding participating whole life inside a corporation is covered in investment-grade participating whole life for Canadian businesses.
The fit test is simple: a corporation with sustained retained earnings beyond operating needs, an owner with a long horizon, and an accountant in the loop from day one. If that is your situation, this version of the strategy is usually stronger than the personal one, and running the corporate illustration against your actual retained earnings takes one conversation
Is Infinite Banking Right for You?
Infinite banking is right for you if three things are true: you have surplus cash flow that can sustain the deposits comfortably for years, your horizon is measured in decades not months, and you want a permanent asset that works whether or not you ever borrow against it. If any of those three are missing, a different tool fits better, and there is no shame in that. Plenty of my clients are better served by term coverage and a boring investment plan.
Strong fit looks like
✓ Steady surplus income or corporate retained earnings beyond operating needs
✓ A 10-year-minimum commitment that does not strain anything else
✓ RRSP and TFSA room already used, or a need for shelter beyond both
✓ Value placed on the permanent death benefit, not just the borrowing
✓ Discipline to treat policy loans as real loans
Wrong fit looks like
✗ The deposit would compete with mortgage payments, debt, or emergency savings
✗ You may need to exit within the first 5 to 7 years
✗ The only goal is affordable family protection (term does that job for far less)
✗ The pitch you received leaned on guaranteed-sounding projections
✗ You would borrow because the system says to, not because a need exists
And if you are on the fence, remember what the illustrations showed: the borrowing is optional. The same max-funded policy that powers infinite banking is simply a strong permanent asset if you never take a loan, and it converts into a retirement income strategy if that becomes the better use later. You are not choosing a lifestyle. You are choosing a structure that keeps your options open.
The honest next step is not a commitment, it is a comparison. Bring your age, your numbers, and your goal, and the illustrations from all the major participating carriers get run side by side for your actual situation. From there the decision usually makes itself.
Get the Real Numbers for Your Situation
At Protect Your Wealth, we have been advising clients on life insurance and segregated fund solutions since 2007. Whether you are comparing participating whole life illustrations or just want a straight answer on whether this strategy fits your situation, we run the numbers across all the major Canadian carriers and walk you through them before you commit to anything.
To schedule a consultation or ask a question, get in touch or call 1-877-654-6119 to talk to a broker directly. We are proudly based in Hamilton and serve clients anywhere in Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, Nova Scotia, and New Brunswick, including areas such as Guelph, Edmonton, and Kelowna.
Frequently Asked Questions About Infinite Banking
Q1
How does infinite banking work?
Infinite banking works by max funding a participating whole life policy so cash value builds quickly, then borrowing against that cash value when you need capital. The policy keeps earning dividends on the full cash value even while a loan is outstanding, and the loan is repaid on your schedule or settled from the death benefit.
Q2
How much money do you need to start infinite banking in Canada?
There is no fixed minimum; the structure works at small premiums and large ones. What matters is that the deposit is sustainable for years and sized so the cash value becomes meaningful borrowing capacity. The illustrations in this guide use $50,000 a year, but the same design principles apply at much lower deposit levels.
Q3
How long does it take before you can borrow against the policy?
You can borrow against cash value as soon as it exists, which in a max-funded design means meaningful capacity in the first year. In the real illustrations above, cash value passes total deposits around year 4 to 5 on current dividend scales, which is the point where the policy is worth more than everything paid in. Dividends are not guaranteed, so timing varies with the scale.
Q4
Do you have to borrow against the policy for the strategy to work?
No. Most of my clients do not borrow unless a need or opportunity shows up, and some never do. The policy works as a tax-sheltered permanent asset either way; the borrowing capacity is flexibility you hold, not an obligation you take on.
Q5
What are the risks of infinite banking?
The main risks are dividend scale changes (the non-guaranteed values move), early surrender (cash value sits below deposits in the first several years), loans reducing the death benefit until repaid, unmanaged loans growing toward the cash value, and borrowing past the policy’s adjusted cost basis, which creates taxable income. Each one is manageable in a monitored policy; the risks and tax sections above cover them in detail.
Q6
What happens if you stop paying premiums?
If the policy cannot carry itself, coverage can lapse and the tax shelter unwinds. In a properly designed policy this risk shrinks over time: the illustrations above project dividends covering the premium from year 21 onward on the current scale. That offset is not guaranteed, which is why the deposit should fit comfortably inside your cash flow from day one.
Q7
Is it better to take a policy loan or a bank loan against the cash value?
As a rule of thumb, the insurer’s policy loan wins for smaller amounts, roughly $25,000 and under, because it is fast and requires no qualification. For larger balances held longer, a bank loan or line of credit against the cash value almost always wins on rate in my experience. Lenders including Manulife Bank, BMO, Scotiabank, and Equitable Bank lend against whole life cash value.
Q8
Does infinite banking work in Quebec?
Yes, the concept works the same way in Quebec: participating whole life policies, policy loans, and the federal tax treatment of exempt policies all apply across Canada. One transparency note: our brokerage is licensed in Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, Nova Scotia, and New Brunswick, so Quebec residents would need a broker licensed with the AMF in Quebec to place a policy.
Q9
How is infinite banking different from traditional banking?
With traditional borrowing, you apply, a lender decides, and the interest leaves your balance sheet permanently. With infinite banking, the collateral is your own policy’s cash value, qualification is automatic on a policy loan, and the asset backing the loan keeps compounding the whole time. You are not literally a bank, but you control the borrowing decision instead of asking permission for it.
Q10
How do you get started with infinite banking?
Start with illustrations, not applications. A licensed life insurance broker runs the max-funded design at the major participating carriers for your age, health, and deposit level, and you compare the real numbers before committing. The structure to ask for is the one this entire guide describes: minimum base, maximized additional deposit option, paid-up additions.





