 ·

Child Life Insurance in Canada: Is It Worth It?
By Parvesh Benning, Licensed Life Insurance Broker
A licensed broker’s honest take on when insuring a child is genuinely worth it, and when an RESP should come first.
Most general advice online treats life insurance for a child as a simple yes or no question. In practice it depends on your family, your finances, and what you are actually trying to do. This guide walks through how children’s coverage works, what it really costs, the cash value you can expect by age, and the honest case for when it is worth it and when something else should come first.
Updated: June 24, 2026
Child Life Insurance in Canada: Is It Worth It?
By Parvesh Benning, Licensed Life Insurance Broker, Updated: June 24, 2026
A licensed broker’s honest take on when insuring a child is genuinely worth it, and when an RESP should come first.
Most general advice online treats life insurance for a child as a simple yes or no question. In practice it depends on your family, your finances, and what you are actually trying to do. This guide walks through how children’s coverage works, what it really costs, the cash value you can expect by age, and the honest case for when it is worth it and when something else should come first.
General advice on the internet is exactly that. It does not apply across the board to everyone, and insuring a child is a perfect example: the right answer for one family is the wrong answer for another. Whether it makes sense comes down to your finances, your family health history, and what you are actually trying to accomplish, not a blanket rule from a forum thread.
Is child life insurance worth it? Sometimes, and only when it fits your situation.
For most families it works as a complement to other savings, not a replacement. It earns its place when you want to lock in a child’s future insurability, or build a tax-sheltered asset in their name that an RESP or a non-registered account cannot match. It is the wrong first move if your own protection and emergency savings are not in place yet.
Often worth it when: there is a family health history, your own coverage is already handled, and you want permanent coverage or a long-term asset for the child.
Usually wait when: you still need parent life and disability coverage, an emergency fund, or RESP room first.
What this guide covers
- What children’s life insurance actually is
- Why parents buy it (the real reasons)
- How a child’s policy works
- What we check before applying
- The types of coverage available
- Real cash value and death benefit by age
- Child life insurance vs an RESP
- Transferring the policy to your child, and the tax
- Pros, cons, and when to wait
- Which Canadian carriers offer children’s coverage
- Which type fits your goal as a parent
- Frequently asked questions
Why Parents Actually Buy Life Insurance for a Child
Most parents buy it for one real reason: to lock in a child’s future ability to get insured, before any health issue ever shows up. Everything else is secondary to that. A healthy child today usually has several coverage options. The same child at 30 with a diagnosis on file may have far fewer, or may pay more for the same coverage.
I will be straight about my own position here. I own these policies on my own children. I believe in these solutions, it is not something I just recommend, it made sense for me and my family. So when I lay out the reasons below, that is where I am coming from.
What I would not do is sell you on the idea that a child “needs” life insurance. They do not, not the way you do. This is planning, not protection of an income. Real reasons, real situations, and it has to fit yours.
How a Child’s Life Insurance Policy Works
A child’s policy works much like an adult’s, with a few twists: the parent owns it and pays it, premiums are locked in at the child’s young age, and on permanent plans part of each payment builds cash value the child can tap later. The child is the life insured the whole time. You are the one holding the wheel until you decide to pass it over.
Premiums
Set by the child’s age at issue, so buying young locks in a low rate. Permanent plans often let you pay for a limited window, say 20 years, then the coverage is paid up for life.
Coverage amount
There is not one universal ceiling across all insurers. A small standalone plan can start in the tens of thousands, while a permanent policy funded as a long-term asset can carry a death benefit into the hundreds of thousands. Higher amounts still have to be justified and approved by the insurer. The illustrations further down start above $100,000.
Cash value
Permanent plans only. Part of each premium builds value inside the policy that grows tax-sheltered and can later be borrowed against or withdrawn. Term coverage has none.
Transfer to the child
At the age of majority you can hand ownership to the grown child, often on a tax-deferred basis. You stay in control until then, and can keep control even after if you set it up that way.
One mechanic people miss is the beneficiary side. While you own it, you are usually the beneficiary if the worst happened to the child. And if you ever name a minor as a beneficiary on any policy, do it through a trustee, otherwise the courts can end up managing the money. I have watched that play out, and it is a slow, messy process you can avoid with one line on the application. That is its own topic, covered in our guide on beneficiaries versus wills.
Application is usually light. Kids are generally healthy, so most plans ask a short set of health questions and skip the medical exam. Many straightforward child applications can be issued relatively quickly.
What We Check Before Applying for Child Life Insurance
Before I submit a single child application, I run through a short list that tells me which carrier to approach and whether to prescreen first. This is the part that separates a broker from a quote form. Get the order wrong, or send a borderline file to the wrong insurer cold, and a decline can follow that child around for years. So we do the homework first.
When a file has any of these flags, I prescreen with the underwriter before putting the child’s name on a formal application. That is an anonymous check on the specifics, no name attached, so we learn the likely outcome without leaving a mark on record. If the answer is good, we apply with confidence. If it is not, we adjust the plan instead of collecting a decline. That single step is the difference between coverage and a problem, and it is exactly why running a child’s application through a broker beats going direct. If your child has any history worth talking through, get in touch before you apply, not after.
The Types of Child Life Insurance Coverage in Canada
There are two families of child coverage in Canada: permanent and term. For children, permanent does the heavy lifting, because it stays in force for life and builds cash value. Term, for a kid, is usually just a rider tacked onto a parent’s policy. So let me take them permanent-first, because that is the order they actually get bought in.
Permanent
Whole life and universal life. Never expires, builds cash value, locks in a lifetime rate at a child’s age.
Term
Usually a child rider on a parent’s policy. Cheap, temporary, no cash value. A few carriers issue standalone child term.
Whole Life and Universal Life for Children (Permanent Coverage)
Permanent coverage on a child means the policy never expires and builds a pot of cash value alongside the death benefit. Two flavours here. Whole life, where the insurer manages the growth and a participating plan pays dividends. And universal life, where you get more say in how the money inside is invested. Both lock in lifelong coverage at a child’s rate, which is the entire appeal.
This is where the long-term asset idea lives. Cash value grows tax-sheltered inside the policy, and the grown child can later borrow against it or draw on it for a first car, tuition, a down payment. The three real illustrations further down are all permanent plans, so you see actual numbers, not theory. For the full mechanics, here is our guide to permanent life insurance in Canada.
Term Coverage and Child Term Riders
Term coverage on a child is almost always a child term rider: a small add-on to a parent’s existing policy that covers every kid in the household for one modest flat cost. It is cheap, it carries no cash value, and it usually converts to a small permanent policy later without a medical. Useful, but it is an add-on, not a standalone asset.
The reason standalone term is so rare on a child comes down to insurable interest. A child has no income to replace, so most carriers will only write permanent coverage (whole life or universal life) on a kid, not term. Of the top 20 carriers in Canada, only a small number will issue a true term policy on a child at all.
Here is the exception most people do not know. A few carriers issue a genuine standalone level term policy on a child, in the child’s own name. Desjardins is the clearest example, with Term 20, 25, and 30 written directly on the child. For a child age 5, non-smoker, $100,000 of coverage, a Desjardins Term 20 runs roughly $10 to $11 a month. Illustrative only, and worth weighing against a rider before you commit. Our term life insurance page covers how level term works in general.
There is also critical illness coverage for children, a separate product that pays out if a child is diagnosed with a covered serious illness. Some permanent plans bundle a no-cost child critical illness benefit in (Beneva does this). It is its own topic, handled on our critical illness page.
Child Life Insurance vs an RESP: Which Comes First
An RESP almost always comes first, and I will say that plainly even though I sell the insurance. For education savings, nothing beats the government match. The RESP pays a 20% grant on the first $2,500 you contribute each year, up to a $7,200 lifetime grant per child. That is free money. A life insurance policy does not do that, and any broker who tells you otherwise is steering you wrong.
So these two are not rivals. They do different jobs. The RESP is the education tool. The permanent policy is a tax-sheltered asset that does things an RESP legally cannot.
Where the RESP wins
The 20% grant is unbeatable for education. Up to $7,200 in grant money per child, plus tax-deferred growth, with a $50,000 lifetime contribution limit.
If the money is for school, this is the first dollar you should be saving.
Where the policy wins
No contribution cap that matters here, no requirement to spend it on school, and the value sits in a tax-sheltered place in the child’s name.
It also locks in the child’s insurability for life, which no savings account can do.
Here is the nuance most people get wrong, and it matters. A child can absolutely hold index funds inside an RESP, that is fine and normal. What gets you in trouble is a standalone non-registered investment in the child’s name. The income on that gets attributed back to you, the parent, and taxed in your hands. That attribution rule is exactly the gap a permanent policy fills: cash value grows tax-sheltered inside the policy, in the child’s name, without that attribution problem and beyond what the RESP will hold.
The way I frame it for families: max the RESP first for the grant, then if you still have money you want to set aside for the child and you have hit the limits or want something outside the education box, that is where the permanent policy earns its place. One funds school. The other builds a long-term, tax-sheltered asset they keep for life. For the full mechanics of the education side, here is our guide to RESPs in Canada.
Transferring the Policy to Your Child, and the Tax
You can transfer a child’s policy to them once they reach the age of majority, and in most cases it happens with no tax triggered at the moment of transfer.
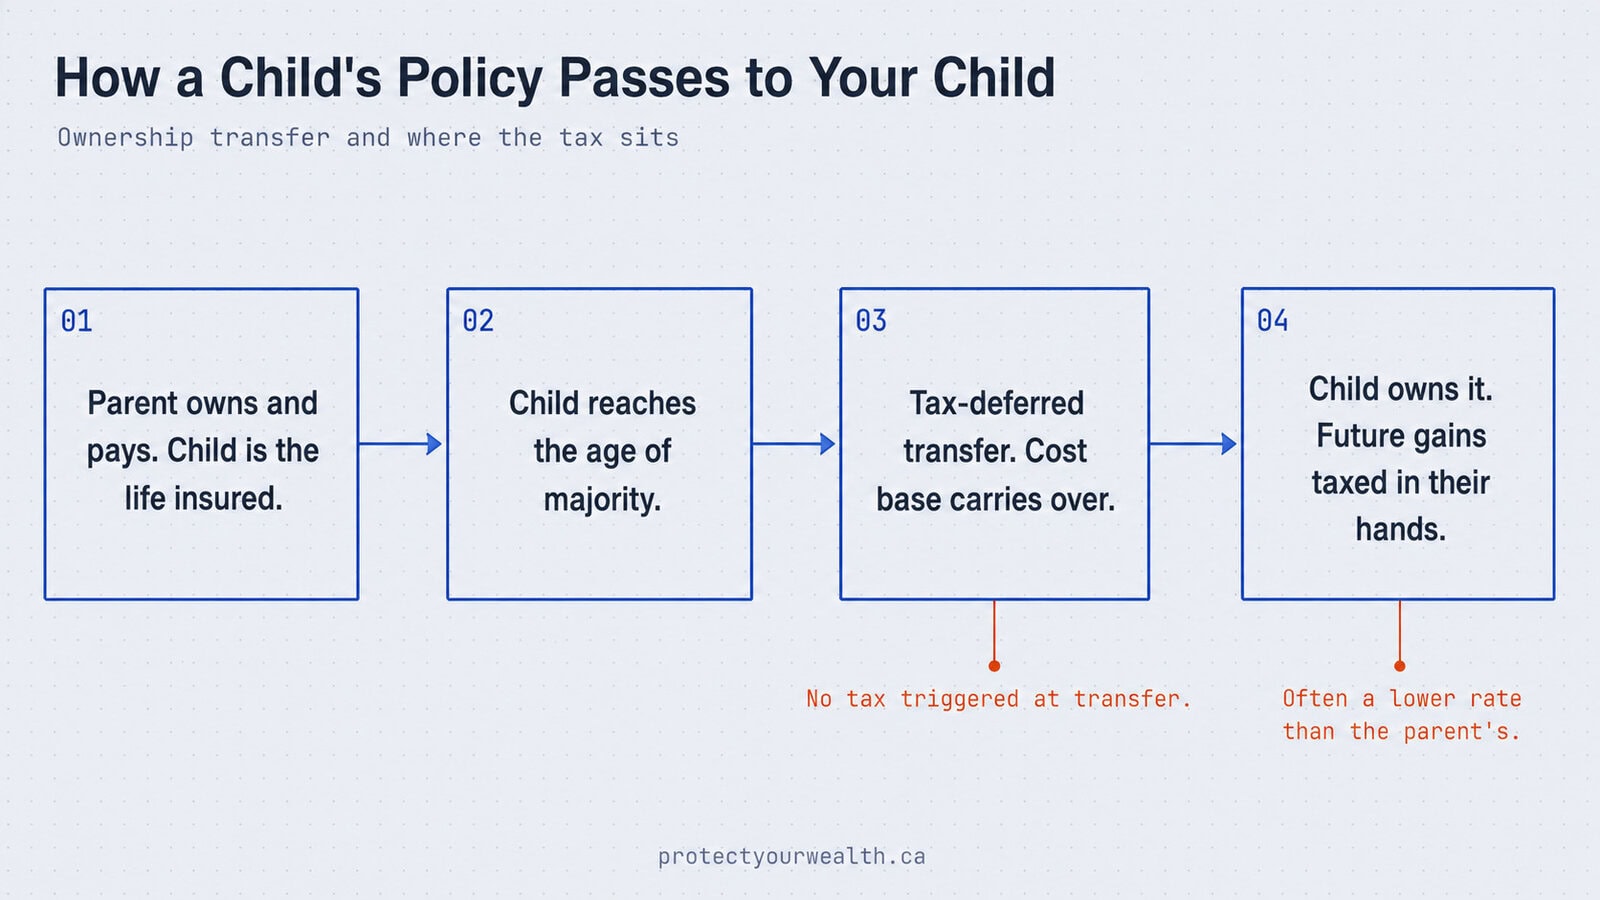
The Income Tax Act lets a parent roll a policy to a child on a tax-deferred basis when the child is the life insured. The cost base carries over, the gain is not crystallized on the handover, and the child picks up the policy where you left off.
The part people miss
Tax-deferred does not mean tax-free forever. It means the bill moves with the policy. Once your child owns it, any future taxable event (a withdrawal, a surrender, a policy loan that triggers a gain) is taxed in their hands, at their rate. For a young adult just starting out, that rate is usually lower than yours, which is part of why the transfer is worth planning around rather than rushing.
Attribution applies to income, not to the policy’s own growth on transfer. That is a different animal from the non-registered investment trap covered earlier.
Timing on the age of majority varies by province. It is 18 in most of the provinces where we are licensed, and 19 in British Columbia, New Brunswick, and Nova Scotia. You do not have to transfer the second they hit that age. A lot of parents keep ownership well into the child’s twenties and hand it over around a real milestone, a wedding, a first home, the birth of their own kid. You stay in control until you decide otherwise.
Here is what I tell families: do not treat the transfer as a paperwork afterthought. The whole reason you started a policy this early was to hand your child a built-up, tax-sheltered asset in their name. Plan the handover, do not just trip into it. If you want the bigger picture on passing assets cleanly, our guide on beneficiaries versus wills covers the estate side.
Pros, Cons, and When to Wait
The honest version: child life insurance is a strong move in the right situation and the wrong first move in plenty of others. Here is the case on both sides, laid out the way I would tell a parent across my desk.
The real upsides
- Locks in lifelong insurability at a child’s health, before anything can show up on a file.
- Premiums set at a child’s age, the cheapest that coverage will ever be.
- Builds a tax-sheltered asset in the child’s name, beyond what an RESP holds.
- Some plans let the grown child buy more later with no medical.
- Can be handed over at majority on a tax-deferred basis.
The honest downsides
- Cash value starts slow. This is a decades-long play, not a quick return.
- A child has no income to replace, so it is planning, not protection.
- Money in a policy is money not going to an RESP grant or your own coverage.
- Universal life designs need monitoring so they do not erode in later years.
- Surrender early and you can get back less than you paid in.
When I tell parents to wait
This is the part the sales-first sites skip. There is a clear order of operations, and a child’s policy sits near the end of it, not the front. If the items below are not handled yet, that is where your money should go first.
1. Your own life insurance comes first. If something happens to the earners, that is the catastrophic risk. Cover the parents before the kids, every time.
2. Disability coverage on the income. You are far more likely to be off work from illness or injury than to die young. Protect the paycheque.
3. An emergency fund. Three to six months of expenses in cash. A child’s policy is illiquid for years, it does not fill this job.
4. The RESP, at least to the grant max. Free 20% match beats anything a policy does for education savings. Get that first.
Clear all four and still have money you want to set aside for your child long term? Now a permanent policy makes real sense. That sequence is the honest answer, and it is exactly the kind of thing a broker should tell you even when it means selling you less. If you want to talk through where you actually sit in that order, get in touch and we will map it out.
Which Type Fits Your Goal as a Parent
The fastest way to narrow this down is to start from what you actually want the policy to do, not from a carrier name. Here is roughly where I point parents depending on the goal they walk in with.
If your goal is
Cheapest basic coverage
Start with a child term rider on your own policy. One small flat cost covers every kid in the house.
If your goal is
Standalone term in the child’s name
Look at a Desjardins-style standalone child term policy, one of the few written directly on the child rather than as a rider.
If your goal is
Locking in future insurability
Permanent coverage, ideally one with a guaranteed insurability option so the grown child can add coverage later with no medical.
If your goal is
Steady, predictable cash value
Participating whole life. Slower early, but built to compound for life without much hands-on management.
If your goal is
Largest early death benefit
Universal life can buy far more coverage for the same outlay, as long as you are willing to review it over time.
If your goal is
Coverage despite a medical history
Prescreen before you apply. The wrong first application can follow the child around, so this is where a broker earns their keep.
If your goal is
You are not covered yourself yet
Your own coverage comes first, every time. Protect the income earners before insuring the kids.
None of these are one-size answers, but they tell you where to start looking. The real fit depends on your budget, your family health picture, and how hands-on you want to be. That sorting is most of what I do on a first call.
Which Canadian Carriers Offer Children’s Coverage
Plenty of Canadian carriers write coverage on children, and the right one depends entirely on what you are after: a large early death benefit, the fastest cash value, or a free rider that throws in extra protection. There is no single best company here, only the best fit for your situation, and that is the whole reason to run it through a broker who can compare them side by side rather than calling one insurer and taking what they offer.
Participating whole life through the Achiever lineup. Steady guaranteed values and a strong long-term death benefit, built to set and leave.
Manulife Par with a paid-up additions and deposit option. In the illustrations it built among the strongest mid-life cash values of the three.
Universal life that buys a large early death benefit, plus a free child critical illness benefit and a guaranteed insurability option. Needs monitoring over time.
Sun Par lineup for permanent coverage on a child, with several pay-period designs depending on how fast you want cash value to start.
EstateMax participating whole life plus a child term rider option, a solid mid-market permanent choice.
Writes children’s coverage through whole life with a child term rider, plus the Access Life simplified route in tougher cases.
Whole life with a child term rider, and base whole life that starts building cash value early.
Writes children’s coverage mostly through whole life with a child term rider. Pricing and rider terms worth comparing against the others.
One of the few that issues a standalone level term policy in the child’s own name (Term 20, 25, 30), not just a rider.
Notice that the same $200 a month landed very differently across just three of these carriers earlier in this guide. Multiply that by a dozen companies and you can see why going direct to one insurer is the expensive way to do this. As an independent broker I am not tied to any of them, so I can run your child’s age and your goal across the lineup and show you where it actually lands. Get in touch and I will pull the comparison for your situation.
Frequently Asked Questions
Question 01
Is life insurance for a child actually worth it?
Sometimes, and only when it fits your situation. For most families it works as a complement to other savings, not a replacement. It earns its place when you want to lock in a child’s future insurability or build a tax-sheltered asset in their name. It is the wrong first move if your own life and disability coverage, an emergency fund, or RESP room are not handled yet.
Question 02
How much does child life insurance cost in Canada?
It depends on the type. A standalone child term policy can run about $10 to $11 a month for $100,000 of Term 20 on a young child. The permanent policies in this guide were all illustrated at $200 a month, which is a funding choice, not a fixed price. You can pay less for a smaller permanent policy or more to build cash value faster. Premiums lock in at the child’s age, so younger is cheaper.
Question 03
Should I get an RESP or life insurance for my child first?
RESP first, in almost every case. The RESP pays a 20% government grant on the first $2,500 you contribute each year, up to $7,200 per child. No insurance policy matches that for education savings. A permanent policy comes after the RESP grant is captured, for money you want to set aside outside the education box or beyond the limits.
Question 04
Can I transfer the policy to my child when they grow up?
Yes. You can roll a child’s policy to them at the age of majority, usually with no tax triggered at the moment of transfer. The cost base carries over and any future taxable event is then taxed in the child’s hands, often at a lower rate than yours. You stay in control until you decide to hand it over, and many parents wait until a milestone like a wedding or first home.
Question 05
What is the difference between whole life and universal life for a child?
Whole life is the steadier design: the insurer manages the growth, a participating plan pays dividends, and it is built to set and leave. Universal life gives you more control over the money inside and can buy a much larger early death benefit, but designs using a rising cost of insurance need monitoring so the fund does not erode in later years. Both are permanent and both build cash value.
Question 06
At what age can I buy life insurance for my child?
From birth. Most carriers will issue coverage on a child from about 14 days old up to the late teens. Buying earlier locks in the lowest premium and the longest runway for cash value to compound, which is why many parents start in the first year. The application is usually light, with a short set of health questions and no medical exam.
Find the Right Child Life Insurance Policy in Canada
If you are still weighing whether a policy makes sense for your children, get in touch. A short conversation with a broker can tell you fast whether coverage is the right move for your family, or whether your money is better aimed at an RESP or your own coverage first. No pressure, just a straight answer.
At Protect Your Wealth we compare policies and quotes across more than 20 Canadian carriers so you are not stuck with whatever one company happens to offer. We provide expert life insurance and segregated fund solutions, including no-medical life insurance, critical illness insurance, term life, and permanent life insurance, built into the right package for what your family actually needs.
Contact Protect Your Wealth or call 1-877-654-6119 to talk to a broker directly. We are proudly based in Hamilton and serve clients across Ontario, Alberta, British Columbia, Manitoba, Saskatchewan, New Brunswick, and Nova Scotia.





