 ·

Life Insurance Lapse in Canada: What Happens and How to Fix It
By Parvesh Benning, Licensed Life Insurance Broker
A lapse is not always a missed payment: some policies quietly collapse while the owner still believes they are fully paid up.
When a life insurance policy lapses, the coverage ends and the death benefit ends with it. The lapses that hurt most are the ones nobody saw coming: a permanent policy slowly draining itself, or a term renewal that suddenly costs several times what it did before. Here is how a lapse actually works in Canada, what your options are if it happens, and how to keep one from sneaking up on you.
Updated: June 16, 2026
Life Insurance Lapse in Canada: What Happens and How to Fix It
By Parvesh Benning, Licensed Life Insurance Broker, Updated: June 16, 2026
A lapse is not always a missed payment: some policies quietly collapse while the owner still believes they are fully paid up.
When a life insurance policy lapses, the coverage ends and the death benefit ends with it. The lapses that hurt most are the ones nobody saw coming: a permanent policy slowly draining itself, or a term renewal that suddenly costs several times what it did before. Here is how a lapse actually works in Canada, what your options are if it happens, and how to keep one from sneaking up on you.
Term policies and permanent policies lapse for completely different reasons, and most people only worry about the obvious one: forgetting to pay. The quieter problem is a permanent policy that was never funded to last, slowly draining its own cash value until there is nothing left to draw from. This guide walks through both kinds of lapse, what a grace period actually buys you, whether reinstating beats buying new, and the moves that keep a policy in force.
A life insurance policy lapses when a required premium goes unpaid and the grace period runs out, which ends both the coverage and the death benefit. With a permanent policy, a lapse can also wipe out the cash value you built up inside it.
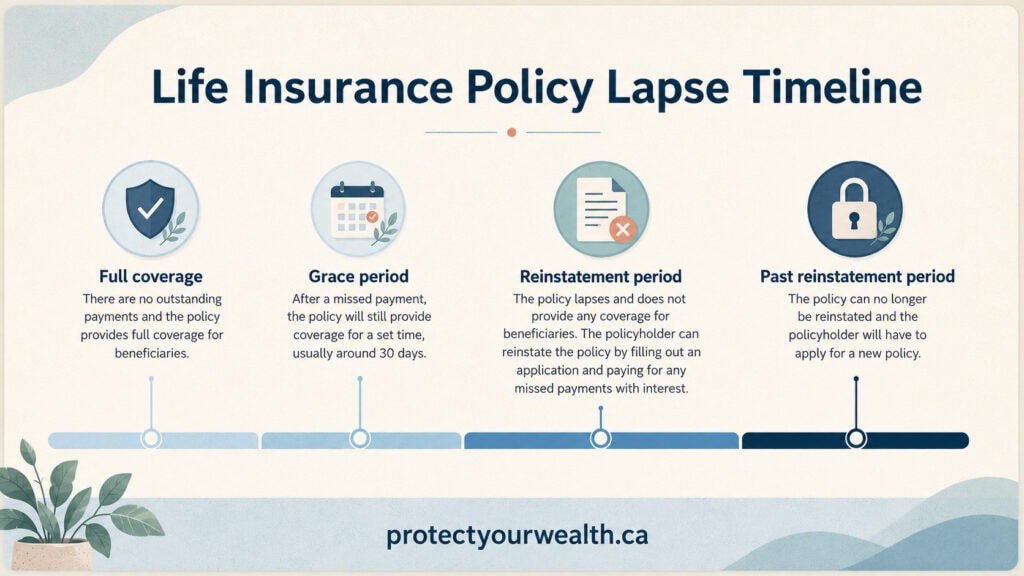
Grace period: about 30 days after a missed payment. Reinstatement: may be available for a limited window after that, depending on the insurer, policy type, timing, and health evidence.
What this guide covers
- What a life insurance lapse actually means
- Why policies lapse in the first place
- The grace period after a missed payment
- Why a permanent policy can lapse when you think it is paid up
- How to avoid a lapse
- How a lapse affects getting covered again
- Reinstating versus reapplying after a lapse
- Can you get money back from a lapsed policy
- Frequently asked questions
What a Life Insurance Lapse Actually Means
A lapse means your coverage has ended because a required premium went unpaid and the grace period ran out. No active policy, no death benefit. If you passed away after that point, your beneficiaries would not receive a payout.
Here is the part people miss. A lapse is not always something you choose or even notice. Term policies usually lapse the obvious way, you stop paying. Permanent policies can lapse a second, quieter way: the policy runs out of internal value to keep itself going. Same word, two very different problems.
Term policy
Lapses when you stop paying the premium and the grace period ends. There is no cash value to lose, but the coverage is simply gone.
Permanent policy
Lapses the same way if you stop paying, but with permanent coverage there is more underneath. A universal life policy can collapse from the inside if it is underfunded. A whole life policy can also run into trouble if premiums, policy loans, or automatic premium features are not managed properly, though the mechanics are different.
With some permanent policies, especially underfunded universal life, a lapse can leave little or no cash value behind, because the policy has been quietly using that value to cover its own internal costs. That underfunding problem is the one I spend the most time fixing, and the one most articles skip entirely. We get into exactly how it happens further down.
Why Policies Lapse in the First Place
The number one reason is renewal shock. A term policy comes up for renewal, and the guaranteed renewal rate can be many times what the market rate is. Insurance companies mitigate their risk by pricing that renewal high, more often than not far above what you would pay shopping fresh.
That does not mean you are stuck. It means you have options, and that is exactly where an independent broker earns their keep. We can compare the renewal against the open market, look at whether converting the policy makes sense, and check what is viable even at an older age. There are usually solutions. You just have to look before the policy quietly renews at the high rate or lapses.
Before you let one lapse: you may be able to lower the coverage amount instead of dropping it entirely. A smaller policy you keep beats a larger one you lose. It is worth exploring before you walk away. Handling a term renewal goes deeper on this.
After renewal shock, the next common one is cost on a fixed income. Ideally the policy was set up to account for retirement years from the start. But we live in an expensive time, things have gotten more expensive, and sometimes a policy lapses because other priorities take over. Coverage for seniors is its own balancing act.
And then there is the plain administrative stuff. A payment that was forgotten. A move where the insurer’s mail never caught up. An automatic payment that failed when a card expired. Less dramatic, but it ends a policy just the same.
The Grace Period After a Missed Payment
A grace period is the window after a missed payment where your policy is still in force, typically around 30 days. Miss the due date and you have not lapsed yet. You still have coverage, and you still have time to make the payment and carry on like nothing happened.
Here is the question people actually worry about: what if someone dies during that window? In my experience I have not come across a client who passed away mid grace period, but the answer is straightforward. If the policy is in force, even inside the grace period, the coverage stays in full effect. A claim would generally be paid, usually with the outstanding premium deducted from the benefit. Your named beneficiary is still protected during that stretch.
One more thing on permanent policies. If you have built up cash value, the policy can sometimes draw on it to cover a missed premium and keep itself going. That can quietly buy you time. It can also quietly drain the policy, which is the trap we get into next.
Why a Permanent Policy Can Lapse When You Think It Is Paid Up
A universal life policy can lapse even while you are paying exactly what you were told to pay, because the cost of insurance inside it was designed to climb every single year. Picture it the way I explain it at the kitchen table.
Say you set the policy up with a hundred dollar monthly premium. In year one the cost of insurance is thirty dollars a month, so seventy goes into the investment side. Fast forward a year: the cost of insurance is now thirty five, and only sixty five goes to investments. Keep going.
The slow bleed, year by year
Year 1: $100 paid. $30 cost of insurance, $70 into investments. Healthy.
Year 10 to 20: cost of insurance is now $110. You are still paying $100. That $10 shortfall gets pulled from the cash value.
Several years later: cost of insurance is $200. Now $100 a month is being eaten out of the cash value every month. The account drains, and when it hits zero the policy lapses unless you put more money in.
That is the slow bleed. The policy was either severely underfunded from the start, or the actual investment return never matched what the original illustration promised. Either way, the cost was designed to rise and the funding could not keep up.
When someone brings me one of these older policies, the first things I check are the premium being paid, the current cash value, and the cost of insurance design: was it a level cost, or was it YRT, yearly renewable term? That last one matters enormously.
I have come across many cases over the years where the client believes they have a level cost premium and does not realize they do not. So the cost of insurance climbs dramatically, the investment component cannot keep up, and the policy is quietly heading for a shock years down the road. To be clear, a YRT design is used all the time and can work very well. It just has to be adequately funded and structured so it does not collapse on you later. How permanent policies are funded is worth understanding if you own one.
If you own a universal life policy you have not looked at in years, do not wait for the statement that says it is about to lapse. Have someone pull the cost of insurance design and the funding before the cash value runs thin. Reviewing your policy regularly is how you catch this in time instead of too late.
How to Avoid a Lapse
Most lapses are preventable with a few habits, and the rest come down to designing the policy right in the first place. Start with the boring stuff that actually works:
Put it on autopay
A pre-authorized payment from your bank account is the single best defence against a forgotten premium. Update the card or account whenever it changes.
Keep your contact info current
If you move, tell your insurer. A lapse notice that never reaches you is one of the quietest ways coverage ends.
Know your premium structure
Understand whether your premium is level or set to rise, especially on permanent policies, so a future increase does not catch you off guard.
Reduce before you drop
If money is tight, ask about lowering the coverage amount or trimming riders you do not need rather than letting the whole policy go.
People ask me about the waiver of premium rider, which covers your premiums if you become disabled. I might recommend it for someone in a high risk job where disability is a real concern. But honestly, my preference is broader. I would rather put adequate disability coverage in place so that if something happens, it is not just your life insurance premium that gets covered, it is your broader expenses too. The rider solves a narrow problem. Proper coverage solves the real one.
How a Lapse Affects Getting Covered Again
Yes, you can still get life insurance after a lapse, but the application gets more involved and the price may move. A new insurer is looking at you fresh, and a few things shape what happens next.
Disclose the lapse
Applications often ask whether you have had a policy lapse. Be straight about it. Leaving it out can complicate or even sink a claim later, which defeats the whole point. Honesty here is what lets the insurer price you properly. Not disclosing is one of the reasons coverage gets declined.
Fresh underwriting
The new insurer reassesses your age, health, and lifestyle. If your health has changed since the original policy, it can affect both your eligibility and your rate.
Premium may rise
A history of lapse, plus being older than when you first applied, can mean a higher rate with a new insurer. How much depends entirely on your situation.
None of this means you are out of options. It means the differences between carriers start to matter a lot, because one insurer may treat your health history very differently than the next. That is the part you cannot see from the outside, and it is exactly what a broker compares for you. If your health has changed, a no-medical policy can be a practical route back to coverage without a full medical workup.
Reinstating Versus Reapplying After a Lapse
If your policy has lapsed, reinstating it is often possible, and the deciding factor for me is cost and how much time is left on the policy. Is it worth resurrecting the old one, or does it make more sense to look at the broad market? Either way, you evaluate and compare. You do not just assume one is better.
Reinstatement means bringing the lapsed policy back to life. Whether it is available, and for how long, depends on the insurer, policy type, timing, and health evidence, commonly a limited window of up to about two years and longer with some carriers. You will usually need to reapply with current health information, repay the missed premiums (often with interest), and if your health has not changed, many insurers will honour the original pricing.
Reinstating often wins when
Your health has not changed, the original rate was locked in at a younger age, and not too much time has passed. Holding the old pricing can beat anything new on the market.
Reapplying often wins when
The lapse went on too long to reinstate, the back premiums plus interest make it expensive, or your situation has changed enough that a simplified or no-medical policy is the cleaner path.
If you ever feel an insurer has handled a reinstatement or claim unfairly, Canada has a free, independent complaint service, the OmbudService for Life and Health Insurance. Worth knowing it exists.
Not sure whether to revive the old policy or start fresh? That is a math problem with real money on both sides, and it is worth getting a second set of eyes on. Talk to a broker directly and we will run the comparison for you.
Can You Get Money Back From a Lapsed Policy
It depends entirely on what kind of policy you had. With a term policy, there is no money to get back. Term has no cash value, so when it lapses, it is simply gone. You paid for coverage during those years, and that is what you got.
A permanent policy is different. If your whole life or universal life policy built up cash value, you may be able to recover some of it, but timing is everything.
One thing to keep in mind. If you surrender a permanent policy and the cash value comes back higher than what you paid in, the gain can be taxable. The rules depend on your specific policy, so this is a conversation to have before you pull the trigger, not after. How life insurance is taxed in Canada covers the general picture, and this is general information, not tax advice.
Frequently Asked Questions
Q1.
How long do I have to reinstate a lapsed life insurance policy?
The reinstatement window varies by insurer, commonly up to about two years and longer with some carriers. During that time you have no coverage, but you can apply to bring the policy back. Check your specific policy with your insurer, since the rules differ from one contract to the next.
Q2.
Will reinstating affect my premium or coverage?
If your health has not changed since the policy was first underwritten, many insurers will honour the original pricing, though you will still owe the missed premiums, often with interest. If your health has changed significantly, you may face a higher rate, reduced coverage, or a declined reinstatement. Reinstatement can ask for current health evidence, similar to a medical exam depending on the insurer.
Q3.
Will a lapse affect my beneficiaries?
During the grace period, beneficiaries are still protected, and a death benefit would generally be paid out (less any owed premium). Once the policy lapses and the grace period has ended, the coverage is gone and beneficiaries would not receive a payout if the insured passed away.
Q4.
Can you get money back from a lapsed life insurance policy?
Only if it was a permanent policy with cash value. Term policies have no cash value, so nothing comes back. A permanent policy may return its cash surrender value (cash value minus any charges or loans), though a policy that lapsed from underfunding may have little left.
Q5.
Can a universal life policy lapse even if I keep paying?
Yes. If the cost of insurance rises faster than the policy is funded, the shortfall gets pulled from the cash value. Once that runs out, the policy can lapse even though you never missed a payment. This is why an underfunded or poorly designed permanent policy needs a periodic review.
Q6.
Can I get a new policy after a previous lapse?
Yes. You can apply for a new policy, though insurers may ask about prior lapses and you may pay more if you are older or your health has changed since the original application. Comparing carriers matters here, because they weigh that history differently.
Q7.
What if I cannot afford my premiums anymore?
Before letting a policy lapse, ask about lowering the coverage amount, dropping riders you do not need, or switching from annual to monthly payments. On a term renewal, compare the renewal rate against the open market. There are usually options short of losing the coverage entirely.
Q8.
What happens if I die during the grace period?
If the policy is still in force, including during the grace period, your coverage remains in full effect. A claim would generally be paid, typically with the outstanding premium deducted from the benefit.
Keep Your Coverage in Force
A lapse is almost always avoidable, and even after one happens you usually have more options than you think. The hard part is knowing which move is actually cheaper: reinstate, convert, reduce, or shop the market. That is what an independent broker compares for you, across more than 20 Canadian insurers, at no cost to you.
We provide life insurance and segregated fund solutions, including no medical life insurance, term life insurance, permanent life insurance, and critical illness insurance, built around what fits your situation.
Talk it through
Based in Hamilton, serving Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, New Brunswick, and Nova Scotia.
or call 1-877-654-6119





