·

Life Insurance and Distracted Driving Tickets in Canada
Many Canadians assume a distracted driving ticket only affects auto insurance, but life insurers often see it as a clear sign of higher day-to-day risk. This guide explains how distracted driving tickets in Canada can influence life insurance pricing, approval, and eligibility, and what you can do if your record is not perfect.
📖 8-Minute Read
📅 Originally Published: December 03, 2025

Life Insurance and Distracted Driving Tickets in Canada
Many Canadians assume a distracted driving ticket only affects auto insurance, but life insurers often see it as a clear sign of higher day-to-day risk. This guide explains how distracted driving tickets in Canada can influence life insurance pricing, approval, and eligibility, and what you can do if your record is not perfect.
📖 8-Minute Read
📅 Originally Published: December 03, 2025
Distracted driving tickets sit at the intersection of your driving record, lifestyle habits, and risk profile, which means they can matter more to life insurers than many people expect. Underwriters look beyond one-off mistakes and focus on patterns, recency, and severity when they decide whether you qualify for preferred, standard, or rated coverage in Canada.
In the sections ahead, you will see how different types of driving violations show up in an application, how insurers in Canada typically review your record, and which strategies can help you present a stronger file even if you have distracted driving or other tickets on your abstract. The goal is not to scare you, but to give you clear, practical next steps so you can choose the right coverage and timing for your situation.
In this Article:
- Overview: How Distracted Driving Shows Up in a Life Insurance Application
- Risk Tiers: How Insurers Classify Distracted Driving, Minor, and Major Violations
- Underwriter’s View: What Driving Records Really Signal About Risk
- Recency Matters: How Long Distracted Driving Affects Life Insurance Eligibility
- Hidden Traps: Common Mistakes Canadians Make With Driving Records
- Insurer Differences: Which Carriers Are Stricter About Distracted Driving?
- Application Strategy: Best Timing and Preparation for Applicants With Tickets
- Cost Factors: When Tickets Actually Increase Life Insurance Rates
- Get Expert Help and Life Insurance Quote
- Case Studies
- Frequently Asked Questions
Overview: How Distracted Driving Shows Up in a Life Insurance Application

Most Canadians are surprised to learn that a distracted driving ticket can influence life insurance decisions because insurers see it as a sign of behavioural risk, not just a traffic mistake. Underwriting teams review your driving abstract the same way they look at medical records, searching for patterns that predict future claims.
Unlike auto insurance, the question for life insurers is not who caused a collision, but whether your driving history suggests a higher likelihood of preventable accidents. Distracted driving is one of the strongest indicators of this pattern, which is why even a single handheld-device ticket may be reviewed carefully.
Why Driving Records Matter in Life Insurance
Driving behaviour gives insurers a snapshot of your day-to-day decision-making, your level of risk exposure, and how predictable your lifestyle appears. A clean record shows consistency. Multiple or recent tickets may signal elevated risk even in healthy applicants.
💡 Quick Insight: Life insurers often view distracted driving more seriously than a mild speeding ticket because it reflects a behaviour choice rather than a momentary lapse.
Insurers do not treat every violation the same. They evaluate distracted driving through the lens of **recency, frequency, and severity**, which determines whether your rates stay preferred, drop to standard, or move into rated territory. The rest of this guide explains those differences with clear comparisons and advisor-level context so you can navigate your application with confidence.
Getting life insurance with a distracted driving ticket is usually very possible, but many applicants lose out on better pricing because of avoidable timing and disclosure errors. A quick conversation with an advisor can help you sidestep the issues that underwriters watch closely.
- Applying too soon after a distracted driving ticket.
- Not knowing which insurers are more flexible about driving history.
- Overlooking how multiple small violations combine into a risk pattern.
Our licensed Canadian advisors help you understand how your driving record affects your application so you can move forward with clarity and confidence.
Risk Tiers: How Insurers Classify Distracted Driving, Minor, and Major Violations
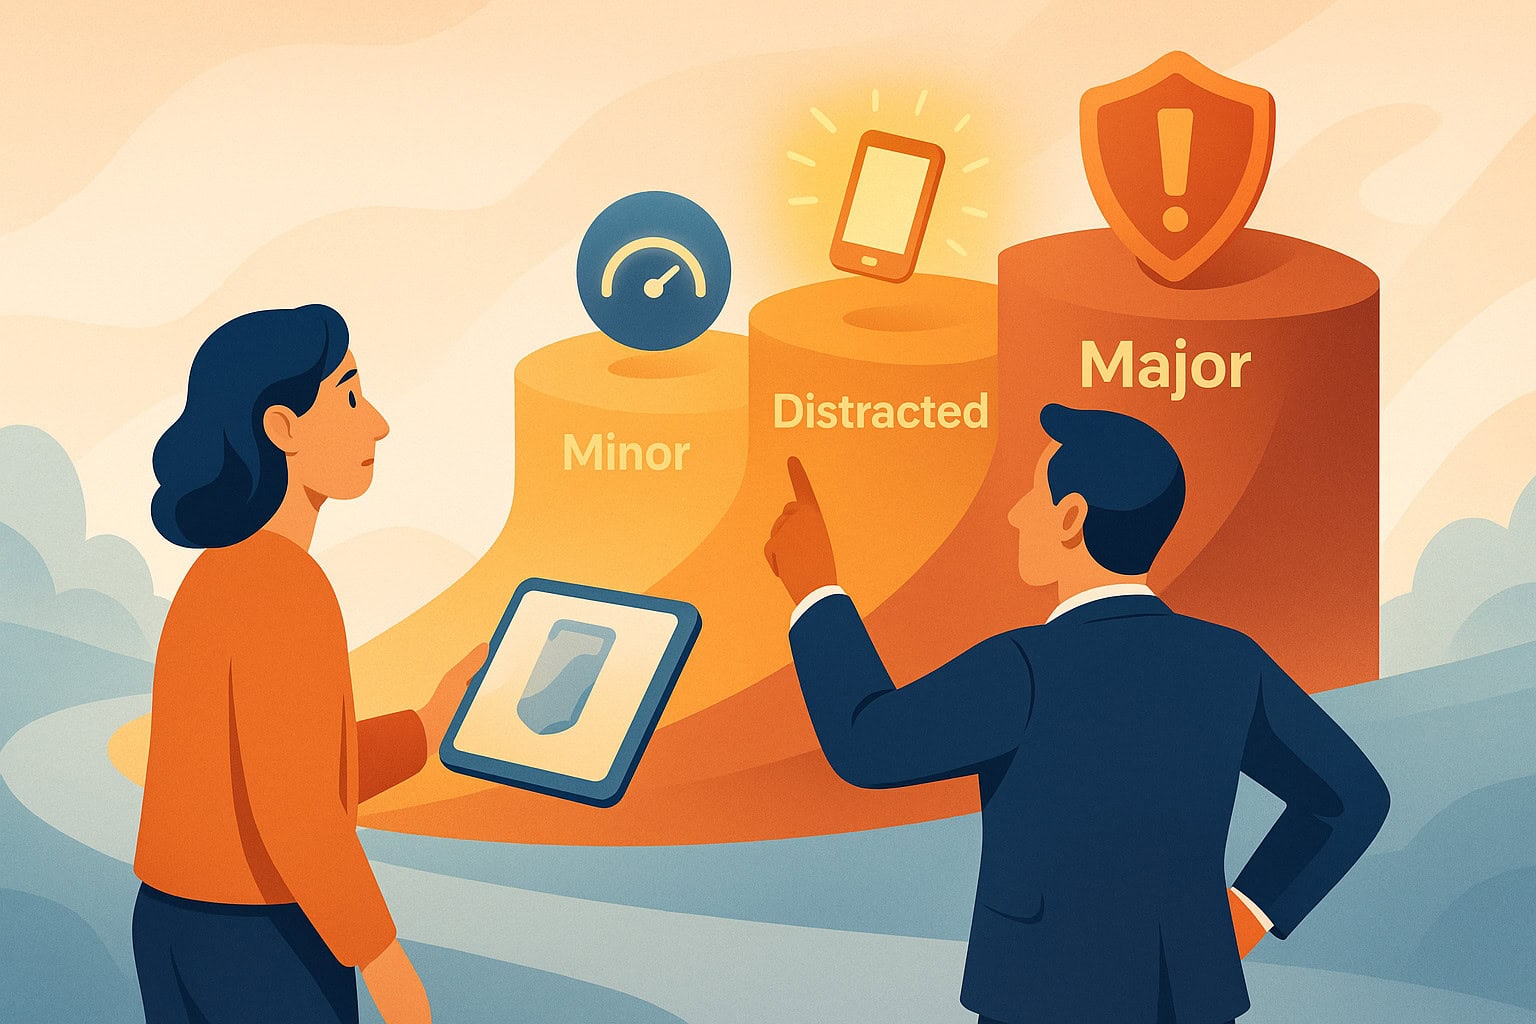
Life insurers group violations into tiers because each category signals a different level of behavioural risk. Distracted driving sits in an unusual middle zone, often treated as more serious than a minor speeding ticket but not as severe as criminal driving charges. Understanding which tier your ticket falls into helps you anticipate how your premiums may shift.
Most Canadian insurers separate violations into three broad buckets: minor infractions, distracted driving or handheld-device offences, and major violations that indicate a substantial risk pattern. Each tier affects eligibility, pricing, and preferred-rate qualification in different ways.
Three Common Driving Violation Categories
- Minor violations, such as low-level speeding or rolling stops, rarely affect approval unless there are several within three years.
- Distracted driving tickets sit in a middle category because they show a behavioural habit linked to preventable accidents.
- Major violations like DUI or careless driving often trigger higher premiums or limited carrier options.
📝 Advisor field note: Many underwriters view distracted driving as a “behaviour consistency” test, which means recency often matters more than the fine itself.
Table 1: How Insurers Classify Driving Violations in Canada
A comparison of violation types and how they influence risk categories.
| Violation Type | Typical Category | Underwriting Impact | Likely Result | Notes |
|---|---|---|---|---|
| Minor speeding | Minor | Low concern unless repeated | Preferred or standard | Often ignored if isolated |
| Handheld device / texting | Intermediate | Moderate concern, behavioural risk | Standard or mild rating | Recency plays a major role |
| Excessive speeding | Intermediate / Major | Higher risk signal | Standard or rated | Impact varies by insurer |
| Careless driving | Major | Significant concern | Rated or possible decline | Often needs a stability period |
| DUI | Major | Severe risk indicator | Rated or postpone | May trigger extra medical review |
- Minor speeding: Minor → Low concern → Preferred or standard if not repeated.
- Handheld/texting: Intermediate → Behavioural risk → Standard or mild rating.
- Excessive speeding: Intermediate or Major → Higher concern → Standard or rated.
- Careless driving: Major → High concern → Rated or possible decline.
- DUI: Major → Severe risk → Rated or postponed with extra review.
Underwriter’s View: What Driving Records Really Signal About Risk
When an underwriter looks at your file, a distracted driving ticket is not just a line on your abstract, it becomes part of your overall risk story. They compare your driving history with your age, occupation, health, and lifestyle to decide whether your behaviour feels predictable and low risk or more volatile.
Most Canadian life insurers pull a driving record for applicants above certain coverage amounts, or when something in the application hints at higher accident exposure. A clean abstract supports preferred rates, while multiple infractions, especially distracted driving, may push you toward standard or rated pricing even if your health is otherwise excellent.
What Underwriters Look For Beyond the Ticket Itself
Underwriters focus less on the exact fine amount and more on patterns such as how often violations occur, whether they are escalating, and how recently they happened. An isolated distracted driving ticket three or four years ago can be viewed very differently than two or three tickets in the last 24 months.
- Frequency: Several violations in a short window may signal a habit rather than a one-time mistake.
- Recency: Tickets in the last one to two years usually carry more weight than older infractions.
- Combination of risks: Distracted driving plus excessive speeding or other major violations can quickly trigger ratings.
From an underwriting perspective, the goal is to decide whether insuring you feels like a reasonable, long-term commitment. A well-structured application, often built with help from an advisor who understands Canadian underwriting, can highlight your positive stability factors and guide you toward suitable coverage, including options like term life insurance quotes in Canada when they fit your budget and goals.
Recency Matters: How Long Distracted Driving Affects Life Insurance Eligibility
For most insurers, the age of your distracted driving ticket has a stronger influence on your application than the ticket itself because recency helps predict current behaviour. A violation from four years ago may have little impact, while one within the last 12 to 24 months can shape whether you qualify for preferred, standard, or rated pricing.
Canadian life insurers typically evaluate driving history in three windows: the past 12 months, the past 24 to 36 months, and the full three to five year period. Each of these ranges signals a different level of stability and behavioural consistency, which directly affects underwriting outcomes.
How Long Distracted Driving Stays Relevant
Most distracted driving tickets remain on your Ontario driving abstract for three years, but insurers may assess their underwriting impact for up to five years depending on the carrier. The closer the ticket is to your application date, the more likely it is to affect pricing and eligibility.
📌 Key Takeaway: Many insurers require a full 24 months without any new violations before considering applicants for preferred pricing again.
The table below outlines how insurers generally treat different recency windows and what applicants can expect when applying for coverage with a recent distracted driving ticket.
Table 2: How Recency Affects Life Insurance Outcomes
A look at typical underwriting responses based on when the violation occurred.
| Recency Window | Insurer Concern Level | Typical Underwriting Response | Likely Outcome | Notes |
|---|---|---|---|---|
| 0–12 months | High | Full review of driving history | Standard or mild rating | Preferred usually not available |
| 12–24 months | Moderate | Depends on additional violations | Standard often possible | Improved odds if isolated |
| 24–36 months | Low to Moderate | Viewed more as past behaviour | Standard or preferred possible | Clean record since makes a big difference |
| 36–60 months | Low | Minimal impact for most carriers | Preferred likely | Few insurers look beyond 3 years |
- 0–12 months: High concern → Standard or mild rating.
- 12–24 months: Moderate concern → Standard often achievable.
- 24–36 months: Lower concern → Standard or preferred possible.
- 36–60 months: Low concern → Preferred likely for most carriers.
Hidden Traps: Common Mistakes Canadians Make With Driving Records
Many Canadians assume a distracted driving ticket only affects their auto insurance, but life insurers often treat it as a signal of consistent behavioural risk. Misunderstanding how these tickets show up in underwriting can lead applicants to make avoidable mistakes that cause higher premiums or unnecessary delays.
Some applicants also believe they should wait until the ticket “falls off” their driving abstract, not realizing that insurers often assess violations on a 3 to 5 year timeline depending on the carrier. A poorly timed application can affect eligibility even if everything else in your file looks solid.
Where Applications Commonly Go Off Track
- Not disclosing a recent ticket because they think insurers won’t check the driving abstract.
- Applying too soon after receiving a handheld device ticket, missing the chance for better pricing later.
- Assuming all insurers treat distracted driving the same when underwriting approaches vary widely.
- Ignoring combinations of risk factors like speeding plus distracted driving, which raises concern dramatically.
If you have multiple violations or a ticket within the last one to two years, strategic timing and a well-prepared application can help highlight stability and responsible behaviour. Small adjustments can make a noticeable difference in how underwriters interpret your record.
Insurer Differences: Which Carriers Are Stricter About Distracted Driving?
Not all life insurers in Canada treat distracted driving tickets the same way. Some carriers weigh them heavily because they indicate behaviour-based risk, while others look more at patterns over time. This is why two applicants with identical driving histories can receive very different pricing depending on the insurer.
In general, insurers fall into three categories: those with stricter behavioural underwriting, those that focus on recency and frequency, and those that only react strongly when distracted driving is paired with other violations such as excessive speeding or careless driving.
Why Insurer Approach Matters
Your approval outcome can shift significantly based on which carrier you apply to. Some companies will still consider preferred rates after a single, older distracted driving ticket, while others may require three full years of clean driving before reconsidering. Working with an advisor helps match your file to the right insurer philosophy.
💡 Quick Insight: Some insurers treat distracted driving nearly as serious as excessive speeding, while others view it as a mid-tier risk that improves quickly with time.
The table below compares how insurers generally approach distracted driving in Canada, using typical underwriting patterns. Carrier philosophies vary, which is why selecting the right insurer can make a meaningful difference in your final pricing.
Table 3: How Canadian Insurers Vary in Their Treatment of Distracted Driving
A comparison of underwriting approaches across typical insurer categories.
| Insurer Type | General Underwriting Stance | Impact of Recent Distracted Driving | Likely Pricing | Notes |
|---|---|---|---|---|
| Strict behavioural-focused carriers | High sensitivity to lifestyle risk signals | Strong impact for violations <2 years old | Standard or rated | Often require longer clean periods |
| Moderate/flexible carriers | Balanced view of patterns and recency | Moderate impact for violations <24–36 months | Standard, sometimes preferred | Best match for isolated tickets |
| Outcome-focused carriers | Emphasis on combinations of violations | Higher concern only with multiple recent violations | Standard or preferred | Favourable when the rest of the file is clean |
- Strict carriers: High concern for recent tickets → Standard or rated.
- Moderate carriers: Balanced view → Standard or sometimes preferred.
- Outcome-focused carriers: Concern mainly when violations stack → Preferred possible.
Application Strategy: Best Timing and Preparation for Applicants With Tickets
When you have a distracted driving ticket on your record, the strategy behind your application becomes just as important as the coverage itself. The right timing and preparation can help you secure better pricing and avoid unnecessary underwriting friction, especially if the violation is recent.
Insurers look closely at behavioural consistency. Even a small delay in applying, or presenting cleaner documentation, can shift an application from rated to standard or preferred. This makes your approach and your advisor’s guidance critical.
Smart Timing Choices
If your ticket is within the last year, waiting until the 12–24 month window can improve your chances of receiving stronger rates. For older tickets, applying sooner may offer no disadvantage, particularly if your driving record is clean since.
- ✅ Request your current driving abstract to ensure you know exactly what underwriters will see.
- ✅ Confirm whether your ticket falls within the insurer’s review period (often 3 to 5 years).
- ✅ Prepare a clear record of time since last violation to support clean-behaviour evidence.
Working with an advisor who understands the different underwriting philosophies across Canadian insurers can help align your application with carriers that are more flexible and pattern-focused, increasing the chance of a smoother approval.
Cost Factors: When Tickets Actually Increase Life Insurance Rates
Not every distracted driving ticket leads to higher premiums, but the ones that do usually fall into patterns that insurers consider predictive of future risk. Underwriters evaluate how the violation fits within your broader lifestyle, driving habits, and recent history to determine whether pricing should remain preferred, drop to standard, or move into a rated category.
Life insurance pricing shifts when the driving record shows more than an isolated lapse. A distracted driving ticket combined with additional violations, or occurring within the last 12 to 24 months, may trigger rate adjustments that many applicants do not expect. This makes understanding how insurers classify risk essential before applying.
What Determines Whether Pricing Goes Up?
- Recency: Newer tickets almost always carry more weight than older ones.
- Frequency: Multiple distracted driving tickets or combinations with speeding can elevate risk tiers.
- Insurer philosophy: Some carriers are far more conservative about driving behaviour than others.
- Total risk picture: Underwriters weigh your driving record against health, lifestyle, and occupation.
💡 Quick Insight: A single distracted driving ticket rarely causes a major pricing jump by itself, but it can prevent preferred rates until enough time has passed.
The table below outlines the typical pricing impact Canadian applicants may see depending on the number and type of violations on their abstract.
Table 4: When Driving Violations Increase Life Insurance Premiums
How different violation patterns influence typical pricing outcomes.
| Violation Pattern | Insurer Concern Level | Typical Pricing Impact | Eligibility Outcome | Notes |
|---|---|---|---|---|
| One distracted driving ticket | Moderate | No increase, but preferred may be restricted | Standard or preferred (case by case) | Recency heavily influences result |
| One distracted + one minor speeding | Moderate to High | Slight rating possible | Standard or mildly rated | Behaviour pattern becomes key |
| Two distracted driving tickets | High | Moderate rating likely | Rated, limited preferred options | Carrier differences are significant |
| Distracted + excessive speeding | High | Noticeable rate increase | Rated or postpone | Often reviewed as a combined risk |
| Distracted + major violation (careless, DUI) | Very High | Major rating or postponement | Rated, postpone, or decline | Usually requires stability period |
- One distracted ticket: Preferred may be limited → Standard or preferred possible.
- Distracted + minor speeding: Slight rating → Standard or mild rating.
- Two distracted tickets: Higher concern → Rated likely.
- Distracted + excessive speed: Rating increase → Rated or postpone.
- Distracted + major violation: Very high concern → Rated, postpone, or decline.
Case Studies
Case 1: Jordan, 32, Ontario
Profile: Healthy non-smoker. One distracted driving ticket 14 months ago. No other violations.
- Problem: Worried the recent handheld device ticket would block preferred rates.
- Approach: Advisor matched him with a carrier that weighs patterns over single incidents.
- Resolution: Approved at standard pricing with an option to reapply later for preferred.
Takeaway: A single distracted driving ticket rarely prevents strong coverage when the rest of the record is clean.
Case 2: Priya, 45, Alberta
Profile: One distracted driving ticket + one minor speeding ticket in 24 months.
- Problem: Concerned that multiple violations would lead to a decline or high rating.
- Approach: Advisor prepared a detailed timeline highlighting recent clean behavioural patterns.
- Resolution: Approved at a mild rating with an option to improve after 12 clean months.
Takeaway: Demonstrating stability after combined violations can significantly improve underwriting outcomes.
Case 3: Marco, 51, British Columbia
Profile: Two distracted driving tickets within three years, no speeding violations.
- Problem: Thought multiple handheld-device tickets guaranteed a decline.
- Approach: Advisor recommended applying to a carrier that focuses on combined risk patterns rather than single categories.
- Resolution: Approved with a moderate rating and no postponement.
Takeaway: Even repeat distracted driving tickets may be insurable when other risk factors are stable.
FAQ – Frequently Asked Questions
Does a distracted driving ticket always raise life insurance rates?
No. A single distracted driving ticket often affects preferred rates more than base pricing. Many applicants still qualify for standard coverage depending on recency and overall driving history.
How long do insurers look at distracted driving tickets?
Most insurers consider them for 3 to 5 years, though the strongest impact is usually within the first 12 to 24 months.
Can I still get preferred rates after a distracted driving ticket?
Yes, but preferred rates typically require a period of clean, violation-free driving, often 24 to 36 months depending on the carrier.
Do insurers treat texting while driving differently from speeding?
Yes. Distracted driving is often considered more directly tied to preventable accidents, so insurers may view it more seriously than a low-level speeding ticket.
Will multiple distracted driving tickets cause a decline?
Not necessarily. Multiple tickets may lead to a rating or postponement, but many applicants are still insurable if other risk factors are stable.
Do life insurers check my driving record automatically?
Most insurers check your driving abstract when you apply for larger coverage amounts or when something in your file suggests elevated accident risk.
Is it better to wait before applying if I recently received a distracted driving ticket?
Often yes. Waiting until the violation is 12–24 months old can improve eligibility for stronger pricing, depending on the insurer.